Car accident

Protect your rights medical liens explained
After an Accident, Car accident, Health, Legal, Settlement, Why we serve

What You Should Know About Medical Liens?

You did the smart thing after your Tampa accident and used your health insurance to get the care you needed. Then you hear a word that makes your stomach drop: lien. Suddenly it sounds like everyone who paid a medical bill wants a piece of your settlement. Here’s what a medical lien really is, who can claim one in Florida, and why the right approach often leaves more money in your pocket, not less. TL;DR — QUICK SUMMARY A medical lien is a legal claim to be repaid from your settlement by whoever covered your accident-related medical care. Your health insurer can seek repayment through subrogation, but under Florida Statute 768.76 its lien is reduced by its share of your attorney’s fees and costs. Medicare and Medicaid have far stronger repayment rights that cannot be ignored, with Medicaid’s lien attaching automatically under Florida Statute 409.910. Using health insurance usually shrinks the bill, because insurers pay providers at reduced negotiated rates, so less comes out of your recovery. Most liens are negotiable, and resolving them before you sign is how you protect what you actually take home. The Reyes Firm Worried a Lien Will Eat Your Settlement? Let us protect what you take home from your Tampa claim. Had a bad day? Contact Us Now $10,000 Florida PIP pays before health insurance Fla. Stat. 627.736 Pro Rata Health insurer liens cut by their share of fees Fla. Stat. 768.76(4) Automatic Medicaid’s lien attaches by law Fla. Stat. 409.910(6) 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) What is a medical lien, and why does it come out of your settlement? A medical lien is a legal claim to be repaid from your settlement by an insurer, provider, or government program that covered your accident-related medical care. The idea behind it is simple: those bills were paid on the understanding that, if someone else caused your injuries, the money would be paid back out of whatever you recover from the at-fault party. This matters most when your injuries are serious and your bills are large, such as after a catastrophic crash. A lien does not reduce what the at-fault party owes you. It determines how much of your recovery you actually keep after the people who paid your bills are reimbursed, which is why understanding and controlling these liens is a real part of winning your case. Who can put a lien on your personal injury settlement in Florida? Several different parties can claim repayment, and they do not all have the same rights. The most common lien holders are your private health insurer, which may seek reimbursement through subrogation; hospitals, which in some Florida counties, including parts of the Tampa and Hillsborough County area, can assert a lien under a local ordinance; and government programs like Medicare and Medicaid, which have powerful repayment rights set by statute. There is also a fourth situation. If you had no health insurance, or chose not to use it, a doctor may have treated you under a Letter of Protection, which is an agreement to wait and be paid directly from your settlement. That arrangement creates a lien-like claim on your recovery too. The first job in any case is identifying every one of these claims, because a lien you forget about does not disappear, it follows you. How does health insurance subrogation actually work? When your health insurer pays accident-related bills, it often has a right to be paid back out of your settlement, and that right is called subrogation. Under Florida Statute § 768.76, a health insurer that has properly asserted this right can be reimbursed only from what you actually recover, and its claim is reduced by its pro-rata share of the attorney’s fees and costs you paid to obtain that recovery. Two things make this far better for you than it first sounds. The insurer is usually repaid based on the discounted rate it actually paid the provider, not the much higher billed amount, and that repayment is then cut down by its share of your legal costs. The main exception is a self-funded employer health plan governed by federal ERISA law, which can have stronger reimbursement rights than a state-regulated plan, so the type of plan you have genuinely matters to the outcome. 💡 Did You Know? Under Fla. Stat. § 768.76, a health insurer’s reimbursement is limited to what you actually recovered and must be reduced by the insurer’s pro-rata share of your attorney’s fees and costs. Combined with the discounted rates insurers pay providers, this often means using your health insurance leaves you with more money than letting the full medical bill ride to settlement. Source: Fla. Stat. § 768.76, leg.state.fl.us. What about Medicare and Medicaid liens? Government liens are a different animal, and they cannot be ignored. Florida Medicaid is automatically subrogated to your claim and holds an automatic lien for the full amount it paid under Florida Statute § 409.910, while Medicare’s repayment rights come from federal law and function as a so-called super lien on your recovery. The good news is that the amount these programs actually collect can often be reduced, for Medicaid by reasonably allocating your settlement to past medical expenses, and for Medicare through its conditional-payment resolution process. The bad news is that disbursing your settlement without addressing them is a serious mistake, because the government can pursue repayment afterward, with interest. These claims come up in any case with major medical care, including large truck and commercial vehicle settlements. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Watch: How medical liens affect your settlement In this short video, attorney Edward Reyes explains how medical liens work and why using your health insurance can still be the smart move after an accident. Tampa personal injury

After A Car Accident, Car accident, Car Search, Legal, Why we serve

Is your Car Damaged?

We love if we could help you with your property damage, and we do. However, the problem with property damage is that there are adjusters involved, there are people that need to go look at your car, there are people that need to fix your car and there are salvage yards and a lot of things. A lot of these companies need appointments. So, what happens is that when we call many times, we leave a voicemail and they call us back. Leave a voicemail, or let’s say they talk to us. Now, we need to coordinate with you on what your schedule is to try to figure out if we coordinate back to the insurance company to get their adjuster to look at your car or the collision center or whatever the case is. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411So, many times, as far as property damage goes, we can help you if you get stuck and if you have a problem, we can definitely help you, but we are not sure about your schedule. And if we do know your schedule, it’s gonna make the process shorter or much longer because we don’t know your personal schedule that way you can meet with your adjusters, the car collision place, mechanics, or rental companies. That is why it is okay to talk to adjusters only for property damage. Do not talk to them at all for injuries because again, they are trying not to pay. So, it is very important that if you talk to them about property damage, you only talk about your car, to get an appointment, to take it to an adjuster, mechanic, or body shop. If you have questions, call us at 833-4-BAD DAY (833-422-3329).   (Transcript from the video, transcribed but not reviewed)

Why insurance undervalues your pain
After A Car Accident, After an Accident, Car accident, Legal, Settlement, Why we serve

Why Insurance Company Undervalue your Pain?

You’re in real pain after your Tampa car accident, but the insurance adjuster keeps acting like it’s no big deal. They weren’t in the crash. They don’t feel your back seize up every morning. To them, you are a stack of paper, and if that paper doesn’t tell the right story, they will value your pain at close to nothing. Here’s why that happens, and how to make sure your pain is taken seriously. TL;DR — QUICK SUMMARY Insurance companies undervalue pain because it is subjective, and Florida’s no-fault law only makes them pay for it when your injury is permanent. Your PIP coverage pays 80% of medical bills and 60% of lost wages up to $10,000, but it pays nothing for pain and suffering. To recover pain and suffering from the at-fault driver, your injury must meet one of four permanency categories under Florida Statute 627.737. Gaps in treatment and old injuries are the two tools insurers use most to argue your pain is not real or not from the crash. You have two years from the crash to file a lawsuit under Florida Statute 95.11(3)(a), and consistent medical proof is what protects your claim’s value. The Reyes Firm Is the Insurance Company Downplaying Your Pain? Get your Tampa injury claim valued fairly. Had a bad day? Contact Us Now 4 Injury categories that allow pain & suffering Fla. Stat. 627.737(2) $10,000 Standard Florida PIP limit Fla. Stat. 627.736 80% Of medical bills PIP pays, none for pain Fla. Stat. 627.736 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) Why do insurance companies undervalue your pain after a car accident? Insurance companies undervalue your pain because pain is subjective, hard to measure, and easy to dispute, and because Florida law only forces them to pay for it under specific conditions. A broken bumper has a price tag. The ache that keeps you from lifting your child or sleeping through the night does not, so the adjuster treats it as negotiable, then looks for reasons to push its value down. The deeper problem is that the insurer only knows you on paper. It has never met you and does not feel what you feel, so it judges your pain entirely by your medical records. If those records show consistent treatment and a clear diagnosis, your pain looks real. If they show gaps, missed appointments, or no imaging, the insurer will argue you must not be hurting much at all. Understanding how that paper trail is read is the first step to protecting what your claim is actually worth. What does Florida’s no-fault system actually pay for your pain? On its own, your no-fault coverage pays nothing for pain and suffering. Florida’s Personal Injury Protection (PIP) coverage under Florida Statute § 627.736 pays 80% of your medical bills and 60% of your lost wages, up to a standard limit of $10,000, and that money covers economic losses only. Pain, suffering, mental anguish, and the loss of enjoyment of your life are non-economic damages, and you can only recover them by stepping outside the no-fault system and pursuing the at-fault driver directly. Florida does not let you do that for every injury, which is exactly the gap insurers rely on. To reach your pain and suffering, you first have to clear a legal bar called the permanency threshold. When can you recover pain and suffering in Florida? You can recover pain and suffering only when your injury meets Florida’s permanency threshold. Under Florida Statute § 627.737(2), you may pursue non-economic damages from the at-fault driver only if your injury involves one of four things: significant and permanent loss of an important bodily function, a permanent injury within a reasonable degree of medical probability, significant and permanent scarring or disfigurement, or death. The phrase that decides most cases is “permanent injury within a reasonable degree of medical probability.” Proving it usually takes more than your word. It takes the right imaging, the right specialist, and a doctor willing to state that your injury is permanent. This is why a thorough diagnosis matters so much, especially for back, neck, and spine injuries where an MRI can reveal disc damage that an X-ray misses, or for head injuries where a traumatic brain injury may need a neurologist rather than a general doctor to document. 💡 Did You Know? Under Florida’s no-fault law, you cannot recover a dollar of pain and suffering from the at-fault driver unless your injury meets one of four permanency categories in Fla. Stat. § 627.737(2), and the permanency normally has to be confirmed by a doctor to a reasonable degree of medical probability. This single requirement is why proper diagnosis can change a claim’s value dramatically. Source: Fla. Stat. § 627.737, leg.state.fl.us. Watch: Why the insurance company says you’re not really in pain In this short video, attorney Edward Reyes explains how insurers use your medical records to argue your pain isn’t serious, and what you can do about it. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411If an adjuster is downplaying what you’re going through, The Reyes Firm offers free consultations and can review your situation at no cost. How gaps in treatment lower the value of your pain Nothing hands an insurer more ammunition than a gap in your treatment. When weeks or months pass with no doctor visits, the adjuster’s argument writes itself: if you were really in pain, you would have kept seeing someone about it. A long delay between the crash and your care, or a stretch where you simply stopped going, becomes their reason to discount how you feel. Consistency is your best answer. Steady, documented treatment shows that your pain is ongoing and real, builds the medical record needed to prove permanency, and removes the insurer’s favorite excuse. The same urgency applies to

Motorcycle Accidents Are Different Than Car Accidents
Accident Injuries & why, After an Accident, Car accident, Injury, Legal, Motorcycles, Uninsured Motorist Coverage, Why we serve

Motorcycle Accidents Are Different Than Car Accidents

Motorcycle accidents are traumatic and the reason why because you don’t have the bumper in a car or airbags to protect you from the impact of a vehicle. In fact, many times you are thrown off your motorcycle and there are major injuries due to do the road rash. Many times, when this happens you have to undergo serious treatment and serious therapy and it’s pretty tragic. In Florida, it is not required for you to wear a helmet, however, it is highly recommended that you wear a helmet for many reasons. One, for your health, to protect your head from a higher impact from traumatic brain injury and on the legal side, the civil side to protect yourself. But also, if you do not have your helmet on, a lot of times what happens is that the insurance company on the other side, the at-fault party’s insurance company will try to deduct the injuries that you have in your head or brain and say anything that your helmet could have protected. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411This is because their stance is, if you had your helmet on, you should have been protected from the impacts or reduce the injuries and damage. It’s very important that you wear your helmet. It is very important that you are safe while keeping your distance from other vehicles. But if you are involved in a motorcycle accident and you are not at fault or even if you are at fault we can still help. It all depends on the facts and the case itself. If you have any questions on this feel free to give us a call at 833-422-3329. (Transcript from the video, transcribed but not reviewed)

Are you Getting a Fair Settlement
Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Legal, Settlement, Why we serve

Are you Getting a Fair Settlement?

So, the insurance company offers you a fair settlement after you involved in an accident? It’s hard to talk about this without laughing because the insurance companies work for the insurance company. Those agents don’t work for you, instead, they work for the insurance company so they’re never going to offer you a fair settlement right off the bat without representation or without fighting them. Their job is to adjust the claims out and pay as little as possible to you for your lost wages, pain, and suffering. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411So, the question or myth is- do they pay you a fair settlement? No, they never pay you a fair settlement off the top. After you find them, you put force, and you show them that you’re not playing around with proper representation and then the settlement becomes fair. So, if you have any questions on this feel free to give us a call at 813.421.3411 and we’ll be more than happy to go through this process with you to help you understand how and what a fair settlement actually is. (Transcript from the video, transcribed but not reviewed)

Don't settle, get expert help
Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Legal, Why we serve

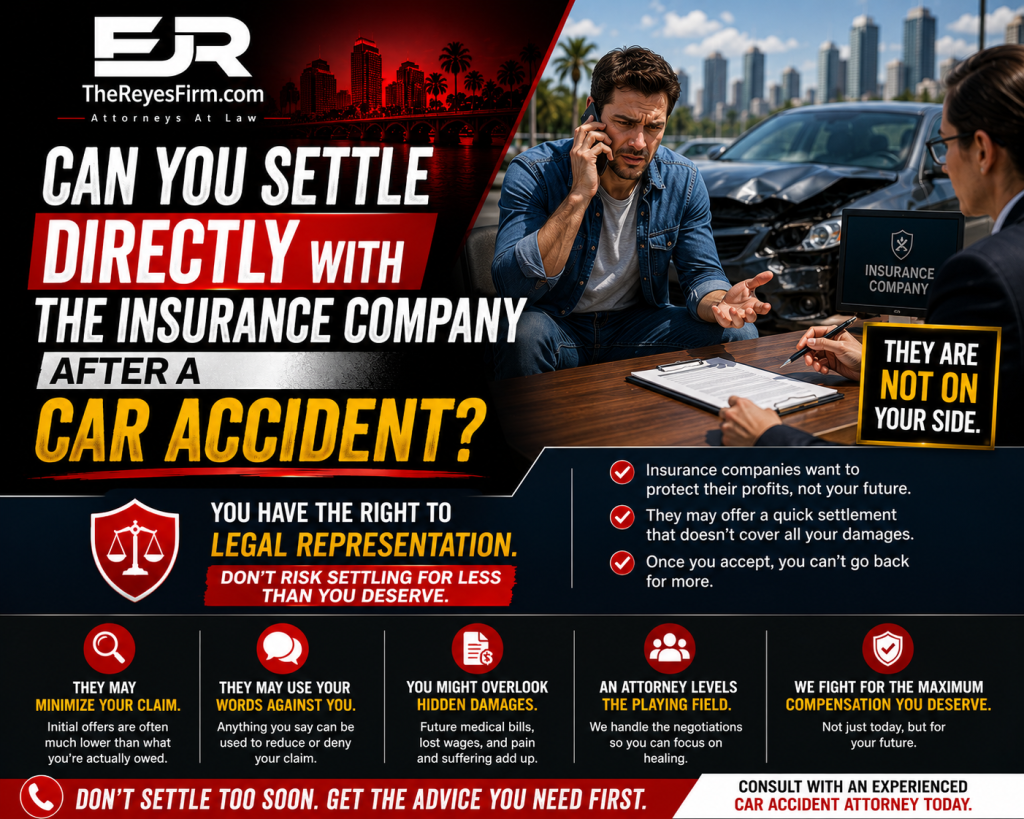
Can You Settle Directly With The Insurance Company After A Car Accident?

You were just going about your day. Then another driver hit you at an intersection. Now your car is damaged, your neck hurts, and the other driver’s insurance company is on the phone offering to “just work this out” with a quick check. Here’s what you need to know before you accept a dollar of it. TL;DR — QUICK SUMMARY Can you settle directly with the other driver’s insurance company? Technically yes. Should you do it alone? Almost never. The adjuster offering you money works for the insurer, and their job is to close your claim for as little as possible. Early offers rarely account for future medical care, lost wages, or injuries that surface days after the crash. Once you sign a release, you usually give up the right to ask for more, even if your condition gets worse. Under Florida Statute 95.11(3)(a), you generally have two years to file a lawsuit, but a signed release can end your claim long before that. A free consultation costs you nothing and tells you what your case is really worth before you decide. The Reyes Firm Did an Insurer Offer to “Work It Out” After a Tampa Crash? Find out what your case is really worth before you sign. Had a bad day? Contact Us Now 2 Years Florida injury filing deadline Fla. Stat. 95.11(3)(a) 14 Days Deadline to seek care for PIP benefits Fla. Stat. 627.736 50% Fault level that bars recovery in Florida Fla. Stat. 768.81 $0 Upfront cost with a contingency fee firm The Reyes Firm Can you work it out with the insurance company yourself? Technically, yes, and that’s exactly why so many people get shortchanged. Nothing in Florida law stops you from negotiating directly with the other driver’s insurer and accepting a settlement on your own. The myth isn’t whether you can. The myth is that doing it alone gets you a fair result. The person calling you is an adjuster, and the adjuster works for the insurance company. Their job is to close your claim for as little money as possible, because every dollar they save is a dollar that stays with their employer. They are friendly, they are professional, and they are negotiating against you the moment they pick up the phone. So the honest answer from The Reyes Firm, a Tampa personal injury law firm, is this: you can work it out yourself, but you usually shouldn’t, and the reason becomes obvious once you see how these offers are built. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your crash to file a personal injury lawsuit. But signing a settlement release ends your claim immediately, no matter how much time is left on that clock. Never sign before you know what your case is worth. Why does settling directly with the other driver’s insurer backfire? Because the first offer is almost always built around what’s visible on day one, not what your injury actually costs you over time. The dented bumper is easy to price. The herniated disc that flares up three weeks later is not, and by then you may have already cashed the check. Attorney Edward Reyes learned this firsthand. After his first car accident as a young man, someone handed him $400 and it seemed like enough. It wasn’t close. The repairs to his car ran over a thousand dollars, and the injuries he felt afterward were worth far more than that. He took the fast money before he understood the real damage, and that lesson is part of why he practices personal injury law today. That story plays out constantly. People try to handle it themselves, accept an early number to make the problem go away, and only later discover the offer didn’t cover their medical bills, their time off work, or the lasting effects of the crash. Once the release is signed, that money is final. 💡 Did You Know? Florida is a no-fault auto insurance state. Under Florida Statute § 627.736, your own Personal Injury Protection (PIP) coverage pays the first portion of your medical bills regardless of who caused the crash, up to a $10,000 minimum, but only if you seek treatment within 14 days. Settling with the other insurer doesn’t change those PIP deadlines. Source: Fla. Stat. § 627.736. Watch: Can You Work It Out With the Insurance Company? In this short video, attorney Edward Reyes busts the myth that you can simply “work it out” with the other side’s insurer, and shares the personal story that shaped how he handles these cases. If you have a settlement offer in front of you and aren’t sure what to do, The Reyes Firm offers free consultations, so you can call 833-4 BAD DAY before you respond. What is a fair settlement actually worth after a Tampa car accident? A fair settlement reflects everything the crash will cost you, not just the bills already on your kitchen table. A complete claim accounts for several categories most people overlook when they negotiate alone: Future medical care, including follow-up visits, physical therapy, imaging, and treatment for injuries that worsen over time Lost wages and lost earning capacity, covering the work you’ve already missed and any long-term limits on what you can do The full diagnosis, since soft-tissue injuries, concussions, and back injuries often don’t show their true severity for days or weeks Property damage done right, repaired or replaced at real cost, not a rounded-down estimate Pain and the disruption to your life, which an adjuster has every incentive to value at zero In a serious or catastrophic crash, the gap between the first offer and the real value of the claim can be enormous. That gap is the insurer’s profit, and it comes directly out of your recovery. 🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are

Pain and suffering compensation guide
Accident Injuries & why, After an Accident, Car accident, FAQ, Health, Injury, Legal, Settlement

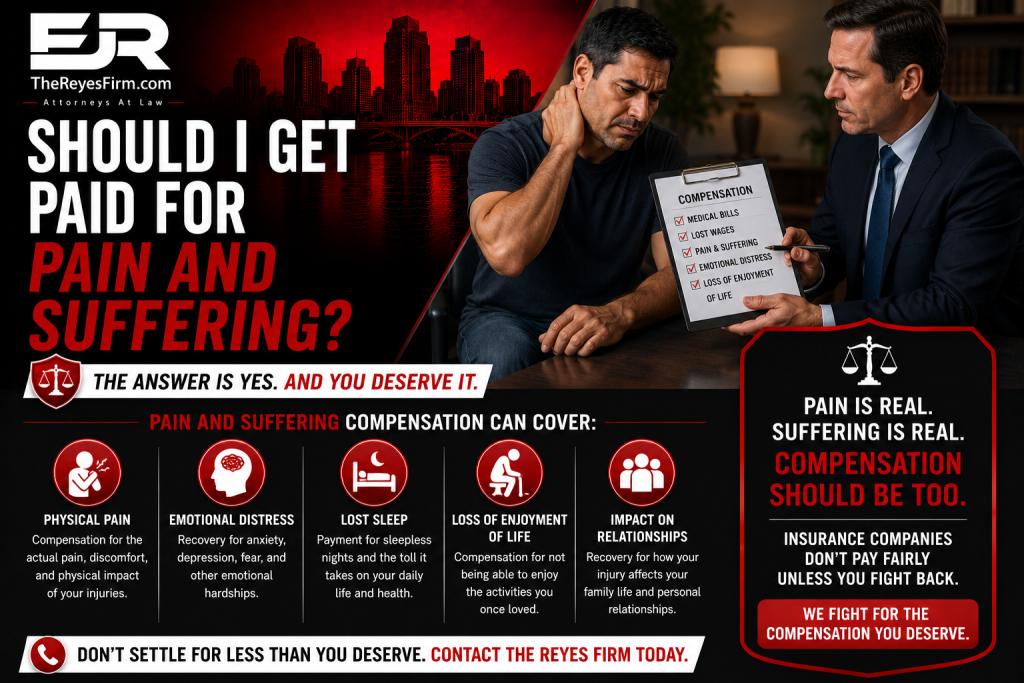
Should I Get Paid for Pain and Suffering? | Tampa, FL

You’re in real pain. The medical bills are only part of it — you can’t sleep, you can’t do the things you used to love, and a car accident you didn’t cause turned your daily life upside down. So can you actually be paid for that suffering, not just your bills? Here’s how pain and suffering compensation works in Florida. TL;DR — QUICK SUMMARY Yes, you can recover money for pain and suffering after a Florida crash that wasn’t your fault, but only if your injuries clear Florida’s serious-injury threshold. Pain and suffering is a type of non-economic damage. It covers physical pain, mental anguish, loss of enjoyment of life, and inconvenience, on top of your medical bills and lost wages. Florida’s no-fault system means your own PIP pays your first $10,000 in bills regardless of fault, but pain and suffering generally comes from the at-fault driver once you meet the injury threshold under Florida Statute § 627.737. There’s no fixed formula. The value depends on the severity and permanence of your injuries, your treatment, and how the crash has changed your life. You have two years from the date of your crash to file a personal injury lawsuit under Florida Statute § 95.11(3)(a). Uninsured/underinsured motorist coverage can also be a source of recovery if the at-fault driver has no insurance. The Reyes Firm Hurt and in Pain After a Tampa Crash? Find out what your pain and suffering claim may be worth. Had a bad day? Contact Us Now 2 Years Florida statute of limitations Fla. Stat. § 95.11(3)(a) $10,000 Florida PIP minimum coverage Fla. Stat. § 627.736 4 Ways To meet FL injury threshold Fla. Stat. § 627.737(2) 50% Fault bar to recovery in FL Fla. Stat. § 768.81 Can you get paid for pain and suffering after a Florida car accident? Yes, you can be compensated for pain and suffering, as long as the crash wasn’t your fault and your injuries are serious enough to clear Florida’s threshold. Whether it actually happens depends on the facts: how badly you were hurt, whether the at-fault driver had insurance, and whether they have assets to reach if they didn’t. If you’re in genuine pain, you should be able to recover for that pain, for the loss of enjoyment of life, for time you couldn’t work, and for the damage to your vehicle. That’s the principle. In practice, it doesn’t happen automatically, which is why how you handle your claim matters so much. One of the biggest obstacles is uninsured drivers. Florida has a high number of people driving without adequate coverage, which is exactly why carrying uninsured/underinsured motorist coverage on your own policy is one of the smartest protections you can have. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Wait too long and you can lose the right to recover anything for your pain and suffering, no matter how badly you were hurt. Don’t let the clock run out. What counts as pain and suffering in a Florida injury claim? Pain and suffering is a category of non-economic damages, meaning losses that don’t come with a receipt. Unlike a medical bill or a paycheck stub, these harms are real but harder to put a dollar figure on, which is exactly why insurers fight them. In a Florida injury claim, pain and suffering can include physical pain from your injuries, mental anguish and emotional distress, loss of enjoyment of life, inconvenience and disruption to your routine, and the lasting effect of scarring or disfigurement. A serious back or neck injury that limits you for years carries very different value than a sprain that heals in weeks. These damages sit on top of your economic damages, which cover medical bills, future treatment, lost wages, and lost earning capacity. Together they make up the full value of your claim. Watch: Should you get paid for pain and suffering in Tampa? In this short video, Tampa personal injury attorney Edward Reyes explains when you can recover for pain and suffering after a Florida crash and what factors affect it. If you’re hurting and unsure whether your injuries qualify, The Reyes Firm offers a free case review to walk you through where you stand. How does Florida’s injury threshold affect pain and suffering? Florida’s injury threshold is the gateway to recovering pain and suffering from an at-fault driver. Because Florida is a no-fault state, your own Personal Injury Protection (PIP) coverage pays your first medical bills regardless of who caused the crash, but PIP does not pay for pain and suffering. To step outside no-fault and pursue non-economic damages from the at-fault driver, your injury generally has to meet the serious-injury threshold in Florida Statute § 627.737. That statute recognizes injuries involving significant and permanent loss of an important bodily function, permanent injury within a reasonable degree of medical probability, significant and permanent scarring or disfigurement, or death. Whether your injury clears that threshold is often the central fight in a Florida case. Strong medical documentation and the right expert opinions are what move an injury from “soft tissue” in the insurer’s eyes to a permanent, compensable harm. 💡 Did You Know? Florida’s PIP system pays up to $10,000 in medical bills and lost wages no matter who caused the crash under Fla. Stat. § 627.736 — but PIP never pays for pain and suffering. Those damages only become available once your injury meets the threshold in Fla. Stat. § 627.737. How is pain and suffering calculated in Florida? There is no fixed formula for pain and suffering in Florida. Two cases with similar bills can settle for very different amounts depending on how the injuries affect each person’s life, which is why a number pulled from an online calculator means little. In practice, the value turns on factors like the severity and permanence of your injuries, the length and intensity of your treatment, whether you’ll

Pedestrian
Car accident, Pedestrian Accident

Pedestrian Safety

Everyone is busy during the holidays. There are just so many things to do here and there. People, in one way or the other, have to go out in the streets and do something. Unfortunately, this is also the time when there is an increase in pedestrian deaths by cars. But the worse thing is, especially when the injury seems minor, people do not report the incident immediately. Most of them would think that it is not something they should worry about. But this is not the case. Not reporting it right away might just be one of the biggest mistakes one can ever make. Here is a Tampa Attorney, Edward Reyes, recommending what needs to be done when such a thing happens and the importance of doing so. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411 Video Transcript: Reporter: We’ve reported it in the past Tampa Bay is one of the top areas in the country for pedestrian deaths by cars. One Tampa attorney Edward Reyes warns there’s a spike in accidents over the holidays due to travelers in town, but he also sees a trend of people waiting to report an accident until after the holidays, something he never recommends. If you find yourself in a pedestrian-car accident, he says the first thing to do is to report it right away. Edward Reyes: Take a picture of the license plate possible in case that person drives away. There are many cases that there’s a lot of hit and runs. This may be needed also when you call law enforcement. The reason why is because you need to document the actual incident itself and you need to call an attorney. It sounds kind of weird but it is because the insurance company on the other side, let’s say the at-fault party, their insurance company is looking for ways to incriminate you in some way because their adjusters are trying to adjust your claims down. Reporter: Reyes says just in Hillsborough County there are between two and three thousand car accidents every month. For more information, call 813.421.3411 today. (Transcript from the video, transcribed but not reviewed)

What to Do If My Car Insurance Company Won’t Pay
Accident Injuries & why, After A Car Accident, After an Accident, Car accident, FAQ, For Parents, For Teens, Legal, Moped Accidents, Road Accidents, Settlement, Why we serve

Who is paying your medical bills if you don’t own a car or have insurance?

So what happens if you are involved in a car accident, it’s not your fault, but you don’t have insurance, but you don’t have a car? What happens then? There are a couple of things. One if you live in a household that somebody has a car and insurance you may be covered under a resident relative. Two, if you do not live in a household that someone has insurance or a car you may be covered by the person that crashed into, their auto insurance company may cover you for personal injury protection. Three, if none of those apply, you can still be covered under the other person’s policy if they have bodily injury coverage. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411 It won’t cover you for medical coverages as far as your personal injury protection but it will cover you for recovery for pain and suffering and then eventually it will pay back the medical expenses if you’ve incurred any. Give us a call at 813.421.3411 today. (Transcript from the video, transcribed but not reviewed)

Scroll to Top