You were rear-ended on your way through Tampa, you did everything right, and you filed your claim. Now the days are passing with no answer, the medical bills are arriving, and you’re starting to wonder whether the insurance company is ever going to call back. Here’s exactly how long they have to respond after a Florida car accident, and what you can do when they drag their feet.
TL;DR — QUICK SUMMARY
- Your own PIP insurer must pay or deny your claim within 30 days of receiving written notice under Florida Statute 627.736(4)(b).
- Insurers are expected to acknowledge a new claim promptly, generally within about 14 days, even though the full investigation takes longer.
- Once you and the insurer agree on a settlement, they have 20 days to pay it under Florida Statute 627.4265, or interest starts to accrue.
- A claim against the at-fault driver’s insurer has no fixed response deadline, which is why those claims can stall for months.
- You have two years from the crash to file a personal injury lawsuit under Florida Statute 95.11(3)(a), so an insurer’s delay should never push you past that line.
The Reyes Firm
Is the Insurance Company Ignoring You?
Get clear answers about your Tampa car accident claim. Had a bad day?
How many days does an insurance company have to respond after a car accident in Florida?
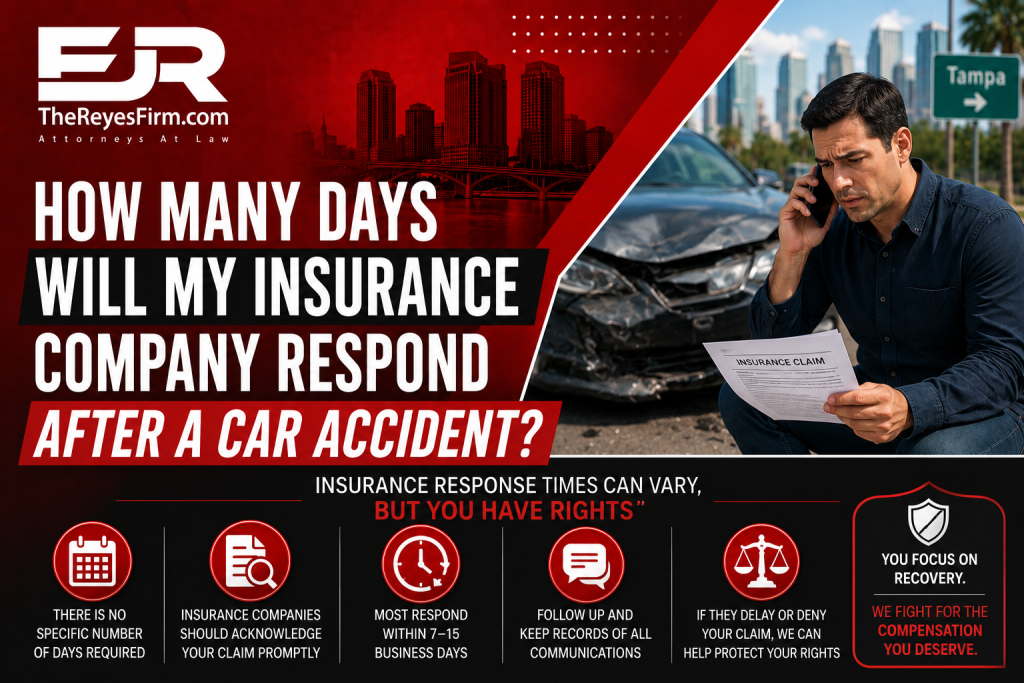
It depends on the type of claim, but the short answer is that your own no-fault insurer must pay or deny a Personal Injury Protection (PIP) claim within 30 days, while a claim against the other driver’s insurer has no fixed deadline at all. Florida law also expects any insurer to acknowledge a new claim promptly, generally within about 14 days, even though the full investigation takes longer than that.
That gap between a quick acknowledgment and a slow resolution is where most of the frustration lives. An insurer can confirm it received your claim, then take weeks or months to actually decide what it will pay. Knowing which deadline applies to your situation tells you whether the delay you’re experiencing is normal or a warning sign.
How long does your own PIP insurer have to pay or deny your claim?
Your own PIP insurer has 30 days to pay or deny your claim after it receives written notice of the loss. This deadline comes from Florida Statute § 627.736(4)(b), and Florida applies a “mailbox rule,” meaning the insurer complies as long as the payment is postmarked by the 30th day.
There is a catch that falls on you first. To qualify for PIP benefits at all, you must seek medical treatment within 14 days of the crash. Miss that window and your insurer can deny PIP coverage entirely, no matter how serious your injuries turn out to be. If you submit your bills in pieces, the insurer gets a fresh 30 days to pay each portion as it comes in, and if it denies part of your claim over a clerical mistake, you generally have 15 days to fix and resubmit it.
💡 Did You Know? Under Florida’s no-fault law, your PIP insurer must pay or deny your claim within 30 days of receiving written notice, and the payment only needs to be postmarked by day 30 to count. Florida also requires you to seek medical treatment within 14 days of the crash to keep your PIP benefits at all. Source: Fla. Stat. § 627.736, leg.state.fl.us.
What about a claim against the other driver’s insurance company?
A claim against the at-fault driver’s insurer works very differently, because there is no statutory deadline forcing a third-party liability insurer to respond by a set date. Instead, the insurer only has to investigate and decide within a “reasonable” period, which gives it far more room to take its time than your own PIP carrier has.
This is the kind of claim that can stretch on for months, especially when injuries are serious, fault is disputed, or a commercial policy is involved, such as in a truck or commercial vehicle crash. The lack of a hard deadline does not mean the insurer can stall forever, and it does not stop your own clock from running. Whatever the other side does, you still have a firm deadline to protect your right to sue.
⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer.
Watch: What to do when an insurance company delays your car accident claim
This short video explains the warning signs that an insurer is stalling and the first moves that keep your claim on track.
If your claim is stuck, The Reyes Firm offers free consultations and can tell you where you stand at no cost.
Why do insurance companies delay responding after a car accident?
Insurers delay because slowing a claim down often costs them less. The longer a claim drags, the more likely an injured person grows anxious about mounting bills and accepts a quick, low settlement just to make the waiting stop.
Common tactics include requesting the same documents more than once, questioning whether your injuries really came from the crash, disputing who was at fault, and simply going quiet for long stretches. Florida follows a comparative fault rule, so one of the most common moves is trying to pin part of the blame on you in order to shrink what the insurer owes.
🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible for your own harm. An experienced Tampa car accident lawyer works to protect the facts, challenge unfair blame, and keep your percentage of fault as low as the evidence allows.
What can you do if your insurance company is not responding?
You have more leverage than the silence suggests. Start by putting everything in writing and keeping a dated record of every call, the name of every adjuster, and every document you send, so there is a clear trail if the delay becomes unreasonable.
If your own PIP insurer ignores a valid claim, Florida law lets you send a written demand for payment, after which the insurer has another 30 days to pay before you can take it to court. Once you do reach a settlement, Florida Statute § 627.4265 requires the insurer to pay it within 20 days, or it owes you interest. When an insurer denies or delays a claim without a reasonable basis, Florida’s bad faith law under Florida Statute § 624.155 may give you additional remedies, including interest and penalties on top of what you were owed. A lawyer can send these demands, document the insurer’s conduct, and apply real pressure where a phone call from you would be ignored.
What are the 7 steps to take when dealing with insurance after a Tampa car accident?
These seven steps protect both your benefits and your leverage with the insurance company. The order matters.
- Report the crash to your insurer promptly. Most policies require timely notice, so tell your own insurer what happened, but stick to the basic facts and avoid speculating about fault or the extent of your injuries.
- Get medical treatment within 14 days. This is the deadline that protects your PIP benefits. Even if you feel fine, see a doctor quickly, because adrenaline hides injuries and a treatment gap gives the insurer a reason to deny coverage.
- Put everything in writing. Keep a log of every call, adjuster name, and date, and follow up important conversations with a short email. A written trail is your best protection if the insurer later stalls.
- Do not give a recorded statement or accept the first offer. The other driver’s adjuster may call quickly and sound helpful. You are not required to give a recorded statement, and the first offer is almost always lower than your claim is worth.
- Track the deadlines. Note when you submitted your PIP claim so you know when the 30-day clock runs out, and remember that an agreed settlement must be paid within 20 days.
- Send a written demand if they stall. If a valid claim goes unanswered, a formal written demand starts a new 30-day clock on your PIP insurer and creates a record of the delay.
- Call The Reyes Firm before signing a release. Once you sign a release, you give up the right to pursue anything more. A Tampa car accident lawyer will review any offer first. Call 833-4 BAD DAY for a free consultation.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm handles your car accident insurance claim
When an insurance company goes quiet while your bills pile up, it is easy to feel like you have no move to make. You do. The insurer already has a team working to pay you as little as possible. We make sure you have a team working for you.
When we take on a Tampa car accident insurance claim, we typically:
- Take over all communication with the insurers, so the calls, recorded-statement requests, and pressure tactics come to us instead of to you while you focus on healing
- Document your claim completely, gathering medical records, bills, wage loss, and crash evidence so the insurer has no excuse to delay over missing information
- Track and enforce every deadline, holding your PIP insurer to its 30-day obligation and pursuing interest and penalties when the law allows
- Push back on unfair blame, challenging attempts to shift fault onto you that are designed only to reduce what you are paid
- Calculate the full value of your claim, including past and future medical care, lost wages, property damage, and the real impact the crash has had on your life
- Prepare every claim as if it will go to trial, which is often what finally moves a stalling insurer to make a fair offer
No lawyer can promise a specific result. What we can promise is that we treat a delayed or denied claim as a problem to be solved aggressively, not a file to be left waiting. We explain every step in plain language and keep you informed throughout. We help drivers in Tampa and across Hillsborough County on a contingency fee basis, which means you pay nothing unless we recover compensation for you.
Frequently asked questions about insurance response times after a Tampa car accident
How many days does an insurance company have to respond to a claim in Florida?
An insurer is expected to acknowledge a new claim promptly, generally within about 14 days. Your own PIP insurer must then pay or deny the claim within 30 days under Fla. Stat. § 627.736(4)(b). A claim against the at-fault driver’s insurer has no fixed statutory deadline.
How long does my own insurance have to pay a PIP claim?
Thirty days from the date it receives written notice of your claim. Florida applies a mailbox rule, so the insurer meets the deadline as long as the payment is postmarked by the 30th day, even if it arrives a few days later.
Is there a deadline for the at-fault driver’s insurance to respond?
No. Third-party liability claims are not first-party PIP claims, so the strict 30-day rule does not apply. The insurer only has to respond within a reasonable time, which is why these claims can take months, particularly when injuries are serious or fault is contested.
What happens if the insurance company agrees to a settlement but does not pay?
Once a settlement is in writing, Fla. Stat. § 627.4265 requires the insurer to pay it within 20 days. If it misses that deadline without a valid reason, it owes you interest on the amount it agreed to pay.
What can I do if my insurance company is ignoring me?
Document every contact in writing, then send a formal written demand, which restarts a 30-day clock on a PIP insurer. If the delay is unreasonable, Florida’s bad faith law under Fla. Stat. § 624.155 may allow extra remedies. An attorney can send these demands and apply pressure that a single phone call cannot.
Can an insurance delay push me past the deadline to sue?
It should not, but you have to watch the clock yourself. You have two years from the crash to file a personal injury lawsuit under Fla. Stat. § 95.11(3)(a). If an insurer stalls as that date approaches, filing suit is often the only way to protect your claim.
Should I accept the first settlement offer from the insurance company?
Usually not. First offers are typically far below what a claim is worth and may come before the full extent of your injuries is known. It is worth having any offer reviewed before you sign, because signing a release ends your right to seek more.
How much does a Tampa car accident lawyer cost?
The Reyes Firm works on a contingency fee basis, which means you pay nothing up front and nothing at all unless the firm recovers compensation for you. The initial consultation is free, so there is no risk in finding out where your claim stands.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. His practice focuses on serious injury and wrongful death cases, including car accident claims where insurance companies delay, underpay, or deny what injured people are owed. Edward Reyes, Esq. represents injured Floridians in Tampa and throughout Hillsborough County on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day — a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault — The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.