You were just going about your day. Then another driver hit you at an intersection. Now your car is damaged, your neck hurts, and the other driver’s insurance company is on the phone offering to “just work this out” with a quick check. Here’s what you need to know before you accept a dollar of it.
TL;DR — QUICK SUMMARY
- Can you settle directly with the other driver’s insurance company? Technically yes. Should you do it alone? Almost never.
- The adjuster offering you money works for the insurer, and their job is to close your claim for as little as possible.
- Early offers rarely account for future medical care, lost wages, or injuries that surface days after the crash.
- Once you sign a release, you usually give up the right to ask for more, even if your condition gets worse. Under Florida Statute 95.11(3)(a), you generally have two years to file a lawsuit, but a signed release can end your claim long before that.
- A free consultation costs you nothing and tells you what your case is really worth before you decide.
The Reyes Firm
Did an Insurer Offer to “Work It Out” After a Tampa Crash?
Find out what your case is really worth before you sign. Had a bad day?
Can you work it out with the insurance company yourself?
Technically, yes, and that’s exactly why so many people get shortchanged. Nothing in Florida law stops you from negotiating directly with the other driver’s insurer and accepting a settlement on your own. The myth isn’t whether you can. The myth is that doing it alone gets you a fair result.
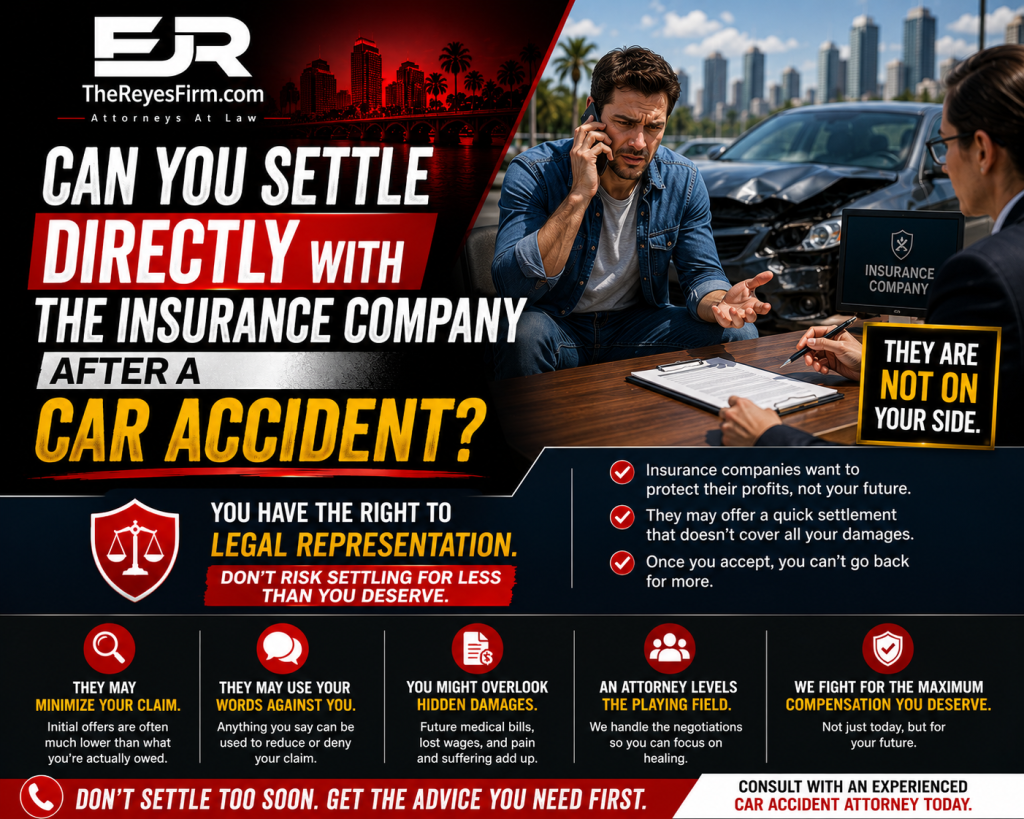
The person calling you is an adjuster, and the adjuster works for the insurance company. Their job is to close your claim for as little money as possible, because every dollar they save is a dollar that stays with their employer. They are friendly, they are professional, and they are negotiating against you the moment they pick up the phone.
So the honest answer from The Reyes Firm, a Tampa personal injury law firm, is this: you can work it out yourself, but you usually shouldn’t, and the reason becomes obvious once you see how these offers are built.
⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your crash to file a personal injury lawsuit. But signing a settlement release ends your claim immediately, no matter how much time is left on that clock. Never sign before you know what your case is worth.
Why does settling directly with the other driver’s insurer backfire?
Because the first offer is almost always built around what’s visible on day one, not what your injury actually costs you over time. The dented bumper is easy to price. The herniated disc that flares up three weeks later is not, and by then you may have already cashed the check.
Attorney Edward Reyes learned this firsthand. After his first car accident as a young man, someone handed him $400 and it seemed like enough. It wasn’t close. The repairs to his car ran over a thousand dollars, and the injuries he felt afterward were worth far more than that. He took the fast money before he understood the real damage, and that lesson is part of why he practices personal injury law today.
That story plays out constantly. People try to handle it themselves, accept an early number to make the problem go away, and only later discover the offer didn’t cover their medical bills, their time off work, or the lasting effects of the crash. Once the release is signed, that money is final.
💡 Did You Know? Florida is a no-fault auto insurance state. Under Florida Statute § 627.736, your own Personal Injury Protection (PIP) coverage pays the first portion of your medical bills regardless of who caused the crash, up to a $10,000 minimum, but only if you seek treatment within 14 days. Settling with the other insurer doesn’t change those PIP deadlines. Source: Fla. Stat. § 627.736.
Watch: Can You Work It Out With the Insurance Company?
In this short video, attorney Edward Reyes busts the myth that you can simply “work it out” with the other side’s insurer, and shares the personal story that shaped how he handles these cases.
If you have a settlement offer in front of you and aren’t sure what to do, The Reyes Firm offers free consultations, so you can call 833-4 BAD DAY before you respond.
What is a fair settlement actually worth after a Tampa car accident?
A fair settlement reflects everything the crash will cost you, not just the bills already on your kitchen table. A complete claim accounts for several categories most people overlook when they negotiate alone:
- Future medical care, including follow-up visits, physical therapy, imaging, and treatment for injuries that worsen over time
- Lost wages and lost earning capacity, covering the work you’ve already missed and any long-term limits on what you can do
- The full diagnosis, since soft-tissue injuries, concussions, and back injuries often don’t show their true severity for days or weeks
- Property damage done right, repaired or replaced at real cost, not a rounded-down estimate
- Pain and the disruption to your life, which an adjuster has every incentive to value at zero
In a serious or catastrophic crash, the gap between the first offer and the real value of the claim can be enormous. That gap is the insurer’s profit, and it comes directly out of your recovery.
🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found more than 50% responsible for the crash. Adjusters often try to pin extra blame on you to cut their payout, and an experienced Tampa car accident lawyer works to keep your percentage of fault as low as the evidence allows.
When is it actually okay to handle a claim on your own?
To be fair, not every fender-bender needs a lawyer. If the contact was truly minor, there are genuinely no injuries, no one needed medical care, and the only issue is a small, clearly documented property-damage repair, handling it yourself may be reasonable.
The danger is that you often can’t tell the difference at the start. Adrenaline hides pain, and injuries to your neck, back, and head frequently surface a day or two later. By the time symptoms appear, an unrepresented person has sometimes already signed away the claim. When there’s any injury, any dispute about fault, or any pressure to settle fast, that’s the signal to talk to an attorney first. The consultation is free, so there’s no downside to checking.
What are the 6 steps before you talk settlement with an insurer?
These six steps protect your health and your claim. The order matters.
- Get medical care immediately. See a doctor within 14 days to preserve your PIP benefits and to document that your injuries came from the crash. A gap in treatment is the first thing an adjuster uses to argue you weren’t really hurt.
- Don’t accept or cash an early check. A fast offer is designed to close your claim before you know the full extent of your injuries. Cashing it can waive your right to anything more.
- Don’t sign a release or recorded statement. A release ends your claim, and a recorded statement gives the adjuster words to use against you. You can decline both until you’ve spoken with a lawyer.
- Document everything. Keep photos, the police report, medical bills, repair estimates, and proof of missed work. Write down how the injury affects your daily life.
- Get the claim valued before you negotiate. You can’t bargain fairly when you don’t know your number and the adjuster knows theirs.
- Call The Reyes Firm first. A Tampa car accident attorney will review any offer, value your case fully, and deal with the adjuster for you. Call 833-4 BAD DAY for a free consultation.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm handles your insurance settlement
When the other side’s insurer wants to “work it out,” they already have professionals protecting their money. We make sure you have someone protecting yours.
When we take on a car accident claim, we typically:
- Take over all communication with the adjuster, so you’re shielded from the friendly calls, recorded-statement requests, and fast offers designed to close your claim cheap
- Investigate and document the crash, gathering the police report, medical records, photos, and witness accounts to establish what happened and who is responsible
- Value your case in full, including future medical care, lost wages, reduced earning capacity, property damage, and the real impact on your life, not just the bills already incurred
- Push back on unfair blame, challenging any attempt to raise your share of fault under Florida’s comparative fault rules
- Negotiate from strength, preparing the case as if it will go to trial, which is often what moves an insurer off its first lowball number
No lawyer can promise an outcome. What we can promise is that we won’t let a $400 handshake stand in for what your case is actually worth. We explain every decision in plain language, and because we work on a contingency fee basis, you pay nothing unless we recover compensation for you.
Frequently asked questions about settling with the insurance company in Tampa
Can I legally settle with the other driver’s insurance company myself?
Yes, nothing requires you to hire a lawyer to settle a claim. The problem is that the adjuster negotiates these claims for a living and you don’t, so people who go it alone are frequently shortchanged, especially when injuries surface after the offer is made.
Why is the insurance company offering me money so fast?
A fast offer is a tactic. The sooner you accept, the less likely the insurer is to pay for injuries that haven’t fully revealed themselves yet. Speed benefits them, not you, so treat an early check as a reason to slow down, not to sign.
What happens if I already cashed the insurance check?
If you signed a release, you may have given up the right to pursue more, even if your injuries turn out to be serious. It’s not always the end of the road, though, so before you assume the worst, have an attorney review exactly what you signed.
Should I give the adjuster a recorded statement?
Not before talking to a lawyer. A recorded statement is one of the main tools adjusters use to gather words that reduce or deny claims. You can politely decline and direct them to your attorney.
How long do I have to settle or file a claim in Florida?
Under Fla. Stat. § 95.11(3)(a), you generally have two years from the date of the accident to file a personal injury lawsuit. A signed settlement, however, ends your claim right away, so the deadline that matters most is often the one the adjuster is pushing you toward.
Will hiring a lawyer actually get me more than settling alone?
No attorney can promise a specific result, but a lawyer values your full claim, handles the negotiation, and prepares the case as if it will go to trial, which often moves an insurer off its first offer. Because the firm works on contingency, you can weigh that option at no upfront cost.
Does The Reyes Firm handle car accident claims throughout Tampa Bay?
Yes. The Reyes Firm represents injured drivers and passengers across Hillsborough County and the greater Tampa Bay area, and consultations are always free.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. His practice focuses on serious injury and wrongful death cases arising from commercial vehicle crashes, including delivery truck accidents involving FedEx, UPS, Amazon, and other carriers. Edward Reyes, Esq. represents injured Floridians in Tampa and throughout Hillsborough County on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day — a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault — The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.