January 11, 2021

Legal response guide for lawsuits
Legal

What to Do If Someone Files a Lawsuit Against You?

You just got handed a thick envelope by a process server, or you opened your mail to find a Summons and Complaint with your name on it. Someone has filed a lawsuit against you in Florida, and the clock is already running. Every day you wait shrinks your options. TL;DR — QUICK SUMMARY If you’ve been served with a civil lawsuit in Florida, you generally have 20 days to file a written response with the court — miss it and the other side can ask for a default judgment against you. If you’ve been served only with a request for records or discovery (not a full complaint), you typically have 30 days to respond under Florida’s Rules of Civil Procedure. Do not ignore the papers, do not throw them away, and do not call the person suing you — anything you say can be used against you. Florida’s personal injury statute of limitations gives the other side a deadline too: under Florida Statute § 95.11(3)(a), most negligence suits filed for incidents on or after March 24, 2023, must be brought within two years. If the lawsuit involves a car crash, slip and fall, or other injury where you were also hurt, The Reyes Firm can review whether you have a counterclaim or independent personal injury claim of your own. The Reyes Firm Served with a Lawsuit in Tampa? If you were also injured in the same incident, you may have a claim of your own. Had a bad day? Contact Us Now 20 Days To answer a Florida civil complaint Fla. R. Civ. P. 1.140(a) 30 Days To respond to discovery requests Fla. R. Civ. P. 1.340, 1.350 2 Years Florida injury statute of limitations Fla. Stat. § 95.11(3)(a) 50% Comparative fault recovery bar Fla. Stat. § 768.81 What does it mean when someone files a lawsuit against you in Florida? When someone files a suit against you, it means they have filed a formal Complaint with a Florida court asking a judge to find you legally responsible for something and to order you to pay money or take some other action. You become the “Defendant.” The person suing you is the “Plaintiff.” Once that Complaint is filed and you are properly served, you are officially in litigation — whether you respond or not. Service of process is the legal step that puts you on notice. In Florida, that usually means a sheriff’s deputy or a private process server physically delivers the Summons and Complaint to you, leaves it with someone over 15 at your usual place of residence, or in some cases serves a designated registered agent. Once you’re served, the deadline clock starts running, and the court considers you formally on notice of the case. ⚠️ Deadline Warning: Under Florida Rule of Civil Procedure 1.140(a), you generally have only 20 days from the date of service to file a written response to a civil complaint. If you miss that deadline, the plaintiff can ask the court for a default judgment — meaning they can win the case and a money judgment against you without you ever being heard. Do not wait to call a lawyer. How long do you have to respond after being served with a Florida lawsuit? You generally have 20 days from the date of service to file a written response with the court if you’ve been served with a full Summons and Complaint in a Florida civil case. That 20-day window is set by Florida Rule of Civil Procedure 1.140(a), and the day you are served does not count — the clock starts the next day. Weekends and holidays are included in the 20 days, except that if the 20th day falls on a weekend or court holiday, you get until the next business day. If you were served with something narrower, like a request for production of documents, interrogatories, or a subpoena for records, the deadline is usually 30 days to respond under Florida’s discovery rules. Pre-suit demand letters and insurance claim notices have their own timelines too. Different documents trigger different clocks, and the wrong assumption costs people their cases every week in Florida. Here are the deadlines that most commonly apply: Summons and Complaint: 20 days to file an Answer or motion under Fla. R. Civ. P. 1.140(a) Discovery requests (interrogatories, requests for production): 30 days to respond under Fla. R. Civ. P. 1.340 and 1.350 Small claims (under $8,000): The summons sets a pre-trial conference date, and you must appear in person or through counsel Eviction actions: Just 5 business days to file a written response under Fla. Stat. § 83.60 Service by publication or out-of-state defendant: Often longer than 20 days — read the summons carefully What are the 7 steps to take if someone files a suit against you in Tampa? These 7 steps protect your legal rights and preserve your ability to fight back. The order matters. Read every page of what you were served. The Summons tells you how long you have to respond, where to file, and the case number. The Complaint lists the specific claims and the dollar amount being demanded. Note the date and exact time you were served — this controls your 20-day deadline. Do not contact the person suing you. Anything you say can become evidence. Do not call them, do not email, do not message them on social media, and do not post about the case anywhere online. Even a casual apology can be twisted into an admission of liability. Notify your insurance company in writing immediately. If the lawsuit involves a car crash, a slip-and-fall on your property, a dog bite, or anything covered by liability insurance, your policy likely requires prompt notice. Insurers can deny coverage if you sit on the papers. Your insurer may also be required to provide you with a defense attorney at no out-of-pocket cost. Preserve all related evidence. Save texts, emails, photos, dashcam footage, repair estimates, medical records, and anything else that

Deleted posts and the truth found
Car accident, Legal, Settlement

Are Deleted Social Media Posts Retrievable in Injury Cases?

You posted something after your car accident, a photo, a status, a quick “I’m fine” to reassure family, and now you’re wondering if you should delete it. Stop before you do. In a Florida injury case, deleting the wrong post can hurt you far more than leaving it up. Here’s what’s really retrievable, and what to do instead. TL;DR — QUICK SUMMARY Deleted social media content is often not truly gone. It can survive in data archives, screenshots, tagged posts, and platform records. Relevant social media is discoverable in a Florida injury case, and privacy settings do not shield it (Nucci v. Target Corp.). Deleting posts after you have a claim can be spoliation of evidence, which carries serious penalties, sometimes worse than the post itself. Insurance companies actively monitor your accounts, and your friends’ and family’s, for anything that contradicts your injuries. The safe move is simple: don’t delete anything, stop posting, and talk to your lawyer before touching your accounts. The Reyes Firm Worried a Post Could Sink Your Claim? Get your case reviewed before you touch your social media. Had a bad day? Contact Us Now Nucci 2015 Set the social media rule Fla. 4th DCA Discoverable Relevant posts, even if private Fla. R. Civ. P. 1.280 Spoliation Risk of deleting after a claim Sanctions / adverse inference $0 Upfront cost on contingency Pay nothing unless you recover Are deleted social media posts really retrievable? Often, yes. Hitting delete removes a post from your timeline, but it doesn’t guarantee the content is gone. Platforms keep data behind the scenes, and the “download your data” archive feature can surface content you thought you erased. Beyond that, anyone who saw the post, including an insurance investigator, may have already screenshotted it, and friends or family may have shared or been tagged in the same content. There’s also the legal route. In a lawsuit, the other side can subpoena the platform or compel you to produce your account data, including deleted material. So the honest answer is that deleting is unreliable as a way to hide something, and as you’ll see, it’s also one of the most dangerous things you can do. Can the other side see my social media if I file an injury claim? Yes, to the extent it’s relevant to your case. When you file a personal injury claim, you put your physical and mental condition at issue, and that opens the door to discovery of social media that bears on it. Florida’s leading case, Nucci v. Target Corp., made this clear: photographs and posts that are relevant to an injury claim are discoverable, and your privacy settings do not protect them. The court treated social media as a kind of free surveillance, valuable to anyone defending a claim. That doesn’t mean the other side gets unlimited access to everything. Discovery still has to be relevant and reasonably tailored. But the takeaway is blunt: marking your account “private” is not a shield. If a post is relevant to your injuries or activities, a court can order you to hand it over. ⚠️ Deadline Warning: The moment you have a potential claim, you have a duty to preserve evidence, including social media. You also generally have two years to file an injury lawsuit under Florida Statute § 95.11(3)(a). Don’t delete anything, and don’t wait to talk to a lawyer about both. Watch: How social media can affect your injury claim This short video explains how posts, photos, and even deleted content can shape what your case is worth. Not sure whether something you posted is a problem? The Reyes Firm offers a free case review. Why is deleting posts the worst thing you can do? Because deleting can turn a minor problem into a major one. Once you reasonably anticipate a claim or a lawsuit, the law expects you to preserve relevant evidence. Destroying it, including scrubbing your social media, is called spoliation of evidence. Courts take it seriously, and the penalties can be severe. The most common consequence is an adverse-inference instruction, where the judge tells the jury they may assume the deleted content was unfavorable to you. In other words, you don’t just lose the post, you hand the other side a weapon, and you can also face monetary sanctions. A harmless photo you deleted out of caution can end up looking like a guilty cover-up. That’s why the rule is so important: don’t delete, preserve, and let your lawyer guide what happens next. 💡 Did You Know? Courts have imposed heavy sanctions on people, and even their attorneys, for deleting social media content after litigation became foreseeable. The danger isn’t only that the content resurfaces, it’s that the act of deleting it can be used to argue you were hiding something. Preserving everything and posting nothing new is almost always the safer path. Source: Nucci v. Target Corp., 162 So. 3d 146 (Fla. 4th DCA 2015). How do insurance companies actually use your social media? Aggressively, and from the moment you file. Insurers and their investigators monitor claimants’ accounts looking for anything that contradicts the injuries you’ve described. A photo of you smiling at a barbecue, a check-in at the gym, a vacation post, or a video of you lifting your child can all be twisted into an argument that your pain and limitations are exaggerated. It doesn’t stop at your own profile. They also look at your friends’ and family’s accounts, public posts, and photos you’re tagged in. A single out-of-context image can do real damage, even when the truth is that you pushed through pain for one moment and paid for it for days. Just as your medical records can be used against you, your social media becomes part of the evidence, whether you intended it to or not. 🛡️ Your Rights Under Florida Law: While relevant posts are discoverable, the other side does not automatically get access to your entire account. Under Florida’s rules of civil procedure, discovery must be relevant

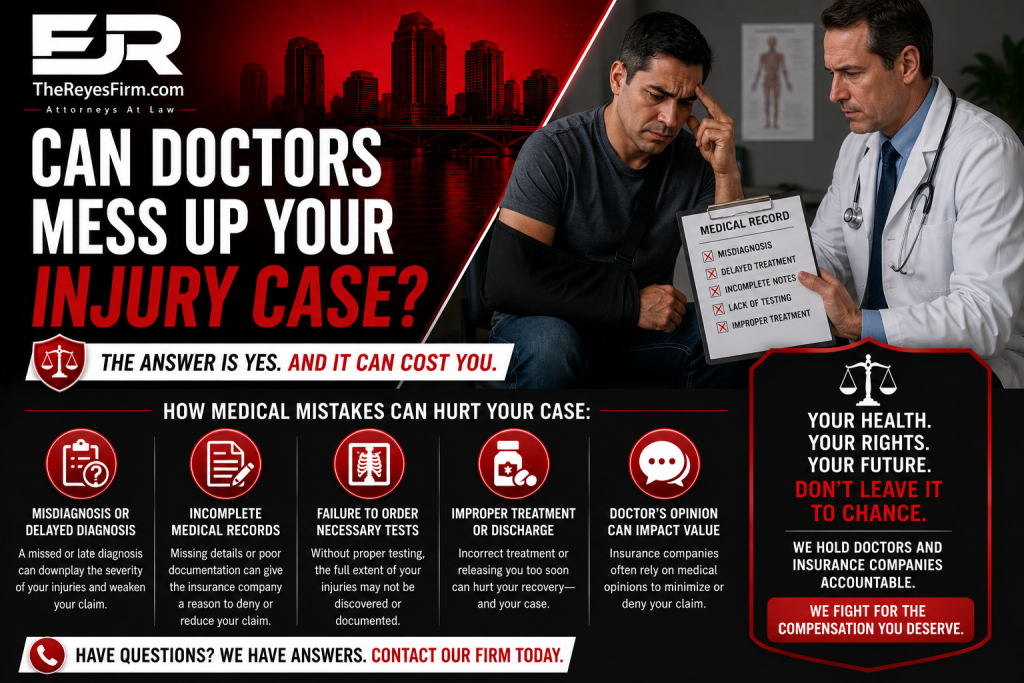
Medical mistakes hurt your case
Health, Legal, Personal Injury

Can Doctors Mess Up Your Injury Case?

You did everything right after your car accident. You saw a doctor, you followed up, you’re trying to heal. So it comes as a shock to learn that the wrong doctor, or the right doctor with sloppy notes, can quietly sink your injury claim. Here’s how it happens, and how to protect yourself before the insurance company turns your own medical records against you. TL;DR — QUICK SUMMARY Your medical records are discoverable evidence. The insurance company reads them closely and uses anything unhelpful against you. Poor or incomplete documentation, like a note that you “feel fine,” can undercut your claim even when you’re seriously hurt. In Florida, you must seek care within 14 days of a crash to keep your PIP benefits under Fla. Stat. § 627.736. The type of provider you see matters, both for your recovery and for how credibly your injuries are documented. Gaps in treatment, downplaying symptoms, and ignoring your doctor’s plan are some of the fastest ways to weaken a strong case. The Reyes Firm Worried Your Medical Records Could Hurt Your Claim? Get your case reviewed before the insurance company twists your treatment against you. Had a bad day? Contact Us Now 14 Days Window to seek care for PIP Fla. Stat. § 627.736(1)(a) $10,000 PIP benefits with an EMC Fla. Stat. § 627.736 2 Years Deadline to file an injury claim Fla. Stat. § 95.11(3)(a) $0 Upfront cost on contingency Pay nothing unless you recover Can your own doctor really hurt your injury case? Yes, and it happens more often than people expect. Not because the doctor is bad at medicine, but because a personal injury claim runs on documentation. The moment a provider writes something in your chart, it becomes part of the medical record, and that record is discoverable. The insurance company gets to read it, and it will seize on anything that helps the defense. Think about how that plays out. A doctor focused on treating you, not on your legal case, jots down “patient reports feeling better” after one good day. To you, it was a single decent afternoon. To an insurance adjuster, it’s a quote to argue you weren’t really hurt. The record outlives the moment, and the words get used against you long after you’ve forgotten you said them. ⚠️ Deadline Warning: After a Florida crash, you must seek medical care within 14 days to keep your PIP benefits under Fla. Stat. § 627.736, and you generally have two years to file an injury lawsuit under Florida Statute § 95.11(3)(a). Miss the 14-day window and you can lose coverage no matter how hurt you are. Don’t wait. How do your medical records become evidence against you? Once you make a claim, your accident-related medical records are fair game. The insurer’s team combs through them line by line looking for three things: anything suggesting your injuries aren’t serious, anything suggesting they weren’t caused by the accident, and any gap that lets them argue you healed or were never really hurt. That’s why what your doctor writes matters as much as what they treat. If the records don’t clearly connect your injuries to the crash, the insurer argues causation is missing. If they don’t capture the full picture of your pain and limitations, the insurer argues your injuries are minor. The medical chart isn’t just a treatment tool. In a claim, it’s the evidence, and weak documentation is a gift to the other side. Watch: How doctors and documentation affect your injury case This short video explains how the right and wrong medical choices can shape what your case is worth. Want a clear read on where your case stands? The Reyes Firm offers a free case review. Why does the type of doctor you see matter? Because no single doctor is a fix-all, and the right specialist both treats you better and documents you better. A neurologist handles nerve issues. An orthopedist handles bones, joints, and muscles. A chiropractor focuses on the spine. Seeing a provider who actually matches your injury means clearer diagnoses, more credible records, and treatment that holds up under scrutiny. In Florida, the provider also matters for your benefits. To keep your PIP coverage, your initial care within the 14-day window has to come from a qualifying provider, such as a physician, an osteopathic physician, a dentist, or a hospital. And whether you receive the full benefit or a fraction of it can hinge on a single determination, which we’ll cover next. Serious harm like spinal or nerve injuries especially needs the right specialist on record early. 💡 Did You Know? Under Florida’s PIP law, you get the full $10,000 in benefits only if a qualifying provider determines you have an “emergency medical condition” (EMC). If your initial provider decides your injuries don’t qualify as an EMC, your medical benefits are capped at just $2,500. That single determination can mean a $7,500 difference. Source: Fla. Stat. §§ 627.736, 627.732. What medical mistakes hurt your case the most? A few patterns do the most damage, and the good news is that all of them are avoidable once you know what to watch for: Waiting too long to get care. Delay lets the insurer argue you weren’t badly hurt, and in Florida it can cost your PIP benefits entirely. Gaps in treatment. Missed or spaced-out appointments create holes the defense fills with “you must have recovered.” Downplaying your symptoms. Telling a doctor you’re “okay” to be polite gets written down and quoted back to you. Not following the treatment plan. Skipping prescribed therapy or care lets the insurer argue you made your own injuries worse. Seeing the wrong provider. A mismatch between your injury and your doctor weakens both your treatment and your records. None of these mean a doctor did anything wrong medically. They’re about how the claim side reads the paper trail, and small habits at the doctor’s office can have an outsized effect on your case. What if you had a

Scroll to Top