March 16, 2026

company vehicle accident claim
Blog, Business

Company Vehicle Accident Claim: How to File, What to Expect, and How to Protect Yourself

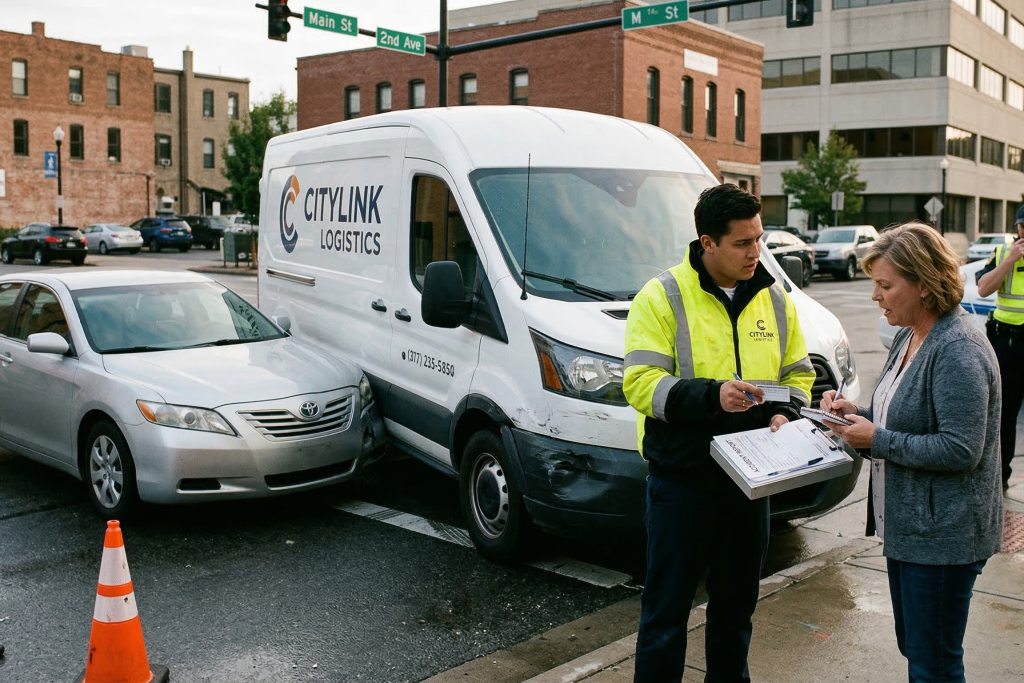
A crash involving a company vehicle does more than dent metal and shatter glass. For construction professionals, property owners, architects, engineers, developers, and even government agencies, one accident can delay projects, trigger insurance investigations, and create serious financial exposure. A single collision on the way to a job site can affect contracts, inspection schedules, and even future bids. Florida’s roads are filled with work trucks, fleet SUVs, delivery vans, municipal vehicles, and contractor pickups. When one of these vehicles causes an accident—or is involved in one—the legal process becomes more complex than a typical car crash. Filing a company vehicle accident claim involves insurance policies, employer liability rules, employment status questions, and sometimes government immunity laws. At The Reyes Firm, a Florida personal injury and accident law firm focused on representing injured plaintiffs, the mission is simple: protect people, not corporations. Below is a comprehensive guide explaining how a company vehicle accident claim works, what to expect, and how professionals in construction and development-related industries can protect themselves. What Is a Company Vehicle Accident Claim? A company vehicle accident claim is a legal claim made after a crash involving a vehicle owned, leased, rented, or operated by a business or government agency while being used for work purposes. This may include: Construction company trucks transporting materials Engineering firm vehicles used for site inspections Property management fleet vehicles Real estate development company cars Government agency vehicles conducting field operations Utility or maintenance vehicles The key legal concept behind these claims is called vicarious liability. Under Florida law, employers can be held responsible for the negligent actions of employees if those actions occur within the scope of employment. In simple terms: If the driver was doing their job when the crash happened, the employer may also be legally responsible. For example: A site supervisor driving between projects runs a red light. An engineering consultant rear-ends another vehicle while traveling to a structural inspection. A municipal inspector causes a collision while on duty. In each of these situations, an injured person may file a company vehicle accident claim against both the driver and the employer. For construction professionals and developers, this concept is critical. It means liability may extend beyond the individual driver and reach the company’s insurance coverage. Why These Claims Are More Complex Than Regular Car Accidents A company vehicle accident claim is rarely simple. Compared to a standard private vehicle crash, these cases involve additional legal layers. 1. Higher Insurance Coverage — and Stronger Defense Most businesses carry commercial auto insurance policies with higher limits than personal policies. This can be beneficial because more coverage may be available for serious injuries. However, higher coverage also means: More aggressive insurance adjusters Detailed investigations Corporate defense attorneys involved early Companies treat these cases as financial risks, not personal matters. 2. Employment Scope Disputes One of the first questions insurers ask is: “Was the driver acting within the scope of employment?” If a construction manager stopped for personal errands, the company might argue the employee was not “on duty.” That argument could affect liability. 3. Fleet Maintenance Issues For construction and engineering firms operating fleet vehicles, maintenance records can become central evidence. Poor brake maintenance, tire neglect, or overloaded trucks can increase corporate liability. 4. Government Vehicles Add Special Rules If the accident involves a city, county, or state vehicle, Florida’s sovereign immunity laws apply. Claims against government agencies must follow special notice procedures and shorter deadlines. This is particularly relevant for contractors working alongside municipal agencies or developers involved in public-private partnerships. Who Can File a Company Vehicle Accident Claim? Several parties may have the right to file a company vehicle accident claim in Florida: Drivers hit by a company vehicle Passengers Pedestrians Cyclists Workers injured while riding in a company vehicle Employees injured while driving for work For construction professionals and engineering consultants, accidents often happen while traveling between job sites. In those situations, multiple legal paths may exist: Workers’ Compensation If an employee is injured while driving a company vehicle during work hours, workers’ compensation may cover medical bills and partial wage replacement. Third-Party Liability Claim If another company’s vehicle caused the accident, the injured worker may pursue a separate third-party personal injury claim. This dual-claim situation is common in large-scale construction projects involving multiple contractors. Understanding these overlapping systems is critical for protecting financial recovery. How to File a Company Vehicle Accident Claim in Florida Filing a company vehicle accident claim involves strategic steps. Step 1: Get Immediate Medical Care Even if injuries seem minor, medical evaluation is essential. Florida’s no-fault law requires treatment within 14 days to access Personal Injury Protection (PIP) benefits. Delayed symptoms are common with: Concussions Internal bleeding Spinal injuries Soft tissue damage Medical documentation builds the foundation of any claim. Step 2: Report the Accident Properly Call law enforcement and obtain a crash report. Notify your employer if you were on duty. Document the company name on the vehicle. For professionals used to field documentation, treat this like recording site conditions. Accuracy matters. Step 3: Preserve Evidence Helpful documentation includes: Photos of damage and road conditions Witness statements Company logos and vehicle numbers Driver’s employer details Delivery schedules or job site logs In fleet vehicle cases, maintenance logs may later become important evidence. Step 4: Notify Insurance Carefully Insurance companies often contact injured parties quickly. Be cautious about giving recorded statements without legal guidance. Commercial insurers are trained to limit payouts. Step 5: Consult a Personal Injury Attorney Early Company vehicle accident claims often involve: Multiple insurance policies Employment disputes Large corporate defendants Technical accident reconstruction Early legal involvement prevents costly missteps. What to Expect During the Claim Process Understanding the timeline helps professionals manage expectations. Investigation Phase A thorough investigation may include: Reviewing employment records Determining driver status at time of crash Analyzing vehicle maintenance logs Examining GPS or fleet tracking data Reviewing company safety training policies In construction-related accidents, weight loads and equipment securement may be reviewed. Insurance Negotiation Phase Insurance
fleet insurance claim
Blog, Business, Car accident

Fleet Insurance Claim Checklist: Documents, Photos, and Common Mistakes

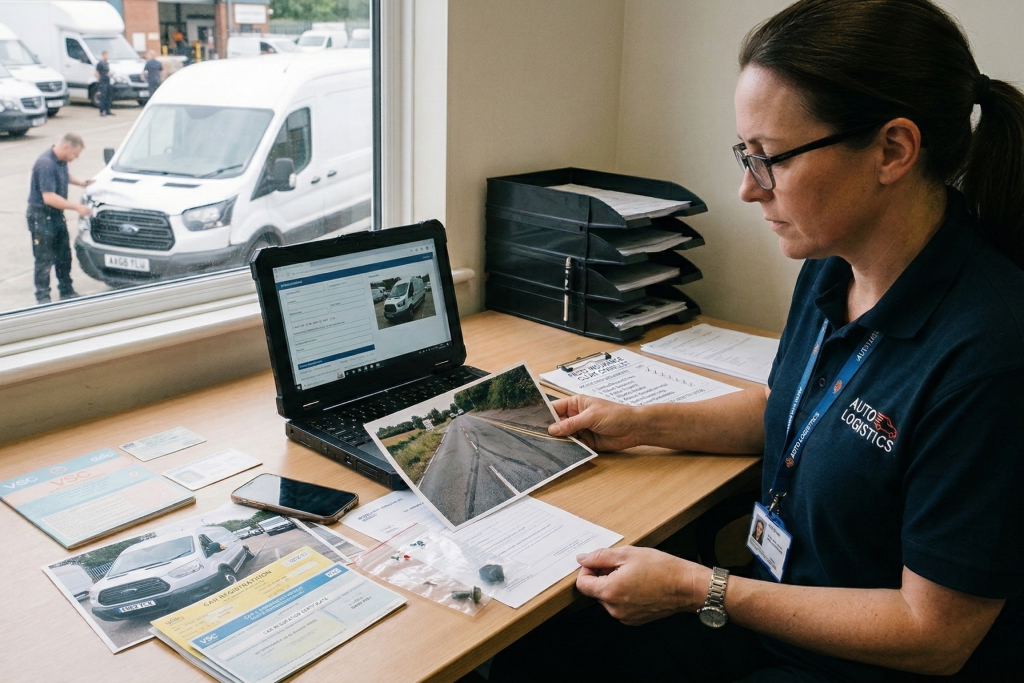
When a company vehicle is involved in a crash, the damage does not stop at the body shop. For construction companies, engineering firms, property owners, architects, government agencies, and real estate developers, one accident can slow down an entire project. Materials may not arrive on time. Inspectors may miss deadlines. Crews may be left waiting. And in serious cases, lawsuits may follow. In Florida, fleet vehicles are everywhere — from dump trucks hauling concrete to site, to engineering consultants driving between inspections, to property managers responding to maintenance calls. Whether the crash happens on a busy highway in Miami or near a job site in Orlando, what happens immediately after the collision can determine whether a fleet insurance claim is approved smoothly or becomes a long, expensive problem. At The Reyes Firm, we represent injured individuals throughout Florida. We also understand how businesses can protect themselves when accidents happen. A properly handled fleet insurance claim protects both your company and the people involved. Below is a detailed, practical guide designed specifically for professionals managing commercial vehicles and active projects. What Is a Fleet Insurance Claim? A fleet insurance claim is a formal request for payment under a commercial auto policy that covers multiple vehicles under one contract. Instead of insuring each truck or car separately, businesses bundle them into one fleet policy. Fleet insurance typically covers: Bodily injury liability Property damage liability Collision coverage Comprehensive coverage Uninsured/underinsured motorist coverage Sometimes cargo or equipment coverage For construction firms and engineering companies, fleet policies often have higher coverage limits because vehicles may cause significant damage if involved in a crash. A loaded dump truck or utility vehicle presents far greater risk than a personal sedan. Unlike personal auto claims, fleet insurance claims often trigger internal insurance investigations. Insurers may review safety programs, training records, maintenance logs, and compliance documentation before approving payment. That is why preparation and documentation matter. Why Proper Documentation Matters in Florida Florida has unique insurance and liability laws. While personal vehicles operate under a no-fault system, commercial vehicle accidents can involve additional layers of responsibility. If a company driver was performing job duties at the time of the crash, the employer may be legally responsible. This is known as “vicarious liability.” In other words, if the driver was working, the company may share liability for injuries or damages. For construction professionals and government contractors, this risk is even higher because: Fleet vehicles are often large and heavy Work zones increase accident risk Multiple contractors may be present Public safety may be involved Insurance companies carefully review fleet insurance claims involving injuries because they can lead to large settlements. Clear documentation protects your company from exaggerated claims or false allegations. Fleet Insurance Claim Checklist: Essential Documents Strong documentation is the backbone of a successful fleet insurance claim. Below is a deeper look at what your company should collect and preserve. 1. Police Crash Report Always obtain the official crash report. This document provides a neutral third-party account of the accident. It typically includes: Officer observations Road and weather conditions Diagrams of the accident scene Statements from drivers and witnesses Any citations issued For companies working near active construction zones, this report may also mention traffic control setups, barricades, and signage. Never rely solely on verbal descriptions. The official report becomes critical evidence if disputes arise. 2. Driver’s Employment and Qualification Records Insurance companies may ask: Was the driver properly licensed? Was the driver trained? Was the driver authorized to operate that vehicle? Maintain organized records including: Driver’s license and CDL copies Drug and alcohol testing compliance (if required) Safety training certifications Employment status confirmation For engineering firms and public agencies, compliance with safety regulations strengthens your position during a fleet insurance claim investigation. 3. Fleet Insurance Policy Details Keep a complete copy of your current policy readily accessible. Review: Coverage limits Deductibles Exclusions Endorsements Named insured entities Real estate developers and government contractors often have contracts requiring specific insurance minimums. After an accident, confirm your policy satisfies contractual obligations. 4. Vehicle Maintenance and Inspection Logs Maintenance records are one of the first things insurers examine. If brake failure or tire blowouts contributed to the crash, insurers will investigate whether: Regular inspections were performed Repairs were delayed Known defects were ignored Construction companies should maintain: Daily vehicle inspection checklists Quarterly service logs Repair invoices These records demonstrate responsible fleet management. 5. Internal Incident Report Require drivers to complete a written report immediately. The report should detail: Exact timeline Speed estimates Traffic signals Conversations at the scene Environmental conditions Encourage factual, simple statements — no opinions or guesses. Prompt documentation prevents inconsistencies later. Photos You Must Take After an Accident Photographs are powerful evidence in a fleet insurance claim. Wide-Angle Scene Photos Capture: Road layout Lane markings Traffic lights Construction signage Skid marks Debris fields If the accident occurred near a project site, photograph traffic cones, barricades, and warning signs. Close-Up Damage Photos Document: All vehicle damage License plates Company markings Cargo damage Equipment inside the vehicle For architects and property managers transporting materials or tools, damaged contents may be separately covered under certain policies. Environmental and Weather Conditions Take photos of: Rain or standing water Poor lighting Obstructed signage Uneven road surfaces These details can affect liability determinations. Common Mistakes That Hurt a Fleet Insurance Claim Many companies unintentionally weaken their case. 1. Delayed Reporting Fleet policies require prompt notice. Delays may lead to denial of coverage. Develop an internal policy requiring immediate reporting to fleet managers and insurers. 2. Poor Driver Training If a driver lacks documented safety training, insurers may question company oversight. Invest in ongoing driver education. 3. Failing to Preserve Electronic Data Modern vehicles contain: GPS tracking Dash cam footage Telematics data Immediately secure this data after an accident. Automatic overwriting can destroy valuable evidence. 4. Direct Communication with Claimants After serious accidents, injured parties or attorneys may contact your company directly. All communications should be directed to insurance representatives or legal counsel. Informal statements

Scroll to Top