Author name: Edward Reyes, Esq

Martial assets
Family Law, Legal, Real Estate, Trust, Why we serve

Martial Assets. Who owns what…

Divorces can be very emotional. Especially when their are kids and property. In this video we will discuss who owns what and why. Subscribe below and stay informed. Our firm has handled numerous accident cases. We have the staff to devote to investigating your accident; we can help you obtain medical treatment for your injuries and obtain the settlement that you are entitled to. Contact The Reyes Firm at 813-421-3411 We are here for you 24/7 and have the experience to protect your interests and get you the recovery you deserve. Call us today – and above all be safe on the roads!

Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Spanish, Why we serve

Accidente?

Los accidentes automovilísticos son estresantes. En el momento del accidente es posible que no sepa qué hacer o decir. Puede decir demasiado o no obtener la información correcta. Puede que no sepa a quién llamar. Este video explica lo que sucede y lo que debe hacer. Si está involucrado en un accidente automovilístico, llámenos al 813-421-3411 Auto accidents are stressful. At the time of the accident you may not know what to do or say. You may say too much or not get the correct information. You may not know who to call. This video explains what happens and what you need to do. If you are involved in a car accident, call us 813-421-3411

Quién Paga las Reparaciones del Automóvil en Florida
After A Car Accident, Body Shops, Settlement

¿Quién Paga las Reparaciones del Automóvil en Florida?

Su automóvil quedó destrozado y no fue su culpa. El otro conductor lo chocó, así que su seguro debería pagar la reparación de inmediato, ¿verdad? No es tan sencillo. Las reglas de Florida sorprenden a casi todos, y la cobertura que usted está obligado a tener es precisamente la que no le va a servir. Esto es quién paga realmente las reparaciones después de un accidente automovilístico en Florida, y por qué. The Reyes Firm ¿Su Automóvil Quedó Dañado en un Choque en Tampa? Averigüe quién debe pagar la reparación. Had a bad day? Contáctenos Ahora $0 Lo que PIP paga por reparaciones Fla. Stat. § 627.736 $10,000 Mínimo de daños a la propiedad en Florida Fla. Stat. § 324.022 2 Años Plazo para demandar por negligencia Fla. Stat. § 95.11 50% Culpa que impide la recuperación Fla. Stat. § 768.81 Quedarse sin automóvil después de un choque es mucho más que una molestia. Afecta su trabajo, la escuela de sus hijos y sus citas médicas. Lo frustrante es que el sistema de seguros de Florida no fue diseñado para devolverlo al camino rápidamente, y la cobertura que todos asumen que los va a ayudar es justamente la que no lo hace. ¿Quién paga las reparaciones de su automóvil después de un accidente en Florida? En la mayoría de los casos, la responsabilidad final recae sobre la cobertura de responsabilidad por daños a la propiedad del conductor que causó el choque. Esa cobertura existe precisamente para pagar los daños que ese conductor le ocasiona al vehículo de otra persona, y esa persona es usted. El problema está en el tiempo y en los límites. La aseguradora del otro conductor no autoriza nada hasta terminar su investigación y aceptar la responsabilidad, y aun cuando la acepta, solo paga hasta el límite de la póliza. Por eso la respuesta práctica casi siempre depende de qué cobertura tiene usted mismo. 💡 ¿Sabía usted? Su cobertura PIP no paga absolutamente nada por reparar su automóvil. A pesar de ser la cobertura que todo conductor de Florida está obligado a tener, PIP cubre únicamente gastos médicos y una parte de la pérdida de salario. No toca los daños a la propiedad ni las reparaciones del vehículo. Fuente: Fla. Stat. § 627.736. ¿Por qué el seguro obligatorio de Florida no repara su automóvil? Porque Florida exige muy poco. Todo conductor debe tener $10,000 en Protección contra Lesiones Personales (PIP) y $10,000 en responsabilidad por daños a la propiedad, según el Estatuto de Florida § 324.022. Ninguna de las dos funciona como la gente espera. PIP es cobertura médica y de salario, nada más. La responsabilidad por daños a la propiedad paga los daños que usted le causa a la propiedad de otra persona, así que no hace nada por su propio vehículo. El resultado es que un conductor que solo tiene el mínimo legal de Florida no tiene ninguna cobertura para reparar su propio automóvil. Eso no es una laguna legal, así fue diseñado el mínimo. ¿Cuáles son sus opciones para reparar el automóvil? Usted tiene principalmente tres caminos, y se diferencian sobre todo en la rapidez: La cobertura de daños a la propiedad del conductor culpable. Es quien debe pagar al final, pero es la vía más lenta. Espere a que acepten la responsabilidad, y tenga en cuenta que solo pagan hasta el límite de su póliza. Su propia cobertura de colisión. Es opcional, pero es la vía más rápida. Repara su vehículo sin importar quién tuvo la culpa, menos su deducible. Su aseguradora luego busca recuperar ese dinero del culpable mediante la subrogación. Pagar de su bolsillo y reclamar después. Guarde absolutamente todos los recibos y estimados, porque el costo razonable de la reparación es recuperable del conductor responsable. Si un vehículo comercial causó el choque, el reclamo pasa por la aseguradora de una empresa y las reglas cambian bastante. Puede leer más sobre la responsabilidad de la empresa de camiones después de un choque en Florida. ¿Qué pasa si el conductor culpable solo tiene la cobertura mínima? Aquí está el problema que más sorprende a la gente. El mínimo de $10,000 en daños a la propiedad se estableció hace décadas, y un vehículo moderno puede superar fácilmente esa cifra en daños. Si el conductor culpable solo lleva el mínimo y su automóvil sufrió $18,000 en daños, la póliza de esa persona simplemente no alcanza. Cuando eso ocurre, sus opciones se reducen a su propia cobertura de colisión, a demandar personalmente al conductor culpable (algo que rara vez sirve si esa persona no tiene bienes), o a absorber la diferencia. En algunos casos el dueño del vehículo también puede ser responsable aunque no manejaba, como explicamos en nuestra guía sobre la entrega negligente de un vehículo en Florida. ⚠️ Advertencia de plazo: Bajo el Estatuto de Florida § 95.11, generalmente tiene dos años desde la fecha del choque para presentar una demanda por negligencia, y ese mismo plazo aplica a los reclamos por daños a su propiedad. Este plazo se redujo de cuatro años a dos en marzo de 2023, así que las guías más antiguas están desactualizadas. No espere para llamar a un abogado. ¿Puede recuperar el “valor disminuido” de su vehículo? Es posible, y casi nadie lo reclama. Aunque el taller repare su automóvil perfectamente, el vehículo ahora tiene un historial de accidente y por lo general vale menos en el mercado de reventa que antes del choque. Esa pérdida se llama valor disminuido, y en Florida puede formar parte de su reclamo por daños contra el conductor responsable. Hay un detalle importante que conviene entender. El valor disminuido generalmente se reclama contra el conductor culpable y su aseguradora, no contra su propia póliza de colisión, porque la obligación de su aseguradora normalmente se limita a reparar el vehículo. Para sustentar un reclamo de este tipo suele hacer falta un avalúo profesional que documente la diferencia de valor. Un abogado puede evaluar si su caso lo justifica. ¿Qué pasa si su

Who pays for rental cars after a crash
After A Car Accident, Uninsured Motorist Coverage

Who Pays for the Rental Car After a Florida Crash?

Your car is in the shop and you still have to get to work tomorrow. The other driver caused the crash, so their insurance should just hand you a rental, right? Not quite. Florida’s rules surprise almost everyone, and the wrong assumption can leave you paying for weeks of rental out of pocket. Here is who actually pays for a rental car after a car accident in Florida, and why. The Reyes Firm Stuck Without a Car After a Tampa Crash? Find out who should be paying for your rental. Had a bad day? Contact Us Now $0 What PIP pays toward a rental Fla. Stat. § 627.736 $10,000 Florida minimum property damage liability Fla. Stat. § 324.022 2 Years Deadline to file a negligence claim Fla. Stat. § 95.11 50% Fault share that bars recovery Fla. Stat. § 768.81 Losing your car after a crash is more than an inconvenience. It affects your job, your kids’ school run, and your medical appointments. The frustrating part is that Florida’s insurance system was not built to get you back on the road quickly, and the coverage most people assume will help is the one coverage that will not. Who pays for a rental car after a car accident in Florida? In most cases the at-fault driver’s property damage liability coverage is ultimately responsible for your rental while your car is being repaired. But “ultimately” is doing a lot of work in that sentence. Their insurer generally will not authorize a rental until it has investigated and accepted liability, and that can take days or weeks. Meanwhile, you still need to get to work. That gap is why the real answer usually depends on what coverage you carry yourself. Understanding your options before you call anyone can save you both money and a lot of frustration. 💡 Did You Know? Your Personal Injury Protection coverage pays nothing toward a rental car. Despite being the coverage every Florida driver is required to carry, PIP covers only medical expenses and lost wages. It does not touch property damage, vehicle repairs, or rentals. Source: Fla. Stat. § 627.736. Why doesn’t your required Florida insurance cover the rental? Florida requires very little. Every driver must carry $10,000 in Personal Injury Protection and $10,000 in property damage liability under Florida Statute § 324.022. Neither of those helps you the way most people expect. PIP is medical and wage coverage only. Property damage liability is coverage that pays for damage you cause to someone else’s property, so it does nothing for your own car or your own rental. The result is that a driver carrying Florida’s legal minimum has no coverage at all for their own vehicle or a replacement while it is repaired. That is not a loophole, it is how the minimum was designed. What are your options for getting a rental right now? You generally have four paths, and they differ mostly in how fast they work: Rental reimbursement on your own policy. This optional add-on is usually the fastest route. It pays a set daily amount, often something like $30 to $50 per day up to a maximum number of days. Check your declarations page, because many people carry it without realizing. The at-fault driver’s property damage liability coverage. The correct payer in the end, but slow. Expect to wait for their liability decision, and expect them to limit the rental to a “reasonable” repair period and a modest class of vehicle. Your collision coverage. This repairs your car regardless of fault, minus your deductible. Important caveat: collision pays for the repair, not the rental. Without rental reimbursement, you are still on your own for the car. Pay out of pocket and claim it later. Keep every receipt. The reasonable cost of a substitute vehicle is recoverable from the at-fault party as part of your damages. If a commercial vehicle caused your crash, the process runs through a business insurer instead, which changes the dynamics considerably. Our overview of truck and commercial vehicle accidents explains how those claims differ. What is “loss of use,” and can you recover it? Loss of use is the legal term for being deprived of your vehicle, and in Florida it is a real, recoverable category of damages. When someone else’s negligence takes your car off the road, the reasonable cost of a substitute vehicle for a reasonable period is part of what you can recover from them. Two words carry the weight there: reasonable cost and reasonable period. An insurer will not pay for a luxury SUV when you were driving a sedan, and it will not pay indefinitely because a shop is slow for reasons unrelated to the repair. This is also why documentation matters. Receipts, repair timelines, and written communication with the shop are what turn a disputed rental bill into a paid one. ⚠️ Deadline Warning: Under Florida Statute § 95.11, you generally have two years from the date of your crash to file a negligence lawsuit, and that same two-year deadline applies to negligence claims for property damage. This was shortened from four years in March 2023, so older guides are out of date. Don’t wait to call a lawyer. What if your car is a total loss? The rental math changes completely, and this catches people off guard. When a car is repairable, the rental generally covers the reasonable repair period. When a car is declared a total loss, there is nothing to repair, so the insurer typically pays for a rental only through a short, reasonable period after it makes its total loss offer, often just a handful of days for you to arrange a replacement. That means the moment your car is totaled, your rental clock is close to running out, even though buying a replacement vehicle usually takes far longer than a repair. If you disagree with the insurer’s valuation of your car, you can push back, but you should not assume the rental keeps running while you argue.

Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Company-Caused Car Accidents, Personal Injury, personal injury attorney, Spanish, Why we serve

Quién paga el alquiler del auto cuando te involucras en un accidente automovilístico?

Quién paga el alquiler del auto cuando te involucras en un accidente automovilístico? Usted está involucrado en un accidente automovilístico, ¿quién paga el alquiler? Para emergencias legales, ER está aquí para su familia. Abogado de accidentes automovilísticos 813-421-3411 www.TheReyesFirm.com   Who pays for the rental car when you involved in a car accident? You are involved in a auto accident, who pays for the rental car? For Legal Emergencies, ER is here for your family. Auto accident attorney 813-421-3411 www.TheReyesFirm.com

Accident Injuries & why, After an Accident, Business, Car accident, Family Law, Legal, personal injury attorney, Spanish, Why we serve

Fraude de seguro que necesita saber

Fraude de seguro que necesita saber El fraude en el seguro de automóviles es una preocupación y problema común entre los hispanos. Lo que necesita saber no solo afecta a la clínica, sino que también afecta a su familia. Para emergencias legales, ER está aquí para su familia. Abogado de accidentes automovilísticos 813-421-3411www.TheReyesFirm.com Auto Insurance fraud is a common concern and issue among hispanics. What you need to know it does not just effect the clinic, it also affects your family. For Legal Emergencies, ER is here for your family. Auto accident attorney 813-421-3411 www.TheReyesFirm.com Subscribe below and stay informed. We will discuss different legal issues and how they can affect your life. We also bring on many experts to cover all the aspects of the issue. The subject category that we will focus on are: 1. PERSONAL INJURY: Auto accident, injuries, slip and falls, dog bites, motorcycle accidents and injuries and more… 2. REAL ESTATE LAW AND SALES: Deeds, real estate closings, quit claim deeds, breach of contracts, escrow challenges, and much more… 4. FAMILY LAW: Divorces, child support, visitation WE ARE HERE TO SOLVE YOUR PROBLEM Contact Us WEBSITE: www.TheReyesFirm.com Office #: (813) 421-3411 FACEBOOK: WWW.FACEBOOK.COM/THEREYESFIRM ADDRESS: 3302 North Tampa St. Tampa, FL 33603 We are a Tampa Bay Law firm that responds and cares for you, your family and friends. We are here for you in many civil issues. When you call, you will scheduled to meet directly Edward Reyes the attorney.

Injured in someone's home
Personal Injury, Premise Liability

Injured in Someone’s Home in Florida: Who Is Liable?

You were at a friend’s barbecue, a family member’s house, or a neighbor’s pool when something went wrong. Now you are hurt, facing medical bills, and dreading an impossible question: do you really file a claim against someone you care about? Here is what Florida law actually says about who is liable when you are injured in someone’s home, and why the answer may surprise you. The Reyes Firm Injured at Someone Else’s Home in Tampa? Find out who actually pays before you decide anything. Had a bad day? Contact Us Now 2 Years Deadline to file an injury claim Fla. Stat. § 95.11(3)(a) 3 Levels Visitor status sets the duty owed Florida premises liability law Strict Dog owner liability for bites Fla. Stat. § 767.04 50% Fault share that bars recovery Fla. Stat. § 768.81 Getting hurt at someone else’s home is uniquely uncomfortable. The property owner is often a friend, a relative, or a neighbor, and no one wants to turn a bad afternoon into a conflict. But Florida law recognizes that homeowners have real responsibilities to the people they invite in, and the way these claims actually work is far less personal than most people assume. Can you sue a homeowner if you’re injured in their home? Yes, when a hazard on someone’s property causes your injury and the homeowner failed to meet their legal duty of care, Florida law allows you to pursue compensation. This area of law is called premises liability, and it holds property owners responsible for keeping their property reasonably safe for the people they invite onto it. Liability is not automatic, though. A homeowner is not responsible for every accident that happens under their roof. The question is whether they knew or should have known about a dangerous condition and failed to fix it or warn you about it. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your injury to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Will your friend or family member have to pay out of pocket? Usually not, and this is the single most important thing to understand before you decide what to do. Most homeowners and renters carry liability insurance precisely because accidents happen to guests. When you bring a claim after an injury at someone’s home, you are in practice making a claim against that insurance policy, not against your friend’s savings account. That changes the emotional math considerably. Your host has already paid premiums for years for exactly this situation, and the insurer, not your friend, investigates the claim, negotiates, and writes the check up to the policy limits. Many homeowners are relieved when a guest uses the coverage, because the alternative is watching someone they care about drown in medical bills after getting hurt in their home. 💡 Did You Know? A claim after an injury at someone’s home is typically paid by their homeowner’s or renter’s liability insurance, not by the homeowner personally. That is what the coverage exists for. Understanding this often removes the biggest reason injured guests hesitate to protect their own rights. Does it matter why you were at the home? It matters a great deal. Florida decides how much protection you get based on your status as a visitor, and there are three broad levels: Invited guests. If you were invited over socially, Florida gives you substantial protection. The homeowner must keep the property in a reasonably safe condition and warn you about concealed dangers they knew about or should have known about, which you could not reasonably discover yourself. Uninvited licensees. Someone who enters for their own convenience without an invitation, such as a person cutting across a yard, is owed a narrower duty. The owner must refrain from willful or wanton harm and warn of known dangers that are not obvious. Trespassers. Under Florida Statute § 768.075, a property owner generally owes a trespasser only a duty to avoid gross negligence or intentional misconduct, and Florida law limits an owner’s liability further in certain circumstances. Most guests injured at a friend’s house fall into the first category, which is the strongest position under Florida law. Workers such as contractors and delivery personnel are treated as invitees and are also well protected. What has to be proven in a home injury claim? A premises liability claim rests on four elements: the homeowner owed you a duty of care, they breached that duty, the breach caused your injury, and you suffered real damages. The heart of most cases is proving the homeowner knew or should have known about the hazard, whether that is a broken step they had been meaning to fix, a loose railing, or a puddle that sat unaddressed. One nuance surprises people. Florida has a demanding statute for slip-and-fall claims involving a transitory substance, but it applies to business establishments, not private residences. A claim at a private home follows ordinary premises liability principles instead of that heightened business standard. On the other side, a homeowner may argue the danger was open and obvious to you, which is a real defense, though it does not automatically defeat a claim in every situation. What kinds of injuries happen at someone’s home? Home injuries range from bruises to permanently disabling harm. The most common claims involve: Slip, trip, and fall injuries from wet floors, loose rugs, uneven walkways, poor lighting, or clutter Stairway and railing failures, where a broken step or a loose banister causes a serious fall Swimming pool accidents, including drownings and falls on slick decking, which in the worst cases lead to a wrongful death claim Dog bites and animal attacks, which carry their own strict rules discussed below Falling objects and structural problems, such as a collapsing deck, a falling shelf, or a rotted balcony The resulting injuries are often severe. A fall down stairs can cause a traumatic

Extending the closing
Business, Business Contracts, Legal, Real Estate, Why we serve

Extending the date on a real estate contract does not extend other important dates

Some homes close fast, some homes take a little longer. Many real estate agents extend on the closing dates on real estate contracts. That is good for the closing date, but not for all the other important dates in a real estate contract. Contact The Reyes Firm at 813-421-3411 We are here for you 24/7 and have the experience to protect your interests and get you the outcome you deserve. Call us today.  

Truck Crash
Accident Injuries & why, Car accident, Injury, Legal, Motorcycles, Police Interaction, Road Accidents, Tractor Trailer Accidents, Truck Accidents

That semi truck driver may not be awake!

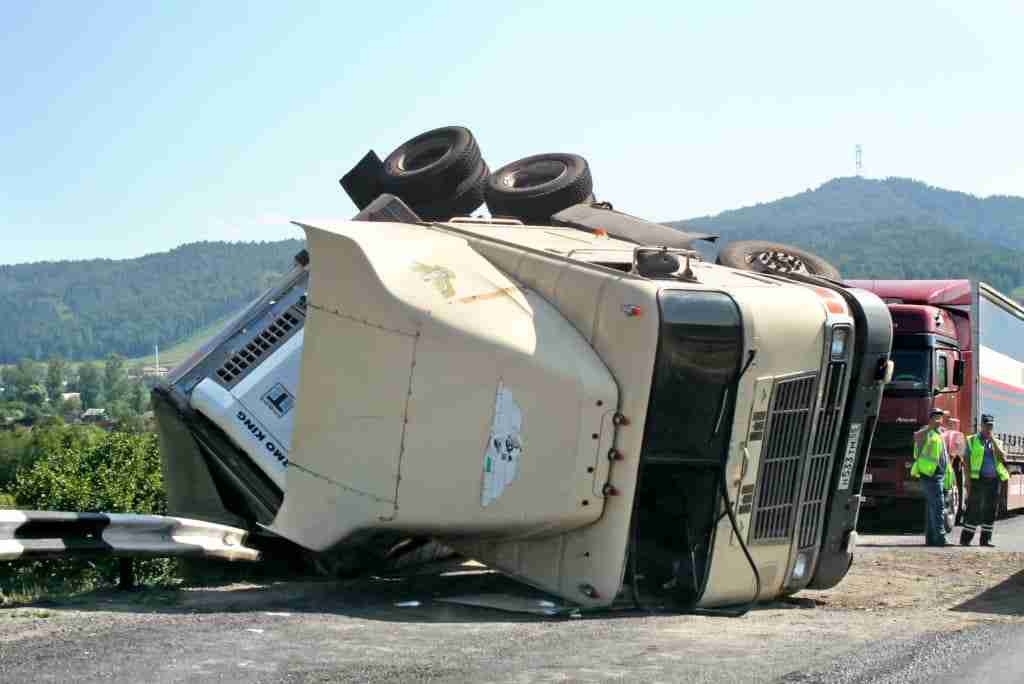
Semi trucks are everywhere. In fact, we many times do not even notice they are there. However this is how America works. The issue with trucks that there drivers of those trucks are many times sleep deprived. This many times has the drivers veer off the road. Many times we want to hurry up and pass them so we cut them off. Trucks are much heavy then the average car. Truck can not stop fast enough to stop, before they collide in to you. This video we will discuss issues that come up when dealing with semi trucks and their drivers. We will discuss ways to be be safer and hopefully avoid accidents.   Our law firm is here to help you. We believe in education and helping you be sage on the roads. For Legal Emergencies, ER is here for you. 813-421-3411 www.TheReyesfirm.com

Teens and accidents
Accident Injuries & why, Car accident, For Parents, For Teens, Injury, Legal, Personal Injury, Police Interaction, Road Accidents, Teen Accidents, Texting, Why we serve

Teens, accidents, and the LAW!

Today we will discuss with retired law enforcement officer Mark Patterson on what happens at the scene of an accident. What things teens and parents can do to reduce those accidents and what to do if you are involved in one. For Legal Emergencies, ER is here for you. 813-421-3411 www.TheReyesfirm.comSubscribe below and stay informed.

Scroll to Top