
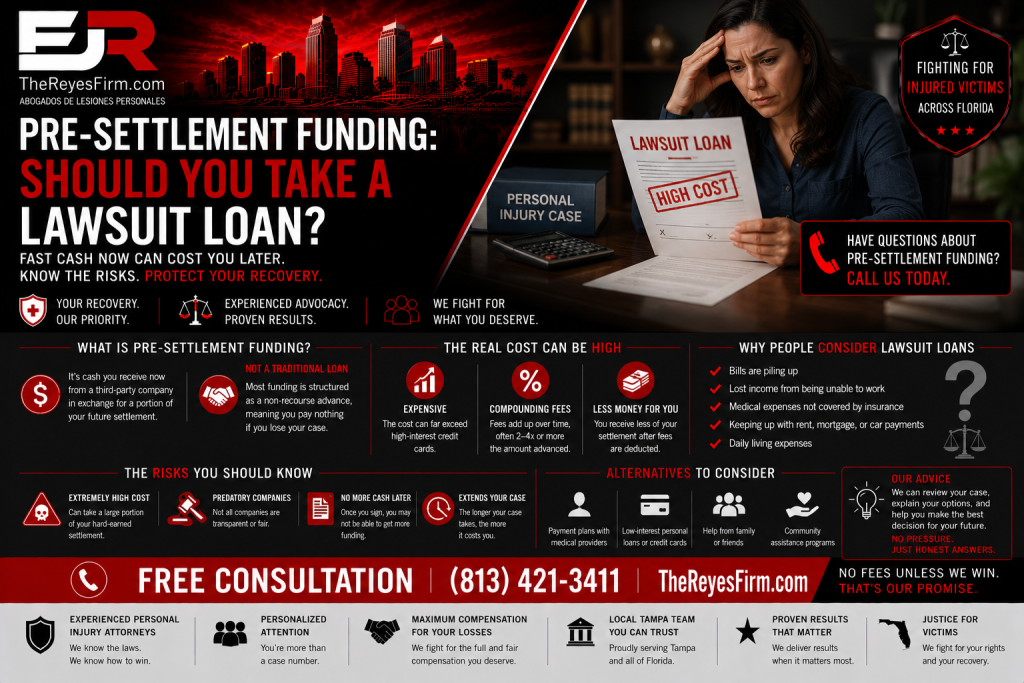
Your injury case is dragging on, the bills keep coming, and you may not be able to work. Then an ad promises fast cash against your future settlement, with nothing to pay unless you win. It can sound like a lifeline. Before you sign anything, it is worth understanding exactly how these arrangements work, what they really cost, and what other options you may have while your injury case is pending.
The Reyes Firm
Struggling Financially While Your Case Is Pending?
Talk to us before you sign a lawsuit loan. Had a bad day?
When an injury keeps you from working and the bills do not stop, financial pressure is real, and it can tempt you into decisions you would not otherwise make. Pre-settlement funding companies know this, which is why their marketing is everywhere. These products are not inherently a scam, but they are expensive and often misunderstood, so going in with clear eyes matters.
What is pre-settlement funding, or a lawsuit loan?
Pre-settlement funding is a cash advance provided by a third-party company against the settlement or judgment you expect to receive in your pending case. People often call it a lawsuit loan, though as we will see, it is usually not structured as a loan at all. The company gives you money now, and in exchange it is entitled to be repaid, usually a larger amount, out of your eventual recovery.
The feature that makes it attractive is that it is typically non-recourse. That means if your case does not succeed and you recover nothing, you generally owe the company nothing. The company is betting on your case, and it prices that risk into the cost, which is where the expense comes from.
Why do people consider a lawsuit loan?
The reasons are usually pressing and completely understandable. An injury can stop your income while your medical bills, rent, and everyday expenses continue. Cases take time to resolve properly, and waiting can be genuinely difficult when money is tight, as our guide to how your case progresses during the pre-suit phase explains.
There is also a subtler reason that matters. When you are financially desperate, you are far more likely to accept a quick, lowball settlement offer just to get money now. Some people turn to funding specifically to relieve that pressure so they can hold out for a fair result. That is a legitimate concern, but as we will explain, funding is not the only way to address it, and it comes at a real cost.
How does pre-settlement funding actually work?
The process is usually straightforward. You apply to a funding company, which then contacts your attorney to evaluate the strength and likely value of your case. Unlike a traditional lender, the company generally does not look at your credit score or income, because it is relying on your case, not your finances, for repayment. If it approves you, it advances a portion of your expected recovery, often a modest percentage of the anticipated settlement.
When your case resolves, the company is repaid directly from the settlement, typically before you receive your share, along with its fees. Because the arrangement is generally written as a purchase of a piece of your future proceeds rather than a loan, it often falls outside the lending laws that cap interest and protect borrowers, which is a key reason the cost can climb so high.
💡 Did You Know? A lawsuit loan is usually not legally a loan. It is typically structured as a non-recourse purchase of part of your future settlement, which means the usury caps and consumer lending protections that limit other high-interest credit often do not apply. Regulation of this industry varies by state and continues to evolve.
What’s the catch? The real cost of lawsuit loans.
The catch is the price. Pre-settlement funding is among the most expensive money you can get, and the effective cost can far exceed even high-interest credit cards. Charges are often applied at rates that compound over time, so the amount you owe does not just grow, it accelerates. On a case that takes a year or two to resolve, which is common, the total you must repay can end up being several times the amount you originally received.
This is the part that catches people off guard. A few thousand dollars taken early in a case can consume a large share of the settlement by the time it resolves, and in a long case with a modest recovery, the funding company’s cut can swallow a painful portion of what should have been yours. The money you accept today is money, and often much more, taken directly out of your future recovery.
⚠️ Important Warning: Before signing any funding agreement, get the full cost in writing, including exactly what you would owe at six months, one year, and two years out. Because the fees often compound, the balance can balloon over a long case and consume much of your settlement. If a company will not clearly show you the total repayment over time, treat that as a serious red flag.
What alternatives should you consider first?
Before turning to funding, it is worth exhausting less costly options, several of which your lawyer can help you with:
- Health insurance and letters of protection. For medical bills, using your health insurance or arranging for providers to treat you under a letter of protection, paid from your eventual settlement, can ease pressure without a funding company.
- Your PIP benefits. In a Florida auto case, your Personal Injury Protection can cover a portion of medical bills and lost wages regardless of fault, which may help in the near term.
- Negotiating with creditors. Many medical providers and creditors will set up payment plans or pause collections when they know a claim is pending.
- Family or personal resources. A short-term arrangement with family, or a lower-cost form of credit, may cost far less than pre-settlement funding.
- Moving your case efficiently. Sometimes the best answer is a lawyer working to resolve your case as promptly as the facts allow, so you are not waiting any longer than necessary.
None of these fit every situation, but they are frequently cheaper than funding, and they are worth exploring before you commit a piece of your recovery to a third party.
How can your lawyer help with this decision?
This is exactly the kind of decision you should not make alone, and your lawyer is your best resource for it. A good attorney can walk you through the true cost of any funding offer, compare it against alternatives, and help you understand how it would affect your net recovery at the end of the case. In many situations, a lawyer can help you find a less expensive path, or ease the pressure that made funding feel necessary in the first place.
Your lawyer can also protect you from being rushed. Funding companies, like insurers offering a quick lowball settlement, benefit when you feel desperate. Having someone in your corner who works for you, and only you, is the best defense against an expensive decision made under pressure. When your case does resolve, your lawyer also handles repaying any funding from the settlement, which we cover in our guide to what happens after you receive your settlement check.
🛡️ Your Rights: You have the right to understand the full cost of any funding before you agree, to take the time to consult your attorney, and to say no. You should never feel pressured or rushed into signing. Your lawyer works for you, not for any funding company, and can help you weigh whether this is truly your best option.
What should you do before you take a lawsuit loan?
These five steps protect your finances and your recovery. The order matters.
- Talk to your lawyer first. Before contacting any funding company, ask your attorney about the true cost, the alternatives, and how funding would affect your final recovery.
- Get the full cost in writing. Insist on seeing exactly what you would owe at several points in time, with all fees included, so you understand how the balance grows.
- Explore alternatives. Look into health insurance, letters of protection, PIP benefits, payment plans, and other resources before committing a piece of your settlement.
- Borrow only what you truly need. Because the cost grows with both the amount and the time, taking the smallest amount necessary limits the damage to your recovery.
- Never let money pressure your case. If funding is meant to help you hold out for a fair result, make sure it is not quietly costing you that result instead. Call 833-4 BAD DAY to talk it through.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm helps you navigate your case and your options
Financial pressure during a case is something we take seriously, because it can push good people into costly decisions. We help our clients understand every option, throughout Tampa and Hillsborough County.
When a client is struggling financially while a case is pending, we typically:
- Explain your case timeline honestly, so you can plan around a realistic picture rather than an anxious guess
- Help you understand the true cost of any funding offer, before you commit a piece of your recovery to a third party
- Point you toward less expensive alternatives, such as letters of protection, coordinating your benefits, and negotiating with creditors
- Work to move your case efficiently, so you are not waiting any longer than the facts of your case require
- Handle repayment properly at the end, accounting for any funding as part of a clear settlement statement
- Protect you from pressure, whether from a funding company or an insurer dangling a quick, inadequate settlement
No lawyer can promise an outcome, and we do not give financial advice. What we can promise is that we will give you an honest picture of your options, so that a decision about your money is made with clear information rather than under pressure. You can also read our overview of what drives the value of a settlement to better understand your case.
Frequently asked questions about pre-settlement funding in Florida
What is pre-settlement funding?
It is a cash advance from a third-party company against the settlement you expect to receive in a pending case. It is often called a lawsuit loan, though it is usually structured as a purchase of part of your future recovery rather than a traditional loan.
Is a lawsuit loan really a loan?
Usually not. Most pre-settlement funding is structured as a non-recourse purchase of a portion of your future settlement, which is part of why it often falls outside the lending laws that cap interest and protect borrowers.
Do I have to pay it back if I lose my case?
Typically no. Because these arrangements are generally non-recourse, if you recover nothing you usually owe nothing. That risk to the company is exactly why the cost is so high when you do recover.
How much does pre-settlement funding cost?
It is among the most expensive money available. The effective cost can far exceed high-interest credit cards, and because charges often compound, the amount owed can grow to several times the amount advanced over a case that lasts a year or two.
Why do people get lawsuit loans?
Usually because an injury has stopped their income while bills continue, or to relieve the financial pressure that might otherwise force them to accept a lowball settlement. These are real concerns, though funding is not the only way to address them.
Are there cheaper alternatives?
Often, yes. Health insurance, letters of protection, PIP benefits, payment plans with creditors, and family resources can all be less costly. Your lawyer can help you explore these before you commit a piece of your settlement.
Should I talk to my lawyer before getting one?
Absolutely. Your lawyer can explain the true cost, compare it to alternatives, show how it would affect your net recovery, and help protect you from being pressured into an expensive decision.
Will a lawsuit loan reduce my settlement?
Yes. Funding is repaid from your settlement, usually before you receive your share, so it directly reduces your net recovery, and because of the high cost, that reduction can be substantial.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. He represents people injured by the negligence of others in cases involving car accidents, truck crashes, and other serious injuries throughout Tampa and the surrounding counties. Edward Reyes, Esq. handles personal injury claims on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day, whether a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault, The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.
The information in this blog post is for general informational purposes only and is neither legal advice nor financial advice. Pre-settlement funding terms, costs, and regulations vary widely by company and by state, and the decision to use it is a personal financial one. Reading this article does not create an attorney-client relationship with The Reyes Firm. Every case is unique. If you have been injured in an accident that wasn’t your fault, consult a licensed Florida personal injury attorney about your specific situation.


