
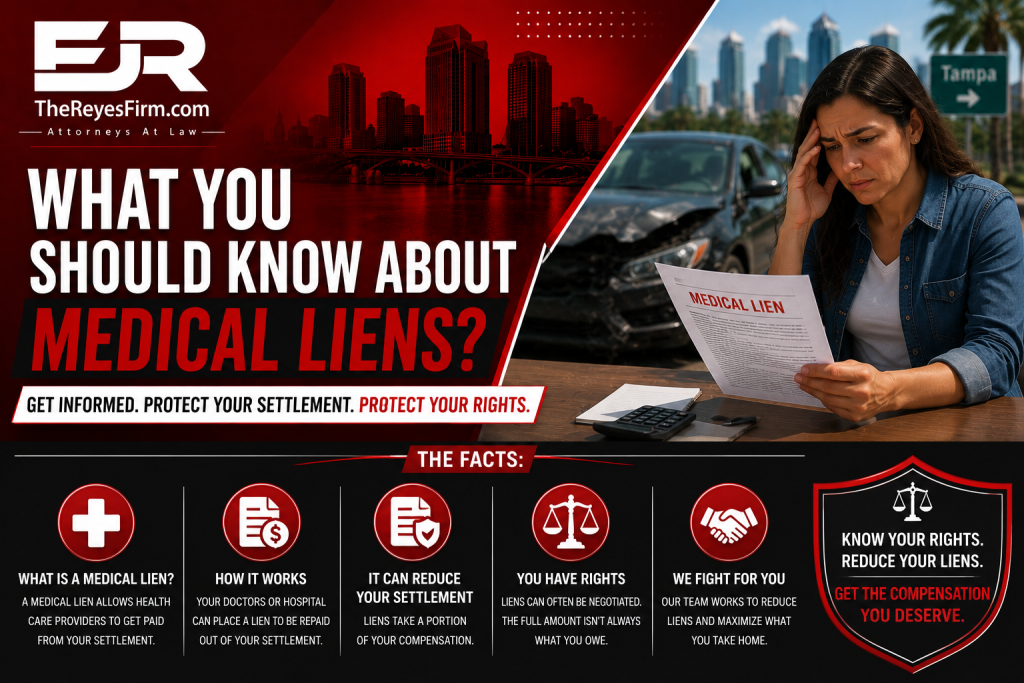
You did the smart thing after your Tampa accident and used your health insurance to get the care you needed. Then you hear a word that makes your stomach drop: lien. Suddenly it sounds like everyone who paid a medical bill wants a piece of your settlement. Here’s what a medical lien really is, who can claim one in Florida, and why the right approach often leaves more money in your pocket, not less.
TL;DR — QUICK SUMMARY
- A medical lien is a legal claim to be repaid from your settlement by whoever covered your accident-related medical care.
- Your health insurer can seek repayment through subrogation, but under Florida Statute 768.76 its lien is reduced by its share of your attorney’s fees and costs.
- Medicare and Medicaid have far stronger repayment rights that cannot be ignored, with Medicaid’s lien attaching automatically under Florida Statute 409.910.
- Using health insurance usually shrinks the bill, because insurers pay providers at reduced negotiated rates, so less comes out of your recovery.
- Most liens are negotiable, and resolving them before you sign is how you protect what you actually take home.
The Reyes Firm
Worried a Lien Will Eat Your Settlement?
Let us protect what you take home from your Tampa claim. Had a bad day?
What is a medical lien, and why does it come out of your settlement?
A medical lien is a legal claim to be repaid from your settlement by an insurer, provider, or government program that covered your accident-related medical care. The idea behind it is simple: those bills were paid on the understanding that, if someone else caused your injuries, the money would be paid back out of whatever you recover from the at-fault party.
This matters most when your injuries are serious and your bills are large, such as after a catastrophic crash. A lien does not reduce what the at-fault party owes you. It determines how much of your recovery you actually keep after the people who paid your bills are reimbursed, which is why understanding and controlling these liens is a real part of winning your case.
Who can put a lien on your personal injury settlement in Florida?
Several different parties can claim repayment, and they do not all have the same rights. The most common lien holders are your private health insurer, which may seek reimbursement through subrogation; hospitals, which in some Florida counties, including parts of the Tampa and Hillsborough County area, can assert a lien under a local ordinance; and government programs like Medicare and Medicaid, which have powerful repayment rights set by statute.
There is also a fourth situation. If you had no health insurance, or chose not to use it, a doctor may have treated you under a Letter of Protection, which is an agreement to wait and be paid directly from your settlement. That arrangement creates a lien-like claim on your recovery too. The first job in any case is identifying every one of these claims, because a lien you forget about does not disappear, it follows you.
How does health insurance subrogation actually work?
When your health insurer pays accident-related bills, it often has a right to be paid back out of your settlement, and that right is called subrogation. Under Florida Statute § 768.76, a health insurer that has properly asserted this right can be reimbursed only from what you actually recover, and its claim is reduced by its pro-rata share of the attorney’s fees and costs you paid to obtain that recovery.
Two things make this far better for you than it first sounds. The insurer is usually repaid based on the discounted rate it actually paid the provider, not the much higher billed amount, and that repayment is then cut down by its share of your legal costs. The main exception is a self-funded employer health plan governed by federal ERISA law, which can have stronger reimbursement rights than a state-regulated plan, so the type of plan you have genuinely matters to the outcome.
💡 Did You Know? Under Fla. Stat. § 768.76, a health insurer’s reimbursement is limited to what you actually recovered and must be reduced by the insurer’s pro-rata share of your attorney’s fees and costs. Combined with the discounted rates insurers pay providers, this often means using your health insurance leaves you with more money than letting the full medical bill ride to settlement. Source: Fla. Stat. § 768.76, leg.state.fl.us.
What about Medicare and Medicaid liens?
Government liens are a different animal, and they cannot be ignored. Florida Medicaid is automatically subrogated to your claim and holds an automatic lien for the full amount it paid under Florida Statute § 409.910, while Medicare’s repayment rights come from federal law and function as a so-called super lien on your recovery.
The good news is that the amount these programs actually collect can often be reduced, for Medicaid by reasonably allocating your settlement to past medical expenses, and for Medicare through its conditional-payment resolution process. The bad news is that disbursing your settlement without addressing them is a serious mistake, because the government can pursue repayment afterward, with interest. These claims come up in any case with major medical care, including large truck and commercial vehicle settlements.
⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer.
Watch: How medical liens affect your settlement
In this short video, attorney Edward Reyes explains how medical liens work and why using your health insurance can still be the smart move after an accident.
Why using your health insurance is usually still a good thing
It can feel backward to use your own health insurance for an injury someone else caused, but in most cases it works in your favor. Health insurers pay providers at contracted rates that are a fraction of the billed charges, so the underlying bill that has to be satisfied from your settlement shrinks dramatically before any lien is even calculated.
The trade-off is time. Resolving liens means finding out exactly what each payer covered, confirming the numbers, and negotiating the amount down, and that process is one of the reasons a settlement is not paid out the instant your case resolves. It is worth the wait, because the goal is not just a bigger settlement number, it is a bigger amount that actually lands in your hands.
🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible for your own harm. Because liens come out of whatever you recover, an experienced Tampa attorney works to protect the facts, challenge unfair blame, and keep your percentage of fault as low as the evidence allows.
What are the steps to protect yourself when you have medical liens?
You have more control over your final number than most people realize. These steps protect both your health and your take-home recovery, and the order matters.
- Use your health insurance for accident-related care. After your PIP benefits, letting your health insurer cover treatment usually shrinks the bill through its negotiated rates, which means less is owed back from your settlement.
- Keep every bill, statement, and explanation of benefits. These documents are how the actual amounts paid get verified, which is the foundation for negotiating any lien down.
- Tell your lawyer about every payer. List your health insurer, Medicare or Medicaid if they apply, any hospital, and any provider who treated you on a Letter of Protection, so no lien gets missed and surprises you later.
- Never ignore a Medicare or Medicaid claim. These have the strongest repayment rights of all, and failing to address them can lead the government to come after you after your case is closed.
- Do not spend your settlement before the liens are resolved. Money disbursed before liens are satisfied can still be clawed back, so the liens come first and your net recovery comes after.
- Let your lawyer negotiate the liens before you sign off. Most liens are negotiable, and reductions based on fee-sharing, settlement allocation, and whether you were made whole can put real money back in your pocket.
- Call The Reyes Firm before you settle. Once you sign a release and the money is paid, your leverage to reduce a lien is mostly gone. Call 833-4 BAD DAY for a free consultation first.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm handles your medical liens
A settlement number means very little until the liens are dealt with, and that final step is where a lot of money is won or lost. The insurers and programs that paid your bills have professionals protecting their interests. We make sure someone is protecting yours, all the way down to the last dollar you take home.
When we handle the liens on a Tampa injury case, we typically:
- Identify every lien and claim against your recovery, from your health insurer to Medicare, Medicaid, hospitals, and any Letter of Protection providers, so nothing surfaces after your case closes
- Verify what was actually paid, demanding itemized records and rejecting inflated or duplicate charges before agreeing to repay a single dollar
- Negotiate each lien down, using Florida’s fee-sharing rules, settlement allocation, and made-whole arguments to shrink what comes out of your pocket
- Hold government claims to the correct amount, working through the Medicare and Medicaid reduction processes rather than simply paying whatever is first demanded
- Coordinate liens with the full value of your case, including the serious, lasting injuries like a spinal cord injury that drive both your damages and your bills
- Show you the math, so before you sign anything you understand exactly what you are receiving and why
No lawyer can promise a specific result. What we can promise is that we treat the lien stage as seriously as the rest of your case, because the number that matters is what you keep. We help injured people in Tampa and across Hillsborough County on a contingency fee basis, which means you pay nothing unless we recover compensation for you.
Frequently asked questions about medical liens in Florida
What is a medical lien on a personal injury settlement?
It is a legal right held by someone who paid your accident-related medical bills, usually a health insurer, hospital, or government program, to be reimbursed out of the money you recover from the at-fault party. The lien is satisfied before you receive your net share.
Does my health insurance have to be paid back after a Florida accident?
Often yes, through subrogation, but under Fla. Stat. § 768.76 a health insurer’s reimbursement is limited to what you actually recover and is reduced by its share of your attorney’s fees and costs. The exact rules depend on the type of plan you have.
Why does using health insurance lower my medical bills?
Health insurers pay providers at pre-negotiated rates that are far below the billed charges. Because the lien is generally based on what was actually paid, the amount that comes out of your settlement is much smaller than the original bill.
Can Medicare or Medicaid take part of my settlement?
Yes. Medicaid holds an automatic lien under Fla. Stat. § 409.910, and Medicare has a federal repayment right that works like a super lien. Both can often be reduced, but neither can be ignored without risking the government coming after you later.
What is a Letter of Protection?
It is an agreement in which a doctor treats you without upfront payment in exchange for being paid directly from your eventual settlement. It is common when an injured person has no health insurance, and it creates a claim on your recovery much like a lien.
Can a medical lien be reduced or negotiated?
Most can. Reductions may come from fee-sharing requirements, allocating the settlement among different types of damages, or showing that you were not fully made whole. This is one of the most valuable things a lawyer does at the end of a case.
What happens if I ignore a medical lien?
It does not go away. A valid lien holder, especially a government program, can pursue you for repayment after your case closes, and spending the money first does not protect you. Liens should be resolved before any settlement is disbursed.
How much does a Tampa personal injury lawyer cost?
The Reyes Firm works on a contingency fee basis, which means you pay nothing up front and nothing at all unless the firm recovers compensation for you. The initial consultation is free.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. His practice focuses on serious injury and wrongful death cases, and on protecting every dollar of his clients’ recoveries by aggressively negotiating the medical liens that come out of a settlement. Edward Reyes, Esq. represents injured Floridians in Tampa and throughout Hillsborough County on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day — a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault — The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.


