
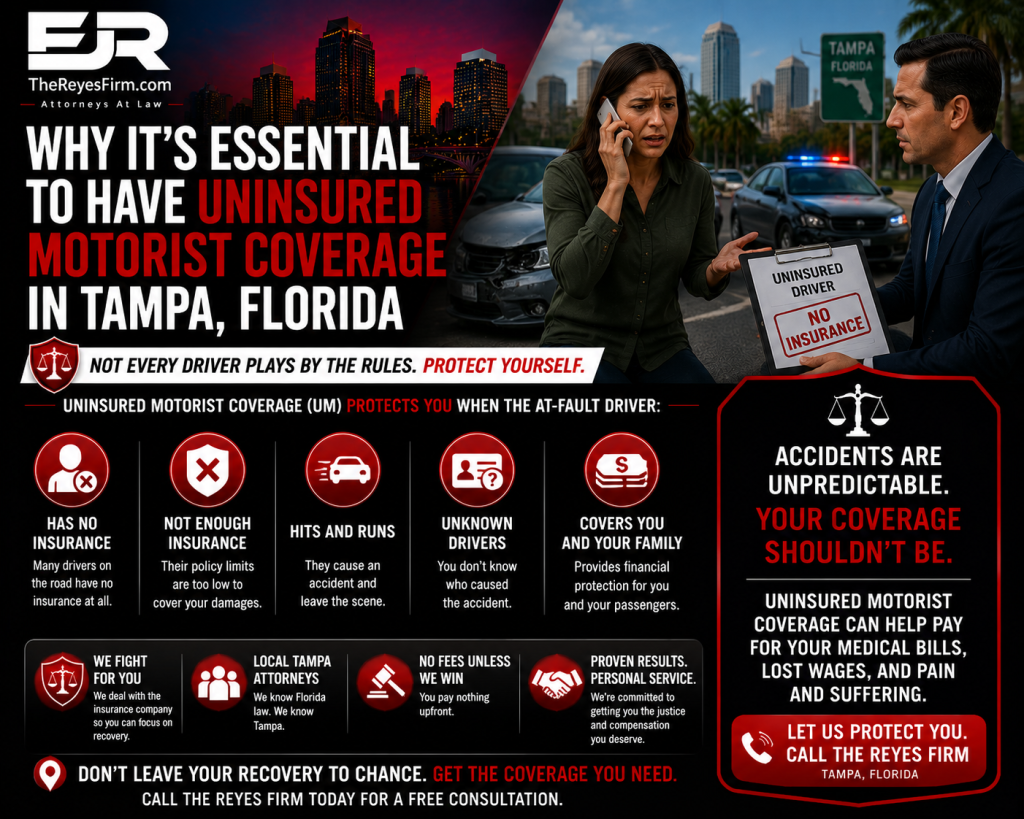
Picture this: you’re driving down Bayshore Boulevard, doing everything right, when another driver runs a light and slams into you. You’re hurt, your car is wrecked, and then you learn the driver who hit you has no insurance at all. In Florida, that nightmare is far more common than most people realize, and whether you walk away financially protected often comes down to one line on your own policy. Here’s why uninsured motorist coverage may be the most important coverage you can carry after a Tampa car accident.
TL;DR — QUICK SUMMARY
- Florida has one of the highest rates of uninsured drivers in the country, with an estimated one in five drivers carrying no insurance at all.
- Florida does not require most drivers to carry bodily injury liability coverage, so even an insured driver may have nothing to pay for the injuries they cause you.
- Uninsured and underinsured motorist (UM/UIM) coverage steps in to pay your medical bills beyond PIP, your lost wages, and your pain and suffering.
- Under Florida Statute 627.727, your insurer must offer you UM coverage, and settling with the at-fault driver without your UM carrier’s consent can wipe out that coverage.
- UM even covers hit-and-run and phantom-vehicle crashes, and you generally have two years to file an injury claim under Florida Statute 95.11(3)(a).
The Reyes Firm
Hit by an Uninsured Driver in Tampa?
Find out if your own coverage can pay your claim. Had a bad day?
Why is uninsured motorist coverage so important in Florida?
Uninsured motorist coverage is so important in Florida because two facts collide on our roads: a large share of drivers carry no insurance, and state law does not require most drivers to carry coverage for the injuries they cause. An estimated one in five Florida drivers has no auto insurance at all, one of the highest rates in the nation according to the Insurance Research Council, and Tampa’s heavy traffic and steady stream of out-of-town drivers only raise the odds of being hit by one.
Here is the part that surprises people most. Florida requires drivers to carry Personal Injury Protection and property damage coverage, but it does not require them to carry bodily injury liability coverage, which is the coverage that would pay for your medical bills and pain after a crash they caused. That means even a driver who is following the law may have nothing available to compensate you, and your own uninsured motorist coverage becomes your safety net.
What is the difference between uninsured and underinsured motorist coverage?
The two go hand in hand but apply in different situations. Uninsured motorist (UM) coverage applies when the driver who hit you has no bodily injury liability insurance at all, or cannot be identified, as in a hit-and-run. Underinsured motorist (UIM) coverage applies when the at-fault driver does have liability insurance, but not enough to cover the full extent of your injuries.
In Florida, the two are usually sold together as a single UM/UIM coverage, and both draw from your own policy. The practical point is the same in either case: when the other driver cannot make you whole, this coverage is what stands between you and paying for someone else’s mistake out of your own pocket.
How does UM coverage fill the gap left by Florida’s no-fault system?
Florida’s no-fault system gives you some protection, but not nearly enough for a serious injury. Your Personal Injury Protection coverage pays 80% of your medical bills and 60% of your lost wages, but only up to a standard limit of $10,000, and it pays nothing at all for pain and suffering. A trip to the emergency room and a single surgery can blow through that $10,000 in days.
Uninsured motorist coverage picks up where PIP stops. It can pay your medical expenses beyond the PIP limit, your lost wages and reduced earning capacity, and your pain and suffering, and it protects not just you but the relatives in your household and the passengers in your car. It is especially vital for motorcycle riders, who are not covered by PIP at all and depend heavily on UM coverage when an uninsured driver hits them.
💡 Did You Know? Florida is a no-fault state that requires only $10,000 in PIP and $10,000 in property damage coverage, and it does not require most drivers to carry bodily injury liability at all. With an estimated one in five Florida drivers uninsured, your own uninsured motorist coverage is often the only source that will pay for your injuries, lost wages, and pain and suffering. Source: Insurance Research Council; Fla. Stat. § 627.736.
Watch: Why you need uninsured motorist coverage in Tampa
In this short video, attorney Edward Reyes explains how uninsured motorist coverage works and how it can protect you when the driver who hit you cannot pay.
If you were hit by an uninsured driver, The Reyes Firm offers free consultations and can review your coverage at no cost.
Does UM coverage protect you in a hit-and-run or no-contact crash?
Yes, and this is one of its most valuable features. If a driver hits you and flees, or if a phantom vehicle runs you off the road without ever making contact, there may be no at-fault driver to identify and no liability insurance to pursue. Uninsured motorist coverage is built for exactly these situations and can pay for your injuries when the other driver vanishes.
These claims do come with conditions, often including a requirement to corroborate that another vehicle caused the crash, which makes fast evidence-gathering critical. In the most tragic hit-and-run cases, where a family loses a loved one, UM coverage can also support a wrongful death claim when the driver is never found.
⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Hit-and-run claims also depend on evidence that fades fast, so the sooner you act, the stronger your case. Don’t wait to call a lawyer.
Why your own insurance company may still fight your UM claim
It is easy to assume that because you paid for the coverage, your own insurer will pay your UM claim without a fight. In reality, the moment you file a UM claim, your insurance company is on the other side of the table. It is the one paying, so it has the same incentive any insurer has to dispute your injuries, argue they were pre-existing, and offer as little as possible.
There is also a serious trap to avoid. Under Florida Statute § 627.727, settling directly with the at-fault driver or their insurer without first getting your UM carrier’s written consent can void your uninsured motorist coverage entirely. Recorded statements and insurer-ordered medical exams are not neutral either, which is why it is wise to talk to a lawyer before agreeing to anything.
How much UM coverage should you carry, and can you stack it?
Because UM coverage is so important, you should carry as much of it as you reasonably can. Under Fla. Stat. § 627.727, your insurer must offer you UM coverage equal to your bodily injury liability limits, and you can only reject it or choose lower limits in writing, so it pays to choose meaningful limits rather than waving the coverage away to save a few dollars.
If you insure more than one vehicle, you may also be able to stack your UM coverage, which multiplies the protection available to you across your policies. Keep in mind that to recover pain and suffering through a UM claim, your injury still has to meet Florida’s permanency threshold under Florida Statute § 627.737, which is why higher limits matter most for the catastrophic injuries and spinal cord injuries that quickly exceed any policy’s limits.
🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible for your own harm. This applies to a UM claim too, so an experienced Tampa attorney works to protect the facts, challenge unfair blame, and keep your percentage of fault as low as the evidence allows.
What are the steps to protect yourself with UM coverage?
A little preparation now can save you from financial disaster later. These steps protect both your coverage and your claim, and the order matters.
- Check your policy for UM coverage today. Do not wait until after a crash to discover you declined it. If you are not sure, call your insurer or agent and ask.
- Match your UM limits to your bodily injury limits. Your insurer must offer UM equal to your liability coverage, so choose limits that would actually cover a serious injury rather than the bare minimum.
- Consider stacking if you own more than one vehicle. Stacked coverage multiplies the protection available to you and is often more affordable than people expect.
- Report the crash to your own insurer promptly. A UM claim has notice requirements, so tell your insurer what happened, while sticking to the basic facts.
- Do not settle with the at-fault driver without your UM carrier’s consent. Signing a release with the other driver’s insurer first can void your UM coverage, so get consent in writing before agreeing to anything.
- Be careful with recorded statements and medical exams. Once you file a UM claim, your insurer is adverse to you, so do not give a recorded statement before speaking with a lawyer.
- Call The Reyes Firm before you accept any offer. A UM claim is a fight with your own insurer, and you should not face it alone. Call 833-4 BAD DAY for a free consultation.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm handles your uninsured motorist claim
Filing a claim against your own insurance company feels wrong, but when an uninsured driver leaves you hurt and out of options, it is exactly what your coverage is for. Your insurer will treat the claim like any other, working to pay as little as possible. We make sure someone is fighting for everything your policy actually owes you.
When we handle a Tampa uninsured motorist claim, we typically:
- Review every layer of available coverage, including your UM and UIM limits, stacking across your vehicles, and any other policies that may apply, so no source of recovery is missed
- Protect your coverage from being voided, handling any settlement with the at-fault driver correctly so your UM rights stay intact
- Document the full extent of your injuries, including future medical care and the lost earning capacity that a serious injury leaves behind
- Push back on your insurer’s tactics, challenging claims that your injuries are pre-existing or worth less than they are
- Shield you from harmful requests, dealing with recorded-statement demands and insurer medical exams on your behalf
- Prepare your claim as if it will go to trial, which is often what moves your own insurer to pay a fair amount
No lawyer can promise a specific result. What we can promise is that we treat a fight with your own insurer as seriously as any other case, and we explain every step in plain language. We help injured people in Tampa and across Hillsborough County on a contingency fee basis, which means you pay nothing unless we recover compensation for you.
Frequently asked questions about uninsured motorist coverage in Florida
Is uninsured motorist coverage required in Florida?
No, but your insurer must offer it to you under Fla. Stat. § 627.727, and you can only reject it or choose lower limits in writing. Given how many Florida drivers are uninsured, carrying it is strongly recommended.
What is the difference between UM and UIM coverage?
UM applies when the at-fault driver has no bodily injury coverage or cannot be identified, such as in a hit-and-run. UIM applies when the driver has coverage but not enough. In Florida they are usually sold together as a single coverage.
Does Florida require drivers to have insurance for my injuries?
Not really. Florida requires only PIP and property damage coverage, not bodily injury liability, so the driver who hits you may legally have nothing available to pay for your medical bills or pain and suffering.
Does UM cover a hit-and-run?
Yes. UM coverage applies to hit-and-run crashes and even phantom-vehicle, no-contact crashes, though these claims usually require evidence corroborating that another vehicle caused the wreck.
Will my own insurance company fight my UM claim?
Often, yes. Once you file a UM claim, your insurer is the party paying, so it has the same incentive as any insurer to minimize your claim. Avoid giving a recorded statement before you talk to a lawyer.
Can settling with the other driver cancel my UM coverage?
It can. Under Fla. Stat. § 627.727, settling with the at-fault driver without your UM carrier’s written consent can void your coverage, so always get consent in writing first.
Can I stack my uninsured motorist coverage?
If you insure more than one vehicle, you may be able to stack your UM coverage, which multiplies the protection available across your policies. Whether your coverage is stacked depends on the election you made when you bought it.
How long do I have to bring a claim after being hit by an uninsured driver?
You generally have two years to file a personal injury lawsuit under Fla. Stat. § 95.11(3)(a). UM claims also carry their own notice requirements under your policy, so it is best to act quickly rather than assume you have plenty of time.
How much does a Tampa car accident lawyer cost?
The Reyes Firm works on a contingency fee basis, which means you pay nothing up front and nothing at all unless the firm recovers compensation for you. The initial consultation is free.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. His practice focuses on serious injury and wrongful death cases, including the uninsured and underinsured motorist claims that injured Floridians are forced to bring against their own insurance companies. Edward Reyes, Esq. represents injured Floridians in Tampa and throughout Hillsborough County on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day — a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault — The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.


