
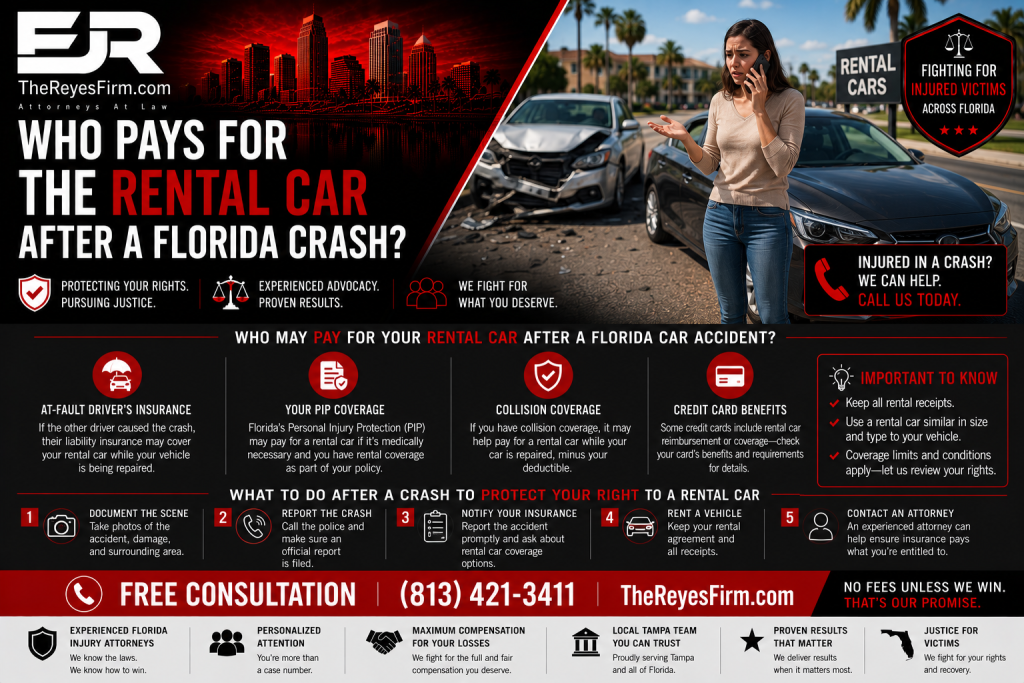
Your car is in the shop and you still have to get to work tomorrow. The other driver caused the crash, so their insurance should just hand you a rental, right? Not quite. Florida’s rules surprise almost everyone, and the wrong assumption can leave you paying for weeks of rental out of pocket. Here is who actually pays for a rental car after a car accident in Florida, and why.
The Reyes Firm
Stuck Without a Car After a Tampa Crash?
Find out who should be paying for your rental. Had a bad day?
Losing your car after a crash is more than an inconvenience. It affects your job, your kids’ school run, and your medical appointments. The frustrating part is that Florida’s insurance system was not built to get you back on the road quickly, and the coverage most people assume will help is the one coverage that will not.
Who pays for a rental car after a car accident in Florida?
In most cases the at-fault driver’s property damage liability coverage is ultimately responsible for your rental while your car is being repaired. But “ultimately” is doing a lot of work in that sentence. Their insurer generally will not authorize a rental until it has investigated and accepted liability, and that can take days or weeks. Meanwhile, you still need to get to work.
That gap is why the real answer usually depends on what coverage you carry yourself. Understanding your options before you call anyone can save you both money and a lot of frustration.
💡 Did You Know? Your Personal Injury Protection coverage pays nothing toward a rental car. Despite being the coverage every Florida driver is required to carry, PIP covers only medical expenses and lost wages. It does not touch property damage, vehicle repairs, or rentals. Source: Fla. Stat. § 627.736.
Why doesn’t your required Florida insurance cover the rental?
Florida requires very little. Every driver must carry $10,000 in Personal Injury Protection and $10,000 in property damage liability under Florida Statute § 324.022. Neither of those helps you the way most people expect.
PIP is medical and wage coverage only. Property damage liability is coverage that pays for damage you cause to someone else’s property, so it does nothing for your own car or your own rental. The result is that a driver carrying Florida’s legal minimum has no coverage at all for their own vehicle or a replacement while it is repaired. That is not a loophole, it is how the minimum was designed.
What are your options for getting a rental right now?
You generally have four paths, and they differ mostly in how fast they work:
- Rental reimbursement on your own policy. This optional add-on is usually the fastest route. It pays a set daily amount, often something like $30 to $50 per day up to a maximum number of days. Check your declarations page, because many people carry it without realizing.
- The at-fault driver’s property damage liability coverage. The correct payer in the end, but slow. Expect to wait for their liability decision, and expect them to limit the rental to a “reasonable” repair period and a modest class of vehicle.
- Your collision coverage. This repairs your car regardless of fault, minus your deductible. Important caveat: collision pays for the repair, not the rental. Without rental reimbursement, you are still on your own for the car.
- Pay out of pocket and claim it later. Keep every receipt. The reasonable cost of a substitute vehicle is recoverable from the at-fault party as part of your damages.
If a commercial vehicle caused your crash, the process runs through a business insurer instead, which changes the dynamics considerably. Our overview of truck and commercial vehicle accidents explains how those claims differ.
What is “loss of use,” and can you recover it?
Loss of use is the legal term for being deprived of your vehicle, and in Florida it is a real, recoverable category of damages. When someone else’s negligence takes your car off the road, the reasonable cost of a substitute vehicle for a reasonable period is part of what you can recover from them.
Two words carry the weight there: reasonable cost and reasonable period. An insurer will not pay for a luxury SUV when you were driving a sedan, and it will not pay indefinitely because a shop is slow for reasons unrelated to the repair. This is also why documentation matters. Receipts, repair timelines, and written communication with the shop are what turn a disputed rental bill into a paid one.
⚠️ Deadline Warning: Under Florida Statute § 95.11, you generally have two years from the date of your crash to file a negligence lawsuit, and that same two-year deadline applies to negligence claims for property damage. This was shortened from four years in March 2023, so older guides are out of date. Don’t wait to call a lawyer.
What if your car is a total loss?
The rental math changes completely, and this catches people off guard. When a car is repairable, the rental generally covers the reasonable repair period. When a car is declared a total loss, there is nothing to repair, so the insurer typically pays for a rental only through a short, reasonable period after it makes its total loss offer, often just a handful of days for you to arrange a replacement.
That means the moment your car is totaled, your rental clock is close to running out, even though buying a replacement vehicle usually takes far longer than a repair. If you disagree with the insurer’s valuation of your car, you can push back, but you should not assume the rental keeps running while you argue.
Does being partly at fault affect your rental and property damage claim?
Yes. Florida’s modified comparative negligence rule reduces what you recover in proportion to your share of fault, and that applies to your property damage and loss of use, not just your injuries. If you are assigned 20% of the blame, your recovery for the crash is reduced accordingly.
This is exactly why an insurer’s early liability decision matters so much, and why it is rarely as neutral as it looks. Their assessment of fault directly shapes what they owe you for both your car and your rental.
🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible. That reduction applies to your vehicle and rental costs too, and an experienced Tampa car accident lawyer works to keep your assigned fault as low as the evidence allows.
Watch: Who Pays for the Rental Car After a Crash?
If you prefer to hear it explained, the short video below covers who pays for a rental car after a Florida car accident and why.
When you are ready to talk through your own situation, The Reyes Firm offers free consultations with no obligation.
What are the 5 steps to get a rental car after a Tampa crash?
These five steps get you back on the road faster and protect what you can recover. The order matters.
- Check your own declarations page first. Look for rental reimbursement and collision coverage before you call anyone. If you have rental reimbursement, it is almost always your quickest route to a car today.
- Report the crash to the at-fault driver’s insurer. Open the property damage claim so their liability decision starts moving, but be careful about giving a recorded statement about how the crash happened.
- Do not wait on their approval if you need a car now. Use your own coverage or pay out of pocket rather than losing your job over a liability investigation. You can pursue reimbursement afterward.
- Keep every receipt and document the timeline. Save rental invoices, repair estimates, and the shop’s timeline. Loss of use is recoverable, but only if you can prove what it cost and why it took as long as it did.
- Call The Reyes Firm before settling anything. A property damage release can be worded to affect more than your car. Call 833-4 BAD DAY for a free consultation before you sign.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm handles your car accident case
A rental car dispute is usually the first sign of how an insurer intends to treat you on everything else. If they are slow-walking a $40-a-day rental, consider what they will do with your medical bills. We handle all of it for you, throughout Tampa and Hillsborough County.
When we take on a car accident case, we typically:
- Push the liability decision forward, so the at-fault insurer stops using its investigation as a reason to delay your rental and your repairs
- Identify every coverage that applies, including your rental reimbursement, collision, and uninsured motorist coverage when the at-fault driver has little or no insurance
- Document your loss of use properly, so the reasonable cost of a substitute vehicle is part of your claim rather than an afterthought
- Review any release before you sign it, because a property damage settlement can be drafted more broadly than you realize
- Pursue your deductible, so that when your own collision coverage pays first, you are not the one left absorbing it
- Handle the injury claim alongside the property claim, since the same insurer is evaluating both and how you handle one affects the other
No lawyer can promise an outcome. What we can promise is that we treat the whole claim seriously, explain every step in plain language, and take the fight off your plate. You can read more about what drives the value of a car accident settlement in our detailed guide.
Frequently asked questions about rental cars after a Florida crash
Does PIP cover a rental car in Florida?
No. Florida PIP covers medical expenses and a portion of lost wages only. It pays nothing toward property damage, vehicle repairs, or a rental car, even though every Florida driver is required to carry it.
Will the other driver’s insurance pay for my rental?
Usually yes, once they accept liability, through their property damage liability coverage. The problem is timing, since they generally will not authorize a rental until their investigation is complete, which can take days or weeks after the crash.
What is rental reimbursement coverage?
It is an optional add-on to your own auto policy that pays a set daily amount toward a rental, up to a cap. It is typically the fastest way to get a car after a crash, and it applies regardless of who was at fault.
How long can I keep the rental car?
Generally for a reasonable repair period. If your car is a total loss, the window is much shorter, often only a few days after the insurer makes its total loss offer, since there is no repair to wait on.
Does my collision coverage include a rental?
No. Collision pays to repair your vehicle regardless of fault, minus your deductible, but it does not include a rental. You need separate rental reimbursement coverage for that.
Can I recover the money if I pay for the rental myself?
Often yes. The reasonable cost of a substitute vehicle is recoverable as loss of use damages from the at-fault party. Keep every receipt and document the repair timeline, since you will need to prove both the cost and the reason for the duration.
What if the at-fault driver has no insurance?
Your own coverage becomes the practical path. Rental reimbursement, collision, and uninsured motorist coverage may apply depending on your policy. A lawyer can review which coverages are available to you.
How long do I have to bring a claim for my vehicle damage?
Under Fla. Stat. § 95.11, negligence claims, including negligence claims for property damage, generally must be filed within two years. That deadline was shortened from four years in March 2023, so it is best to act well before it approaches.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. He represents people injured by the negligence of others in cases involving car accidents, truck crashes, and other serious injuries throughout Tampa and the surrounding counties. Edward Reyes, Esq. handles car accident and personal injury claims on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day, whether a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault, The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.
The information in this blog post is for general informational purposes only and does not constitute legal advice. Reading this article does not create an attorney-client relationship with The Reyes Firm. Every case is unique. If you have been injured in a car accident that wasn’t your fault, consult a licensed Florida personal injury attorney about your specific situation.


