What You Need to Know
- Your own PIP insurance usually pays your medical bills first, even when the DoorDash driver caused the crash.
- Get medical care within 14 days of the crash, or you can lose PIP medical benefits.
- DoorDash says its liability insurance may apply during an active delivery, but it can sit behind the driver’s own policy. A DoorDash accident lawyer can help sort out which policy pays.
- Florida’s rideshare insurance law is written for passenger rides, so Uber and Lyft rules do not carry over to food delivery.
- For most crashes after March 24, 2023, you generally have two years to file a negligence lawsuit.
Had a bad day? Call The Reyes Firm at 833-4 BAD DAY.
A car with a red delivery bag on the dashboard just hit you. The driver says he was “just finishing an order.” Now you are hurt, your car is damaged, and you have no idea which insurance company is supposed to call you back. That confusion is why many people in Tampa start searching for a DoorDash accident lawyer within days of a crash.
Delivery crashes are different from regular car accidents. The driver’s personal policy, DoorDash’s coverage and your own insurance can all point at each other. What the driver’s app showed at the moment of the crash can change which policy applies.
This guide explains who pays first under Florida law, when DoorDash’s insurance may come into play, what to do in the first days after a crash, and when it makes sense to talk to a lawyer.
Who Pays First If a DoorDash Driver Hits You in Tampa?
In most Tampa crashes, your own personal injury protection (PIP) pays first. Florida law makes PIP primary, which means it pays before other coverage, up to $10,000 for medical and disability benefits. After that, a claim against the Dasher’s auto insurance, and possibly DoorDash’s coverage, can help cover what PIP leaves unpaid.
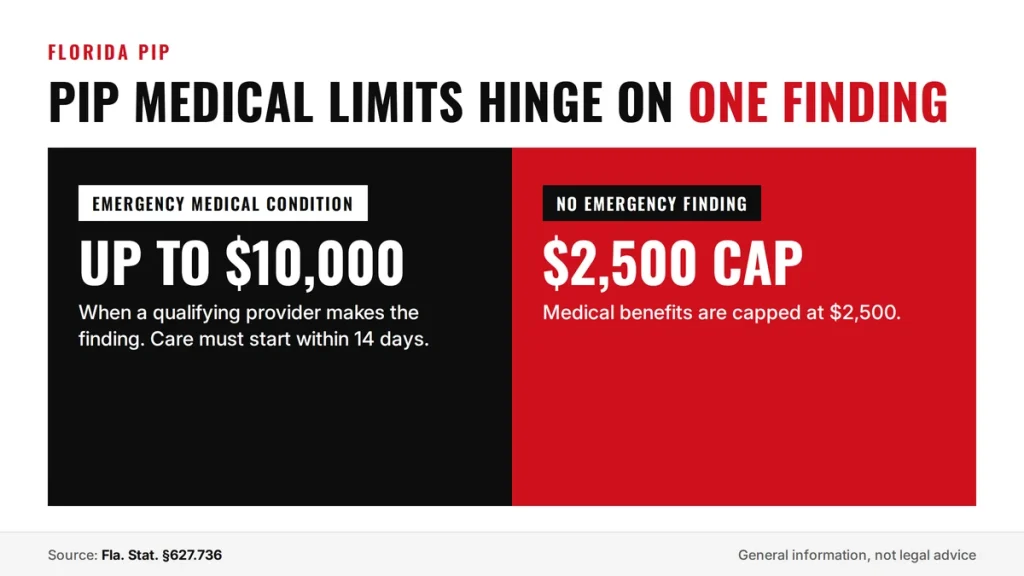 Florida PIP medical limits depend on an emergency medical condition finding. Source: Fla. Stat. 627.736.
PIP comes with Florida auto policies that meet the state’s insurance requirements. Under Fla. Stat. 627.736, it pays 80% of reasonable medical expenses and 60% of lost income, up to the policy limit.
The full $10,000 is not automatic:
- You must get initial care within 14 days of the crash.
- A qualifying provider must find you had an emergency medical condition for the full $10,000.
- Without that finding, medical benefits are capped at $2,500.
PIP rarely covers everything after a serious crash. The rest of your losses, such as pain, lost wages beyond PIP and future care, usually come from the at-fault driver’s coverage. That is where delivery cases get complicated.
| Who may pay | When it usually applies |
|---|---|
| Your PIP | First, for medical bills and lost income, up to your limit |
| The Dasher’s personal auto policy | When the Dasher was at fault and the policy covers delivery driving |
| DoorDash’s liability coverage | According to DoorDash, during an active delivery, often after the driver’s own policy |
| Your own uninsured or underinsured motorist coverage | If you bought it and the other coverage falls short |
Florida’s financial responsibility law requires $10,000 in property damage coverage under Fla. Stat. 324.022. That section does not require bodily injury coverage, so the Dasher may carry little or no coverage for your injuries.
Does DoorDash’s Insurance Cover You After a Crash?
Sometimes. DoorDash says that during an active delivery, from accepting an offer through drop-off, its third-party liability insurance may cover up to $1,000,000 for injuries and damage to others in most states. That coverage may apply only after the Dasher’s own policy, so the Florida terms need to be confirmed for every claim.
That answer comes from DoorDash’s own Dasher insurance page, not from a Florida statute. Three details on DoorDash’s pages matter most for you:
- The app status matters. DoorDash’s help center article on insurance describes the covered window as the “Delivery Available” or “Delivery Service” period. Its Dasher site describes it as offer accepted through drop-off. Those descriptions do not match exactly.
- It may be excess coverage. DoorDash says its coverage may apply after the Dasher’s own business-use or delivery-eligible policy.
- The Dasher’s policy may not cover delivery. DoorDash warns that a Dasher’s personal insurance may not provide coverage while delivering.
This is the gap that hurts injured people. The driver’s insurer may deny the claim because he was working. DoorDash’s insurer may argue the app was off, or that the driver’s own policy must pay first. You can end up stuck in the middle while the bills pile up.
DoorDash also says its coverage aims to match each state’s requirements. So the national $1,000,000 figure should not be treated as a guaranteed Florida limit.
DoorDash is not Uber. Many websites mix the two together. Florida’s rideshare insurance law, Fla. Stat. 627.748, is built around “prearranged rides” that carry passengers. By its own terms, it does not describe food delivery. Rideshare coverage tiers should not be assumed to apply to a DoorDash crash. If you were hurt by a food delivery driver on another app, our guide to Uber Eats accident claims covers a similar setup.
What If You Were Walking or on a Bike When a Dasher Hit You?
If you were on foot and a car struck you, Florida PIP can still apply. If you own a car, your own PIP generally covers you. If you are a Florida resident with no car and no PIP of your own, you may claim PIP from the policy covering the car that hit you. Bike and scooter crashes need review.
These rules come from Fla. Stat. 627.736, which extends PIP to people struck by a motor vehicle while they are not riding in a self-propelled vehicle. In plain terms, a pedestrian in a crosswalk near a Tampa restaurant row may still have a PIP claim even without a car.
Cyclists, e-bike riders and scooter riders face harder questions:
- How the “self-propelled vehicle” wording applies to your bike, e-bike or scooter needs a case-specific review.
- Many Dashers in Tampa deliver by bike, e-bike or scooter. DoorDash’s insurance description addresses Dashers using an automobile, so coverage for other Dashers is less clear.
- Your health insurance and any household auto policy may also matter.
People outside a vehicle have the least protection in a crash. Nationally, 639 pedestrians, cyclists and other people outside vehicles were killed in crashes involving distracted drivers in 2024, according to NHTSA’s Distracted Driving in 2024 research note. Those figures cover all drivers, not only delivery drivers.
💡 Did You Know? Florida recorded 8,418 bicycle crashes and 10,306 pedestrian crashes in 2023, statewide. Bicycle crashes rose 15.30% from 2022. Source: Florida Department of Highway Safety and Motor Vehicles, Traffic Crash Facts Annual Report 2023, page 9. FLHSMV notes these figures may change as late reports arrive.
Can You Sue DoorDash, or Only the Driver?
You can bring a claim against the Dasher who caused the crash, and DoorDash’s insurance may be part of that claim. Suing DoorDash directly is harder. DoorDash generally treats Dashers as independent contractors, so any claim against the company itself turns on the specific facts and needs a careful legal review.
A company is not automatically responsible just because its driver was working. Florida courts look at real details, such as how much control a company had over the work. Those questions are fact-heavy, and nobody can answer them from a police report alone.
The facts that usually matter most:
- What the Dasher’s app showed at the moment of the crash
- Who owned the car the Dasher was driving
- What the Dasher’s personal policy says about delivery or business use
- What DoorDash’s policy terms say for Florida
- What evidence shows how the crash happened
If someone else owned the car, Florida’s vehicle owner liability rules may also come into play. For a deeper look at how employee and contractor status affects these claims, read our guide to when you can sue a company if its driver hit you.
One more point clears up a common mix-up. Searching “DoorDash settlement” often turns up news about settlements that have nothing to do with crash injuries. Those payouts do not apply to your accident claim.
What Should You Do in the First Days After a DoorDash Crash?
Get medical care within 14 days, document the scene, and save proof that the driver was delivering. Call the police, photograph the car, any delivery bag or app screen, and your injuries. Then notify your own insurer. Avoid giving a recorded statement to the other side’s insurer until you understand your rights.
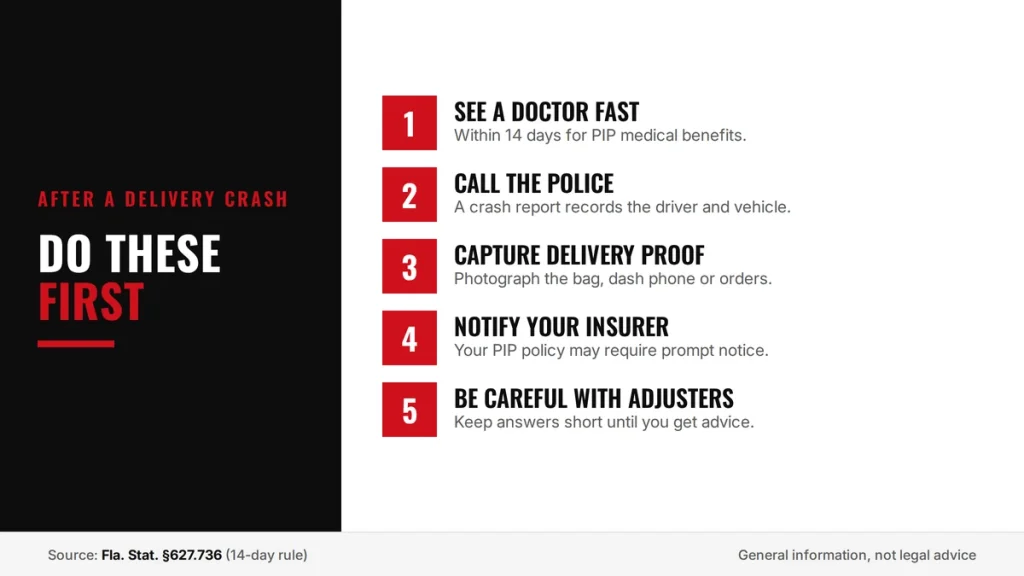 First steps after a crash with a delivery driver. General information, not legal advice.
Here is what helps most, in order:
- See a doctor fast. Go to the ER, urgent care or your doctor. The 14-day PIP rule applies even if you feel fine at first.
- Call the police. A crash report records the driver, the vehicle and what each person said.
- Capture delivery proof. Photograph the DoorDash bag, a phone mounted on the dash, or food orders in the car. Ask the driver if he was on a delivery and write down the answer.
- Get names and policies. Write down the driver’s name, plate, insurer and policy number. Note nearby businesses with cameras.
- Notify your insurer. Your PIP policy may require notice as soon as practicable.
- Be careful with other insurers. Their adjusters work for them. Keep your answers short until you get advice.
If the driver leaves the scene, call 911 right away and write down anything you remember about the car. Hit-and-run crashes are common in Florida. FLHSMV counted 105,092 hit-and-run crashes statewide in 2023 in its Traffic Crash Facts Annual Report 2023.
In a busy Tampa delivery zone, the evidence that proves the driver was working can disappear fast. Restaurant cameras get recorded over. App data sits with DoorDash, not with you. Acting in the first days protects your options later.
⚠️ Warning: Two deadlines you cannot ignore. 14 days for PIP medical benefits. Under Fla. Stat. 627.736(1)(a), you must receive initial medical care within 14 days of the crash to use PIP medical benefits. This is a treatment deadline, not a lawsuit deadline. Two years to file a lawsuit. Under Fla. Stat. 95.11(5)(a), most negligence lawsuits must be filed within two years. This shorter deadline applies to claims arising after March 24, 2023, according to the Florida Senate’s 2023 bill summary. Older claims may fall under the prior four-year rule. Claims involving children or government vehicles can follow different rules, so get advice early.
When Do You Need a DoorDash Accident Lawyer?
Talk to a lawyer when you are hurt, when insurers point at each other, or when the Dasher’s insurer denies coverage because he was delivering. A lawyer also helps when fault is disputed. In Florida, your share of fault reduces what you can recover, and being more than 50% at fault bars recovery.
Hillsborough County roads are busy. In 2023, the county recorded 27,474 crashes, 230 deaths and 18,873 injuries, according to FLHSMV’s Traffic Crash Facts Annual Report 2023. A crash with a delivery driver adds more insurance questions to an already hard situation.
Signs your DoorDash claim needs a lawyer:
- You needed an ER visit, imaging, surgery or ongoing treatment.
- You missed work or cannot do your normal job.
- The Dasher’s insurer denied the claim because of delivery driving.
- DoorDash’s insurer says the app was off or the driver’s policy must pay first.
- The police report or the other driver blames you.
- An adjuster offered a quick settlement before you know how badly you are hurt.
Quick offers deserve extra caution. Once you sign a release, you usually cannot reopen the claim, even if your injuries turn out to be worse. A DoorDash accident lawyer can review every policy that may apply before you sign anything.
For a broader look at these cases, read our guide from a delivery driver accident attorney in Tampa and our article on delivery company insurance limits in Florida.
🛡️ Your Rights Under Florida Law: Shared fault does not always end your claim. Under Fla. Stat. 768.81(2), your own share of fault lowers your damages in proportion, but it does not bar recovery on its own. Under 768.81(6), you cannot recover damages if you are found more than 50% at fault for your own harm. Example: if you are found 20% at fault, your award is reduced by 20%. Fault percentages are decided from the evidence, so an insurer’s first opinion is not the final word.
How The Reyes Firm Handles Your DoorDash Accident Case
Delivery crashes are won or lost on details most people never see. The Reyes Firm, at 4730 N. Habana Ave., Suite 201, Tampa, FL 33614, starts by finding out what the driver’s app showed and which policies may apply. Call us at 833-4 BAD DAY.
Here is how we approach a DoorDash case:
- We investigate the delivery. We work to identify the driver’s app status, the order and the timeline around the crash.
- We find every policy. That includes your PIP, the driver’s personal policy, DoorDash’s coverage and any uninsured motorist coverage you carry.
- We preserve evidence early. We move to secure camera footage, crash reports and records before they disappear.
- We document your injuries. Attorney Edward Reyes worked on the medical side of personal injury before becoming a lawyer, so we know how insurers read medical records and treatment gaps.
- We handle the insurers. You focus on getting better while we deal with adjusters who point at each other.
- We prepare for court when needed. We build each serious case with litigation in mind, so we are ready if a fair settlement does not come.
We are based in Tampa and the South Shore communities, serving Tampa, Riverview, Brandon, Plant City, and communities across Hillsborough County. We offer free consultations in English and Spanish, and you pay no upfront attorney fee.
Frequently Asked Questions About DoorDash Accident Claims
Does DoorDash pay for accidents caused by its drivers?
Sometimes. DoorDash says it provides third-party liability coverage during an active delivery, up to $1,000,000 in most states, and that it may apply after the driver’s own policy. The Florida terms and the driver’s app status decide how it applies to your crash.
What if the DoorDash driver says he was not on an order yet?
That statement does not settle the question. DoorDash’s own pages describe the covered window in slightly different ways, so app records matter. A lawyer can work to get the records that show what the app said at the moment of the crash.
The Dasher’s insurance denied my claim because he was delivering. What now?
That denial is a known gap in delivery cases. DoorDash warns that a Dasher’s personal policy may not cover delivery driving. Your PIP still pays first, and a lawyer can review other coverage that may apply.
I was hit two weeks ago and have not seen a doctor. Is it too late?
You may lose PIP medical benefits if you did not get initial care within 14 days, under Fla. Stat. 627.736. That PIP rule does not erase a claim against the at-fault driver. Get checked now, and keep every record.
Can I still recover if the police report says I was partly at fault?
Often, yes. Under Fla. Stat. 768.81, your share of fault reduces your recovery, but you are barred only if you are found more than 50% at fault. A police report is evidence, not the final decision on fault.
How long do I have to file a claim after a DoorDash crash in Florida?
For most negligence claims arising after March 24, 2023, you generally have two years to file a lawsuit under Fla. Stat. 95.11(5)(a). Wrongful death claims also have a two-year limit. Insurance claims should start much sooner, so do not wait.
Do I need a lawyer if my injuries seem minor?
Not every crash needs a lawyer. But some injuries are not obvious right away, and delivery cases often involve more than one insurer. A free consultation can help you decide.

Edward Reyes, Esq. is the founder and managing attorney of The Reyes Firm, a Tampa personal injury law firm he opened in 2017. Before law school, he worked on the medical side of personal injury as a licensed massage therapist and opened a personal injury clinic that treated thousands of injured patients. Licensed to practice law in Florida, Edward represents people hurt in car, delivery, rideshare and truck crashes across Tampa and Hillsborough County.
How Can The Reyes Firm Help You?
If you’ve had a bad day — a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault — The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.
This article provides general information about Florida law and is not legal advice. Reading it does not create an attorney-client relationship with The Reyes Firm. Insurance terms and laws change, and every case depends on its own facts, so speak with a licensed Florida attorney about your situation.