
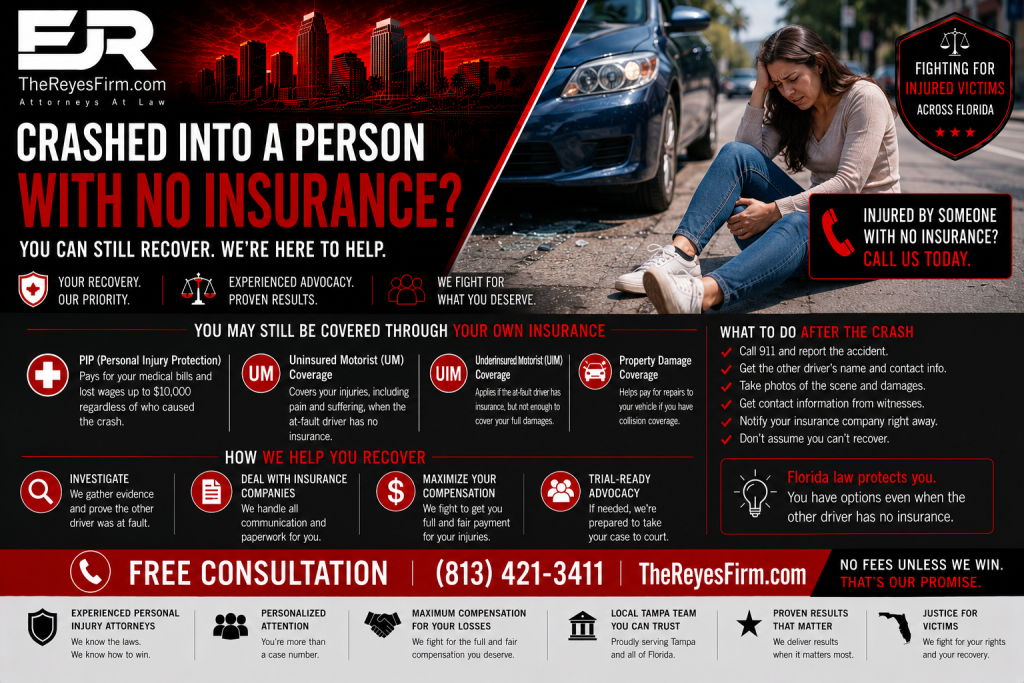
The other driver ran the light, wrecked your car, and left you hurting. Then comes the gut punch: they have no insurance. It feels like you have no way to recover, but in Florida that is often not true. Between your own coverage and the state’s rules, you may have far more protection than you realize after a car accident with an uninsured driver. Here is how it works.
The Reyes Firm
Hit by an Uninsured Driver in Tampa?
You may have more coverage than you think. Let us check. Had a bad day?
Discovering that the person who hurt you carried no insurance is one of the most frustrating moments after a crash. It feels like the responsible party gets to walk away while you are left with the bills. The good news is that Florida’s insurance system was built with this exact problem in mind, and the path to recovery usually runs through coverage you may already have.
What happens if the driver who hit you has no insurance?
You still have options. In Florida, being hit by an uninsured driver does not mean you are out of luck, because your recovery does not depend entirely on the other driver’s insurance. It depends first on your own coverage, which Florida’s no-fault system and uninsured motorist rules are designed to provide.
This matters more here than in most states, because Florida consistently ranks among the states with the highest percentage of uninsured drivers. Being prepared for this situation is not paranoia in Florida, it is simply realistic, and the drivers who come through it best are usually the ones who understand their own policy.
Does Florida’s no-fault system still cover you?
Yes. Florida is a no-fault state, which means your own Personal Injury Protection coverage under Florida Statute § 627.736 pays your medical bills first, regardless of who caused the crash. Because PIP is your own coverage, it applies whether the other driver had insurance or not, as long as you seek initial medical care within 14 days of the crash.
The limitation is that PIP only goes so far. It covers a portion of your medical expenses and lost wages up to a $10,000 cap, and it does not compensate you for pain and suffering. For a serious injury, PIP is a starting point, not the whole answer, which is where uninsured motorist coverage becomes essential.
What is uninsured motorist coverage, and how does it help?
Uninsured motorist coverage, often called UM, is the single most important protection when the at-fault driver has no insurance. It essentially steps into the shoes of that driver’s missing policy and pays for the harm they caused you, including the pain and suffering and the excess medical costs that PIP does not cover. A closely related coverage, underinsured motorist coverage, applies when the at-fault driver has some insurance but not enough to cover your injuries.
There is an important wrinkle worth understanding. When you file a UM claim, you are making a claim against your own insurance company, which means your insurer is now on the other side of your claim. That can feel strange, and it is one reason these claims sometimes become contentious even though you have paid your premiums faithfully.
💡 Did You Know? You may already have uninsured motorist coverage without realizing it. Under Fla. Stat. § 627.727, an insurer generally must offer UM coverage equal to your bodily injury liability limits, and you can only reject it or choose lower limits in writing on an approved form. If you never signed such a rejection, there is a good chance you have this coverage. Source: Fla. Stat. § 627.727.
What if you didn’t think you had uninsured motorist coverage?
Check before you assume the worst. Because Florida law requires insurers to offer UM coverage and to obtain a written rejection if you decline it, many drivers carry this coverage even though they do not remember choosing it. The rejection form itself must carry a bold warning that you are giving up valuable protection, precisely because the state wants drivers to have it.
The practical takeaway is simple: do not give up before someone reviews your actual policy. Pulling your declarations page and reading exactly what coverage you carry is one of the first things worth doing, and a lawyer can do it with you to make sure nothing is missed. What looks like a hopeless situation frequently turns out to be a covered one.
🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible. When the at-fault driver is uninsured, insurers sometimes lean harder on blaming you, and an experienced Tampa injury lawyer works to keep the facts straight and your assigned fault as low as the evidence allows.
Can you sue an uninsured driver personally?
You can, but it is often not the most productive path. A driver who cannot afford insurance frequently cannot afford to pay a judgment either, and a court award means little if there are no assets to collect from. This is the old problem of trying to get blood from a stone, and it is why your own uninsured motorist coverage usually matters far more than a lawsuit against the individual.
That said, an uninsured driver is not always the only responsible party. Sometimes another person or company shares liability, such as an employer if the driver was working, or the owner of the vehicle if someone else let them drive it. Identifying every potentially responsible party is part of what a lawyer does, and it can open doors you would not find on your own.
What about the damage to your car?
Your injuries and your vehicle follow separate tracks. Uninsured motorist coverage in Florida generally addresses bodily injury, not the damage to your car. For the vehicle itself, your own collision coverage can pay to repair it regardless of who was at fault, subject to your deductible, and you may be able to pursue the uninsured driver for that amount separately.
One worry we hear often is whether using your own coverage after a crash you did not cause will raise your rates. Florida law offers real protection on that point, which we cover in detail in our guide to what happens to your rates after a car accident.
⚠️ Deadline Warning: Under Florida Statute § 95.11, you generally have two years from the date of your crash to file a personal injury lawsuit. This was shortened from four years in March 2023. Uninsured motorist claims can carry their own separate notice requirements and policy deadlines too, so the sooner you act, the better protected you are.
Watch: What to Do When the Other Driver Has No Insurance
If this post has an accompanying video, it is included below, walking through your options when the driver who hit you has no insurance.
When you are ready to talk through your own situation, The Reyes Firm offers free consultations with no obligation.
What should you do if you’re hit by an uninsured driver in Tampa?
These five steps protect your health and your claim at the same time. The order matters.
- Get medical care right away. Prompt treatment protects your health and, just as important, keeps your PIP benefits available by meeting Florida’s 14-day requirement.
- Still call the police and document everything. An official crash report, photos, and witness information matter even more when the other driver is uninsured, because your UM claim depends on proving they were at fault.
- Do not admit the other driver “seemed fine” or agree it was minor. Get their information anyway, including any identification, and let the facts be documented rather than assumed at the scene.
- Find and review your own policy. Look for uninsured motorist coverage on your declarations page, and do not assume you lack it until someone confirms that in writing.
- Call The Reyes Firm before dealing with your insurer. A UM claim puts you across from your own insurance company, so having help matters. Call 833-4 BAD DAY for a free consultation.
The Reyes Firm
4730 N. Habana Ave., Suite 201, Tampa, FL 33614
Phone: 833-4 BAD DAY | thereyesfirm.com
How The Reyes Firm handles your uninsured driver case
When the at-fault driver has no insurance, the path to recovery runs through your own coverage and any other responsible parties, and both take real work to pursue. We handle that for you, throughout Tampa and Hillsborough County.
When we take on a case involving an uninsured driver, we typically:
- Review your policy for coverage you may not know you have, including uninsured and underinsured motorist coverage and the PIP benefits that apply regardless of fault
- Handle the claim against your own insurer, since a UM claim makes your insurance company the party you are recovering from, which changes how it must be approached
- Prove the uninsured driver was at fault, gathering the crash report, photos, and witness statements your UM claim depends on
- Look for other responsible parties, such as an employer or a vehicle owner, who may share liability and provide additional coverage
- Protect you from unfair blame, since insurers often push harder on comparative fault when there is no other policy to pay
- Calculate full damages, covering past and future medical care, lost wages, and the pain and suffering that PIP does not address
No lawyer can promise an outcome. What we can promise is that we treat your claim seriously, explain every step in plain language, and fight to reach every source of coverage available to you, including when your injuries are severe enough to be considered catastrophic. You can also read more about what drives the value of a claim in our detailed guide.
Frequently asked questions about uninsured driver crashes in Florida
What happens if the person who hit me has no insurance?
You can still recover through your own coverage. Your PIP pays your initial medical bills regardless of fault, and your uninsured motorist coverage can pay for your injuries, including pain and suffering, that the at-fault driver’s missing policy would have covered.
Does my PIP cover me if the other driver is uninsured?
Yes. Under Fla. Stat. § 627.736, your PIP pays your medical expenses and a portion of lost wages up to $10,000 regardless of who caused the crash, as long as you seek initial care within 14 days. It does not, however, cover pain and suffering.
What is uninsured motorist coverage?
It is coverage on your own policy that pays for injuries caused by a driver who has no insurance, and underinsured motorist coverage applies when the at-fault driver does not have enough. It effectively replaces the coverage the at-fault driver should have carried.
Do I already have uninsured motorist coverage?
You might. Under Fla. Stat. § 627.727, insurers generally must offer UM coverage equal to your bodily injury liability limits, and you can only reject it or select lower limits in writing. If you never signed a written rejection, there is a good chance the coverage is on your policy.
Can I sue an uninsured driver personally?
You can, but it is often not worthwhile, because a driver who cannot afford insurance frequently cannot pay a judgment. Your own uninsured motorist coverage is usually the more reliable path, though other responsible parties may also exist.
Will using my uninsured motorist coverage raise my rates?
Florida law provides protection against being surcharged for an accident that was not your fault. We explain how those rules work in our article on what happens to your rates after a car accident, and a lawyer can help you understand how they apply to your situation.
What about the damage to my car?
Uninsured motorist coverage in Florida generally addresses bodily injury, not property damage. Your own collision coverage can pay to repair your vehicle regardless of fault, subject to your deductible, and you may pursue the uninsured driver for that cost separately.
How long do I have to bring a claim?
The general deadline to file a negligence lawsuit in Florida is two years under Fla. Stat. § 95.11. Uninsured motorist claims can involve their own notice requirements and policy deadlines as well, so it is wise to act quickly and consult a lawyer.

Edward Reyes, Esq. is a Florida Bar-admitted personal injury attorney and the founder of The Reyes Firm in Tampa, Florida. He represents people injured by the negligence of others in cases involving car accidents, uninsured and underinsured motorist claims, and other serious injuries throughout Tampa and the surrounding counties. Edward Reyes, Esq. handles personal injury claims on a contingency fee basis, meaning clients pay nothing unless the firm recovers compensation for them.
Read more about Edward Reyes.
How Can The Reyes Firm Help You?
If you’ve had a bad day, whether a car accident, a slip and fall, a trucking crash, or any injury that wasn’t your fault, The Reyes Firm is in your corner. Our Tampa personal injury attorneys offer free consultations and work on a contingency fee basis, which means you pay us nothing unless we win your case.
You shouldn’t have to fight the insurance companies alone. Let us fight for you.
📍 Address: 4730 N. Habana Ave., Suite 201, Tampa, FL 33614
📞 Phone: 833-4 BAD DAY
🌐 Website: Schedule your free consultation today at thereyesfirm.com
Had a bad day? Call The Reyes Firm. We’ll handle the rest.
The information in this blog post is for general informational purposes only and does not constitute legal advice. Insurance coverage depends on the terms of your specific policy, and the statutes described here contain conditions and exceptions not fully summarized above. Reading this article does not create an attorney-client relationship with The Reyes Firm. Every case is unique. If you have been injured in a crash with an uninsured driver, consult a licensed Florida personal injury attorney about your specific situation.


