After A Car Accident

Tampa Personal Injury Lawyer
After A Car Accident, After an Accident, Body Shops, Car accident, FAQ, florida cities we serve, Legal, Our Community, Personal Injury, personal injury attorney, Why we serve

The Unparalleled Advantages of Hiring a Personal Injury Lawyer Post-Accident

When you find yourself injured due to an unforeseen accident, dealing with the subsequent challenges can be daunting. Insurance companies, medical bills, and legal systems can be overwhelming, particularly when you are trying to recover. This is where a personal injury lawyer can prove to be your best ally, navigating you through these tumultuous waters. Introduction to Personal Injury Lawyer A Personal Injury Lawyer is a legal professional who provides representation to those who claim to have been injured, either physically or psychologically, as a result of the negligence of another person, company, government agency, or any entity. They specialize in an area known as tort law, which includes private or civil wrongs or injuries, including defamation and actions for bad faith breach of contract. Expert Legal Assistance Accidents come unannounced, leaving you in situations you are mostly unprepared for. A personal injury lawyer can provide expert legal assistance, helping you understand the complexities of the law and making the legal process much more manageable. Their extensive knowledge of law ensures that you can avoid common pitfalls and receive the compensation you deserve. Professional Assessment of Damages An accurate assessment of damages is crucial in personal injury cases. Lawyers possess the experience and insight to evaluate all aspects of the injury and its repercussions. They consider not only immediate medical expenses but also long-term medical costs, loss of earnings, and emotional distress, ensuring that the compensation claimed is comprehensive and just. Negotiation Skills When dealing with insurance companies, negotiation is crucial. A personal injury lawyer acts as your advocate, leveraging their skills to ensure that you receive a fair settlement. Their ability to negotiate effectively with insurance adjusters and opposing counsel can significantly increase your compensation, maximizing the value of your claim. Stress Reduction Facing an accident is stressful enough, let alone dealing with insurance and legal proceedings. Having a personal injury lawyer to handle these aspects can alleviate significant stress, allowing you to focus on recovery. They deal with the bureaucracy, paperwork, and legal communications, shielding you from the unnecessary burden. Court Representation If negotiations fail, a personal injury lawyer can take your case to court. They can handle every aspect of the trial, presenting your case in the most compelling way possible, increasing the likelihood of a favorable judgment. Their extensive experience in litigation ensures that your rights are protected and your case is properly presented. Time-saving Navigating the legal landscape can be time-consuming. Hiring a personal injury lawyer means less time wasted on legal procedures and more time focused on your well-being and recovery. From gathering evidence to consulting with medical experts, your attorney will manage every detail efficiently. Improved Chances of High Compensation Lawyers understand the subtleties of personal injury law and use this knowledge to secure the best possible compensation for your injuries. By establishing the negligence of the responsible party and proving the extent of the damages, they can substantially increase the amount of compensation you receive. Ethical and Objective Support Personal injury lawyers provide objective and ethical support when emotions are high. Their professional standpoint allows them to present the facts of the case without bias, ensuring that your injury’s true impact is understood and considered. Securing Your Rights and Well-being In the aftermath of an accident, a personal injury lawyer is an indispensable asset, securing your rights and representing your interests. They navigate the intricacies of the legal system, negotiate with insurance companies, and ensure that you receive the compensation you deserve. With their expertise, you can rest assured that every aspect of your claim is being handled professionally and efficiently, allowing you to focus on your recovery and well-being. So, if you find yourself a victim of an accident, seeking the services of a personal injury lawyer should be your foremost priority. Remember, it’s crucial to select an experienced and knowledgeable personal injury lawyer, considering their specialization, experience, and track record, to ensure optimal representation and outcome in your case. If you or a loved one has been injured in an accident due to someone else’s negligence, do not hesitate to consult with a qualified personal injury lawyer immediately. Secure your rights and get the compensation you rightly deserve. Find the best legal representation now!
Uninsured motorist coverage in Tampa
Accident Injuries & why, After A Car Accident, Blog, FAQ, Uninsured Motorist Coverage

Why It’s Essential to Have Uninsured Motorist Coverage in Tampa, Florida

Picture this: you’re driving down Bayshore Boulevard, doing everything right, when another driver runs a light and slams into you. You’re hurt, your car is wrecked, and then you learn the driver who hit you has no insurance at all. In Florida, that nightmare is far more common than most people realize, and whether you walk away financially protected often comes down to one line on your own policy. Here’s why uninsured motorist coverage may be the most important coverage you can carry after a Tampa car accident. TL;DR — QUICK SUMMARY Florida has one of the highest rates of uninsured drivers in the country, with an estimated one in five drivers carrying no insurance at all. Florida does not require most drivers to carry bodily injury liability coverage, so even an insured driver may have nothing to pay for the injuries they cause you. Uninsured and underinsured motorist (UM/UIM) coverage steps in to pay your medical bills beyond PIP, your lost wages, and your pain and suffering. Under Florida Statute 627.727, your insurer must offer you UM coverage, and settling with the at-fault driver without your UM carrier’s consent can wipe out that coverage. UM even covers hit-and-run and phantom-vehicle crashes, and you generally have two years to file an injury claim under Florida Statute 95.11(3)(a). The Reyes Firm Hit by an Uninsured Driver in Tampa? Find out if your own coverage can pay your claim. Had a bad day? Contact Us Now 1 in 5 Florida drivers are uninsured Insurance Research Council $0 Bodily injury coverage Florida requires of drivers Florida law Must Offer Insurers must offer you UM coverage Fla. Stat. 627.727 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) Why is uninsured motorist coverage so important in Florida? Uninsured motorist coverage is so important in Florida because two facts collide on our roads: a large share of drivers carry no insurance, and state law does not require most drivers to carry coverage for the injuries they cause. An estimated one in five Florida drivers has no auto insurance at all, one of the highest rates in the nation according to the Insurance Research Council, and Tampa’s heavy traffic and steady stream of out-of-town drivers only raise the odds of being hit by one. Here is the part that surprises people most. Florida requires drivers to carry Personal Injury Protection and property damage coverage, but it does not require them to carry bodily injury liability coverage, which is the coverage that would pay for your medical bills and pain after a crash they caused. That means even a driver who is following the law may have nothing available to compensate you, and your own uninsured motorist coverage becomes your safety net. What is the difference between uninsured and underinsured motorist coverage? The two go hand in hand but apply in different situations. Uninsured motorist (UM) coverage applies when the driver who hit you has no bodily injury liability insurance at all, or cannot be identified, as in a hit-and-run. Underinsured motorist (UIM) coverage applies when the at-fault driver does have liability insurance, but not enough to cover the full extent of your injuries. In Florida, the two are usually sold together as a single UM/UIM coverage, and both draw from your own policy. The practical point is the same in either case: when the other driver cannot make you whole, this coverage is what stands between you and paying for someone else’s mistake out of your own pocket. How does UM coverage fill the gap left by Florida’s no-fault system? Florida’s no-fault system gives you some protection, but not nearly enough for a serious injury. Your Personal Injury Protection coverage pays 80% of your medical bills and 60% of your lost wages, but only up to a standard limit of $10,000, and it pays nothing at all for pain and suffering. A trip to the emergency room and a single surgery can blow through that $10,000 in days. Uninsured motorist coverage picks up where PIP stops. It can pay your medical expenses beyond the PIP limit, your lost wages and reduced earning capacity, and your pain and suffering, and it protects not just you but the relatives in your household and the passengers in your car. It is especially vital for motorcycle riders, who are not covered by PIP at all and depend heavily on UM coverage when an uninsured driver hits them. đź’ˇ Did You Know? Florida is a no-fault state that requires only $10,000 in PIP and $10,000 in property damage coverage, and it does not require most drivers to carry bodily injury liability at all. With an estimated one in five Florida drivers uninsured, your own uninsured motorist coverage is often the only source that will pay for your injuries, lost wages, and pain and suffering. Source: Insurance Research Council; Fla. Stat. § 627.736. Watch: Why you need uninsured motorist coverage in Tampa In this short video, attorney Edward Reyes explains how uninsured motorist coverage works and how it can protect you when the driver who hit you cannot pay. If you were hit by an uninsured driver, The Reyes Firm offers free consultations and can review your coverage at no cost. Does UM coverage protect you in a hit-and-run or no-contact crash? Yes, and this is one of its most valuable features. If a driver hits you and flees, or if a phantom vehicle runs you off the road without ever making contact, there may be no at-fault driver to identify and no liability insurance to pursue. Uninsured motorist coverage is built for exactly these situations and can pay for your injuries when the other driver vanishes. These claims do come with conditions, often including a requirement to corroborate that another vehicle caused the crash, which makes fast evidence-gathering critical. In the most tragic hit-and-run cases, where a family loses a loved one, UM coverage can also support a wrongful death claim when the driver is never found. ⚠️ Deadline

Know your rights probable cause explained
After A Car Accident, DUI/DWI, Legal

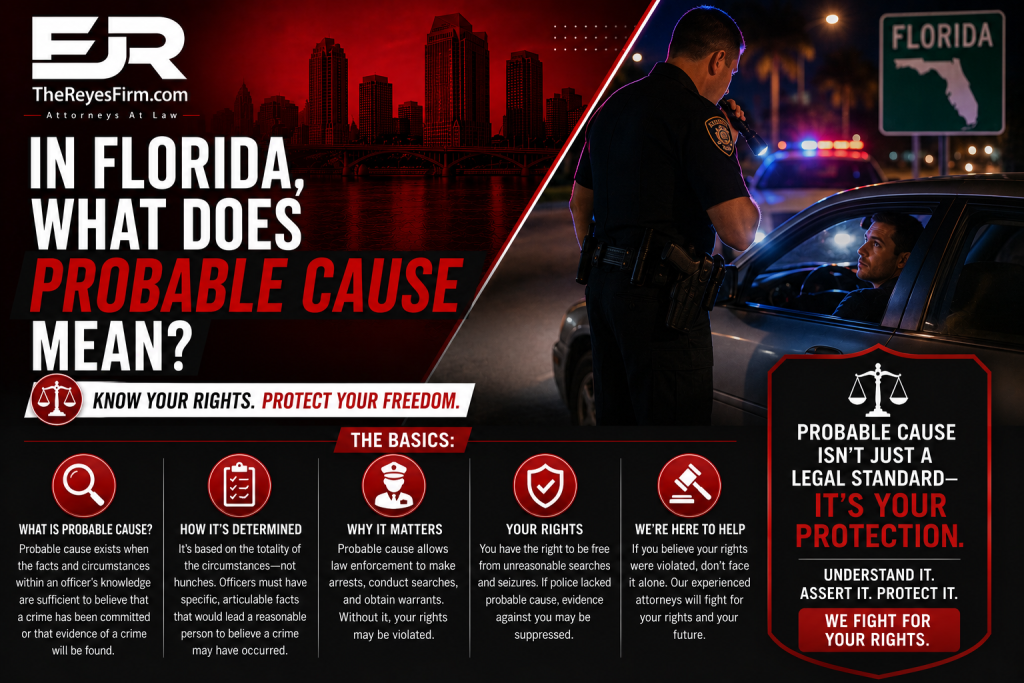
In Florida, What Does Probable Cause Mean?

You were hurt in a car accident that wasn’t your fault. The other driver got cited, maybe even arrested for DUI, and an officer mentioned “probable cause.” Now you’re wondering what that phrase actually means for you, and whether it helps your injury claim. Here’s what probable cause is, and how it can shape what you recover. TL;DR — QUICK SUMMARY Probable cause is the legal standard police need to arrest someone or get a warrant: a reasonable, fact-based belief that a crime occurred, not just a hunch. After a crash, an officer with probable cause can cite or arrest the at-fault driver, including for DUI, which can support your injury claim. A ticket alone does not automatically prove fault, and Florida’s accident report privilege keeps the crash report itself out of civil court. The evidence behind the arrest, like breath or blood test results, independent witnesses, and physical evidence, often can be used, and a DUI conviction generally can too. A DUI or other reckless conduct may open the door to punitive damages on top of your regular compensation. The Reyes Firm Hurt by a Cited or Arrested Driver in Tampa? Find out how the other driver’s citation or DUI affects your claim. Had a bad day? Contact Us Now 0.08% Florida legal BAC limit Fla. Stat. § 316.193 2 Years Deadline to file an injury claim Fla. Stat. § 95.11(3)(a) Privileged Crash report in civil court Fla. Stat. § 316.066(4) $0 Upfront cost on contingency Pay nothing unless you recover What does probable cause mean in Florida? Probable cause is the legal standard police must meet before they can arrest someone or obtain a warrant to search or seize. It means there are enough facts and circumstances for a reasonable person to believe a crime has been committed. It’s more than a hunch or a gut feeling, but less than the “beyond a reasonable doubt” proof needed to convict someone at trial. The protection comes from the Fourth Amendment, which guards against unreasonable searches and seizures. In plain terms, an officer generally can’t arrest a driver or search a vehicle on a whim. They need a reasonable, fact-based justification. After a car accident, that standard is exactly what an officer relies on when deciding whether to cite or arrest the driver who hurt you. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your crash to file a personal injury lawsuit, even if the other driver is facing criminal charges. The criminal case and your civil claim are separate. Don’t wait on one to protect the other. How does probable cause come up after a car accident? It comes up the moment an officer responds to your crash and starts piecing together what happened. If the facts give the officer probable cause that the other driver broke the law, the officer can issue a citation or make an arrest. This is most common in serious cases: running a red light, reckless driving, or driving under the influence. DUI is the clearest example. To arrest a driver for DUI, an officer needs probable cause, often built from observations like erratic driving, the smell of alcohol, slurred speech, or field sobriety results. When that arrest happens after a crash that injured you, it can become an important part of your civil case. A serious or catastrophic crash caused by an impaired driver is exactly the kind of case where these details matter. Does a ticket or arrest of the other driver prove they were at fault for my injuries? Not by itself. This is where many people get the wrong impression. A traffic citation is not automatic proof of fault, and you are not bound by an officer’s findings, which can be incomplete or simply wrong. On top of that, Florida’s accident report privilege under Fla. Stat. § 316.066(4) keeps the crash report itself, and the statements drivers make to the officer for that report, out of evidence in civil court. So what actually helps your case? The evidence underneath the arrest. Breath, blood, and urine test results are not covered by the privilege and can be admissible. Independent witnesses who weren’t involved in the crash can testify. Physical evidence like skid marks, vehicle damage, and scene photos can be used. And if the at-fault driver is convicted, that conviction generally can come into your civil case. The arrest is a signpost. The admissible evidence behind it is what carries weight. đź’ˇ Did You Know? Under Fla. Stat. § 316.066(4), the crash report and the statements you make to the officer for it generally can’t be used as evidence in a civil or criminal trial. But chemical test results, independent witness accounts, and physical evidence from the scene are not shielded by the privilege, which is why a thorough independent investigation matters so much. Source: Fla. Stat. § 316.066(4). How can a DUI arrest affect my injury claim? A DUI arrest can strengthen your case in a real way. Your civil injury claim is separate from the criminal case and uses a lower standard of proof. A criminal conviction requires proof beyond a reasonable doubt, while your civil claim only requires showing the other driver was more likely than not negligent. That means you can win compensation even if the criminal case resolves differently than you’d expect. There’s another important consequence. When a driver causes a crash through drunk driving or similarly reckless conduct, Florida law may allow punitive damages, which are meant to punish and deter, on top of compensation for your medical bills, lost wages, and pain. Not every case qualifies, but impaired driving is one of the situations where that possibility is real. When a drunk driver causes a death, our Tampa wrongful death attorneys handle those claims with particular care. What if the police blamed me or gave me a citation too? A citation against you is not the end of your claim. Just as the other

Know your case, know your value
After A Car Accident, Health, Legal, Migraines, Personal Injury, personal injury attorney, Settlement, Traumatic injury

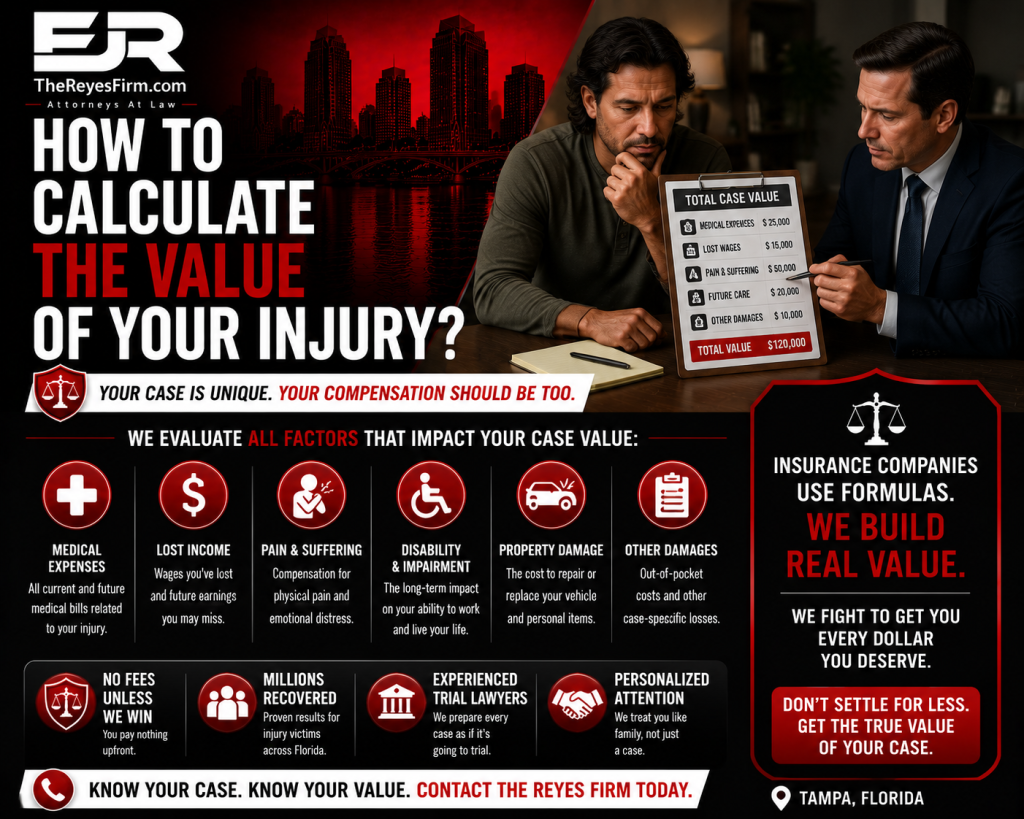
How To Calculate The Value of Your Injury?

After a serious Tampa accident, one question outweighs almost every other: how much is my case actually worth? Put a number too high and the insurer stops taking you seriously. Settle for too little and you are stuck paying for an injury that was never your fault. Here’s how the value of an injury claim is really calculated in Florida, and what quietly raises or lowers that number. TL;DR — QUICK SUMMARY Your claim’s value is the sum of your economic damages and your non-economic damages, then adjusted for your share of fault and the available insurance. Economic damages are documentable losses like medical bills, lost wages, and future care; non-economic damages cover pain, suffering, and lost quality of life. Most insurers start with the multiplier method, adding up your medical bills and multiplying by a number, usually between 1.5 and 5, based on how serious your injury is. In Florida you can only recover pain and suffering from an at-fault driver if your injury meets the permanency threshold under Florida Statute 627.737. Comparative fault and insurance policy limits can shrink what you actually collect, and you have two years to file under Florida Statute 95.11(3)(a). The Reyes Firm Wondering What Your Case Is Worth? Get an honest valuation of your Tampa injury claim. Had a bad day? Contact Us Now 1.5 to 5 Common multiplier applied to your damages Industry standard No Cap On pain and suffering in most FL injury cases Florida law >50% Your fault share that bars recovery Fla. Stat. 768.81 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) How do you calculate the value of a personal injury claim? You calculate the value of an injury claim by adding together two kinds of damages, your economic losses and your non-economic losses, and then adjusting that total for real-world factors like your share of fault and the insurance coverage available. There is no single official formula a court hands you, but insurance companies and experienced attorneys both start from a recognized method and refine it based on the facts of your case. The goal of these damages is to make you whole, meaning to put you back, as much as money can, in the position you would have been in if the injury had never happened. Getting the number right matters in both directions. Aim too high and the insurer assumes you are not serious about settling. Accept too little and you are left covering costs that should have been someone else’s responsibility. What are economic, or special, damages? Economic damages are the losses you can put a receipt to. They include your past and future medical bills, your lost wages, your reduced earning capacity if you cannot work the way you used to, the property damage to your vehicle, and out-of-pocket costs like medication and travel to appointments. In a Florida auto case, your own Personal Injury Protection coverage pays the first portion of these medical bills before you pursue the at-fault party for the rest. The piece people most often undervalue is the future. A catastrophic injury can require surgeries, therapy, and care for years or even a lifetime, and all of that belongs in your claim. Counting only the bills you have already received is one of the fastest ways to settle for far less than your case is worth. What are non-economic, or general, damages? Non-economic damages compensate you for harm that has no invoice: physical pain, mental anguish, the loss of enjoyment of your life, disfigurement, and the strain an injury puts on your relationships. These losses are real, but because they are subjective, they are the hardest part of a claim to value and the part insurers fight the most. In Florida there is an important gate. You can only recover non-economic damages from an at-fault driver if your injury meets the permanency threshold under Florida Statute § 627.737, which generally requires a permanent injury such as a spinal cord injury or a traumatic brain injury. The good news is that Florida does not cap pain and suffering in typical injury cases, so when the threshold is met, the value of these damages is limited by the evidence, not by an arbitrary ceiling. đź’ˇ Did You Know? In a Florida car accident, you cannot recover pain and suffering from the at-fault driver unless your injury meets the permanency threshold in Fla. Stat. § 627.737. When it does, Florida places no cap on non-economic damages in ordinary injury cases, so the value is driven by the strength of your medical evidence. Source: Fla. Stat. § 627.737, leg.state.fl.us. How does the multiplier method work? The multiplier method is the most common starting point for valuing pain and suffering. An adjuster or attorney adds up your economic damages, focusing on your medical bills, and multiplies that total by a number, usually between 1.5 and 5. A minor injury with a full recovery sits near the bottom of that range, while a severe, permanent injury sits near the top, and the result is an estimate of your non-economic damages that gets added to your economic losses. A second approach, the per diem method, assigns a set dollar amount for each day you live with your injury, which works better for shorter-term injuries than for lifelong ones. Both are only starting points. This is also why the free calculators you find online are unreliable, because they cannot weigh permanency, fault, your future prognosis, or the specific facts that move the multiplier up or down. Watch: How injury value is calculated In this short video, attorney Edward Reyes breaks down how the value of an injury claim is calculated and the mistakes that leave money on the table. If you want a clear, honest read on what your case is worth, The Reyes Firm offers free consultations at no cost to you. How do fault and insurance limits change what you actually collect? Two factors can separate what your claim is worth from

Settle your case privately today
Accident Injuries & why, After A Car Accident, Legal, personal injury attorney, Settlement, Why we serve

Can you settle your case privately?

You finally got the call. The car accident case settled, and a check is coming. Now you’re wondering who has to know, and whether anyone can take a piece of it. Here’s the truth about settling your injury case privately in Florida, and the liens that don’t disappear just because the deal is quiet. TL;DR — QUICK SUMMARY Most Florida personal injury cases settle before a lawsuit is ever filed, which means there’s no public court record of the payout. A “private” settlement usually means two things: it’s resolved pre-suit, and the agreement includes a confidentiality clause. Private does not mean untouchable. Liens for medical care, health insurance, Medicare, Medicaid, and even past-due child support can still attach to your settlement. Government liens like Medicare and Medicaid generally must be paid first, and they’re protected by federal and Florida law. Most liens are negotiable. An attorney identifies them, fights to reduce them, and resolves them before your money is disbursed. The Reyes Firm Worried About Who Gets a Cut of Your Settlement? Get clear answers about liens, confidentiality, and your net recovery. Had a bad day? Contact Us Now Pre-Suit Stage where most cases resolve No public court record Confidential Common private settlement clause Settlement agreement term Paid First Priority for Medicare & Medicaid Federal & Fla. law 2 Years Florida deadline to file a claim Fla. Stat. § 95.11(3)(a) What does it mean to settle your case privately? Settling privately usually means two things. First, your case resolves before anyone files a lawsuit, so there’s no public court file documenting the amount you received. Second, the settlement agreement often includes a confidentiality clause that legally bars both sides from disclosing the terms. Put together, that’s what most people mean when they ask about a “private” settlement: a quiet, pre-suit resolution that doesn’t end up in the public record. This is the most common way personal injury cases end. The vast majority settle in the pre-suit phase, before a complaint is ever filed in court. The upside is real. You avoid the time, stress, and public exposure of litigation, and there’s no court docket broadcasting what you were paid. Can you settle a personal injury case without going to court in Florida? Yes. You absolutely can settle without going to court, and most people do. A claim can be negotiated and resolved directly with the at-fault party’s insurance company, and a signed settlement and release ends the matter without a judge, a courtroom, or a public trial. That said, there’s a catch worth understanding. Settling pre-suit only works if both sides reach an agreement before your filing deadline runs out. If negotiations stall and your time is running low, the only way to protect your claim is to file the lawsuit. You can read more about that clock in our guide to Florida’s statute of limitations, but the short version is this: don’t let a slow private negotiation quietly run out your right to sue. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your injury to file a lawsuit. Private settlement talks do not pause this clock. If a deal isn’t done in time, you must file suit to protect your claim. Don’t wait to call a lawyer. Does a private settlement stay completely secret? Not entirely, and this is where people get caught off guard. A confidentiality clause keeps the terms private between you and the other side, but it does not erase legal obligations attached to your money. If someone has a valid legal claim against your settlement, called a lien, that claim survives no matter how quiet the deal is. So while your neighbor or your coworkers won’t find out what you were paid, certain parties with a legal right to repayment can. The most common are healthcare providers, health insurers, government programs, and, in some cases, an agency collecting past-due child support. A private settlement protects your privacy. It does not protect you from obligations the law says you owe. Watch: How private settlements really work This short video walks through what a private settlement means and how liens can affect what you actually take home. Have a question the video didn’t cover? The Reyes Firm offers a free case review so you understand your settlement before you sign anything. What liens can attach to your injury settlement? A lien is a legal right to claim money from your settlement before it reaches your pocket. Several types can apply at once, and they’re paid in a specific order. The most common liens in Florida injury cases include: Medical and hospital liens. Providers who treated you, including hospitals and ambulance companies, can secure a lien for their bills, sometimes under Florida statutes and sometimes by contract when you signed intake paperwork. Letters of protection. If a doctor agreed to treat you and wait for payment until your case resolved, that agreement is a contractual lien paid out of your settlement. Health insurance subrogation. If your private health insurer paid accident-related bills, it may have a right to be reimbursed from your recovery. Medicare and Medicaid. Federal and Florida law require these programs to be repaid for accident-related care. Government liens like these generally get paid first. Child support. If you’re behind on child support, the obligation can attach to your settlement, which we’ll cover in detail below. Here’s the good news that often gets lost: most of these liens are negotiable. An experienced attorney requests itemized documentation, challenges inflated or unreasonable charges, and works to reduce what comes out of your settlement, so you keep as much of your recovery as possible. đź’ˇ Did You Know? Under the federal Medicare Secondary Payer Act, Medicare must be repaid for accident-related care out of your settlement, and failing to handle it correctly can lead to penalties or collections. A smart settlement plan often holds funds in trust until the final lien amount is confirmed, so your check doesn’t get

Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Family Law, FAQ, For Parents, For Teens, Injury, Legal, Why we serve

Can you sue your own mom in a car accident?

Personal injury attorney in Tampa, Edward Reyes talks about cases if you can sue you own mother for claiming against you in a car accident. Can you sue your mom for claiming issue you in a car accident? It may sounds bad but YES! You can sue your mom in case you got into a car accident.This sounds pretty bad, but we’ve seen it many times. It goes both ways.This sounds pretty bad, but we’ve seen it many times. It goes both ways, where you sure your mom or your mom sues you. You cant live in the same household. Your mom lives in household A and you live in household C. If you live in the same household, you are consider resident relatives. Regardless if you’re relatives or not. You can settle as relatives because you live are residing together. If you live in a different household as your mom and as long as you completely different insurance policies then you can make make a claim against her. Lets say you are in car with your mom, and your mom decides to hit somebody else. If you want to, you can claim against your mom because you are a passenger of her bad driving. It works both ways. If she’s in your car and you hit somebody, your mom can claim against you for your negligent driving. So can you sue your mom? The answer is YES. Watch this video for the full details if you can sue your mom for her bad driving.

After A Car Accident, After an Accident, FAQ, For Parents, For Teens, Health, Injury, Legal, Migraines, Traumatic injury, Why we serve

How accidents cause Depression, PTSD, Coping and mental health issues?

Personal injury attorney in Tampa, Edward Reyes talks about depression, post traumatic stress, mental health and how it relates to accidents. We see depression from people that are exposed in extreme trauma. Sometimes it is mistakenly attributed as marital issues, increased intake of alcohol, or family problem. We have to treat auto-accidents as a grieving process and a loss. We are not just talking about losing a loved one but also includes the loss of your job or the loss of your finances and in some ways are taking out of their role if there’s a significant injury then mental stress should be addressed too. If it disrupts you day to day activities, there’s stress that you need to cope with because we are creatures of habit. Watch this video for the full details about coping with Post Traumatic Stress Disorder caused by car accidents.

Accident insurance guide and legal help
After A Car Accident, Settlement

What Not to Say to an Insurance Adjuster After a Car Accident in Florida

The Reyes Firm Insurance Adjuster Calling After a Crash? Do not give a recorded statement before you understand your rights. Had a bad day? Contact Us Now Should You Talk to an Insurance Adjuster After a Car Accident in Florida? After a crash, the phone may ring before you have even had time to process what happened. The caller may say they are an insurance adjuster and only want to “get your side of the story.” They may sound friendly. They may say the call is routine. They may ask if they can record you. Be careful. Knowing what not to say to an insurance adjuster after a car accident in Florida can protect your injury claim, your right to compensation, and your ability to respond if the insurance company later tries to blame you. The safest answer is this: you can report basic facts, but you should not provide a detailed statement, a recorded statement, a medical opinion, an apology, or an explanation of fault before speaking with a Florida personal injury attorney. This is especially important in Tampa and across Hillsborough County, where crash victims may be dealing with busy roads, commercial vehicles, uninsured drivers, rideshare vehicles, and multiple insurance companies. Why Does the Insurance Adjuster Call You So Fast After a Crash? Insurance adjusters often contact crash victims quickly because early statements can be valuable to the insurance company. Right after a crash, you may be scared, in pain, confused, or still trying to understand what happened. You may not know the full extent of your injuries yet. You may not have seen the police report, photos, witness statements, or medical records. That creates risk. An adjuster may listen for statements such as: “I’m fine.” “I didn’t see them.” “I’m sorry.” “It happened so fast.” “I might have been going a little over the speed limit.” “I think I’m okay.” “I just want this to be over.” Even if you are only trying to be polite, those statements can later be used to question your injuries, your credibility, or your share of fault. Many serious injuries do not fully appear right away. Back injuries, neck injuries, concussions, herniated discs, and soft tissue injuries can become more painful in the days after a crash. That is why it is safer to avoid giving injury details until you have been medically evaluated. ⚠️ Important Florida Deadline: For many negligence claims in Florida, the statute of limitations is now two years. Florida Statute § 95.11(5)(a) lists a two-year deadline for an action founded on negligence. This deadline is separate from your insurance claim. Waiting too long can put your right to file a lawsuit at risk. Speak with a Florida personal injury attorney as soon as possible after a crash. What Is the Difference Between Your Insurance Adjuster and the Other Driver’s Adjuster? Not all insurance adjusters have the same role. After a Florida car accident, you may hear from two different types of adjusters. First-party insurance adjuster A first-party adjuster works for your own insurance company. You may need to notify your insurer about the crash because your policy likely includes a cooperation clause. This does not mean you should give unlimited statements, guesses, or detailed injury explanations before speaking with a lawyer. It means you should report the crash and provide basic information. Third-party insurance adjuster A third-party adjuster works for the other driver’s insurance company. That company does not represent you. It represents the person or business that may be responsible for your injuries. You generally do not have to give the other driver’s insurance company a recorded statement. You can politely decline and tell them your attorney will handle communications. A simple response is: “I am not giving a recorded statement. Please contact my attorney.” Then end the call. Watch: Should You Speak to an Insurance Adjuster After a Car Accident? In this short video, The Reyes Firm explains when you should avoid speaking to the other driver’s insurance company, when you may need to communicate with your own insurer, and why having an attorney involved can help protect your claim. Key takeaway: You generally should not discuss the accident or your injuries with the other driver’s insurance company. If your own insurance company needs information, keep the conversation focused and consider having an attorney present for any recorded statement. Do You Have to Talk to the Other Driver’s Insurance Company in Florida? No. You generally do not have a legal obligation to give a recorded statement to the other driver’s insurance company after a Florida crash. The other driver’s insurer may call repeatedly. They may suggest that your claim cannot move forward unless you speak with them. They may ask for permission to record the call. They may ask you to explain how the accident happened. You do not have to help them build a defense against your claim. You can provide basic identifying information if needed, but you should not: Explain fault Guess what happened Describe your injuries in detail Agree to a recorded statement Sign a broad medical release Accept a settlement before knowing the full value of your claim If the other driver’s insurance company contacts you, the safest step is to speak with a lawyer first. 💡 Did You Know? Florida drivers often face insurance coverage issues after a crash. Some drivers may have limited coverage, no available bodily injury coverage, or no insurance at all. If the at-fault driver is uninsured or underinsured, your own policy may become important. That is one reason to be careful when speaking with any insurance company, including your own. Why Do Insurance Adjusters Ask for Recorded Statements? Insurance adjusters ask for recorded statements because they create a permanent version of your story. Once you give a recorded statement, the insurance company can compare it against: The police report Medical records Photos and video Witness statements Later deposition testimony Social media posts Repair estimates Prior medical history Even small inconsistencies can be used to

After A Car Accident, After an Accident, Car accident, Legal, Police Interaction, Settlement, Why we serve

When You’re Involved In a Car Accident, Always Get a Police Report

Personal injury attorney in Tampa, Edward Reyes discusses what are the roles of law enforcement officers at the scene of the accident. The reason why you want to call the officers is for documentation. They are there to hear both sides of the story. They will compare your side and the other person’s side. They will then look at the surrounding areas to see if there’s a stop sign, red light, the damages where the car has landed, and a whole bunch of different things to document the case. You need it because even though a police report is not admissible in court, it helps a lot before you even get to court. If the law enforcement officer does not show up, the other person may change his/her story and now the insurance company that should have covered the damages of your car and your injury is not going to pay for it because their client told them that they are not at fault. It’s a wise idea to document everything, take a lot of pictures, and make sure to call the police. This is to make sure that they have all the facts put together in a nice report. If there’s injuries, there’s got to be a long form. By doing this, it will save you months in filing lawsuit against somebody when you could’ve just spent 30-40 minutes for the law enforcement officer to show up to write the report the way it should be written. Watch this video for the full details.

Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Legal, personal injury attorney, Settlement, Why we serve

What NOT to say to the insurance companies

[vc_row][vc_column][vc_column_text]Personal injury attorney in Tampa, Edward Reyes discusses what you shouldn’t disclose to your insurance company in case you got involved in a car accident. Sometimes when you got involved in a car accident, you want to be nice to there person. Like saying “It wasn’t that bad”, “It’s okay”, or “I’ll be alright”. Then days later you start feeling pain and you have do something like getting checked or be hospitalized. You will then realize that the insurance company is not so nice. They’ll say you’re lying or trying to milk the system. They’ll say a lot of other things to discredit your claim. Watch this video for the full details. [/vc_column_text][/vc_column][/vc_row]

Scroll to Top