Uninsured Motorist Coverage

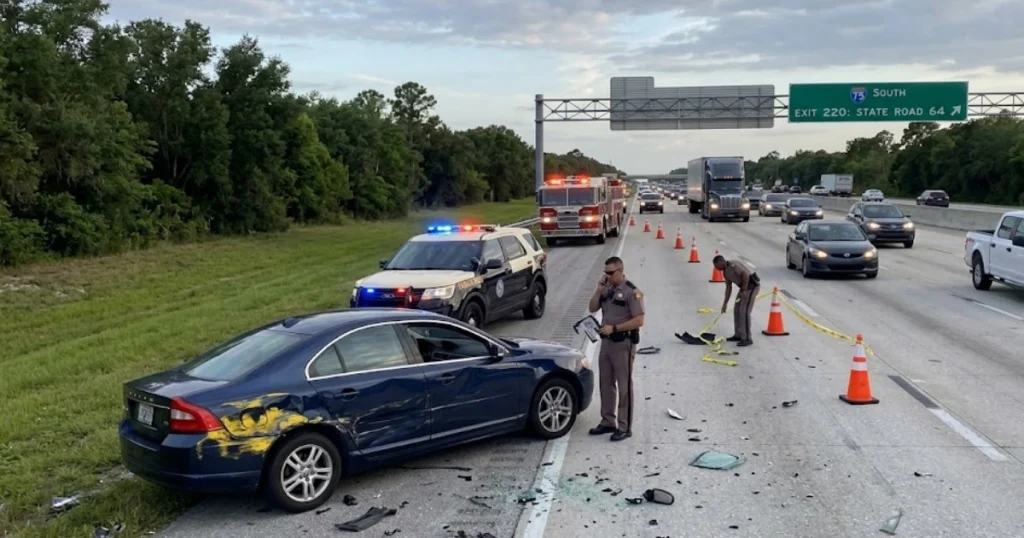
I-75 southbound near State Road 64 in Manatee County Florida following hit-and-run crash, for illustrative purposes only
Blog, Commercial Vehicles, News, Uninsured Motorist Coverage, Wrongful Death

Deadly I-75 Hit-and-Run in Manatee County: 5 Critical Rights Florida Victims Must Know Now

Hit by a driver who fled on I-75 in Manatee County? Learn your rights after a hit-and-run crash in Florida. A truck driver left for work before sunrise on a Monday morning and never came home. A vehicle weaving through southbound I-75 traffic near State Road 64 in Manatee County clipped another car, sending it into the path of a fully loaded semi. The semi overturned across all three southbound lanes. The driver died at the scene. He left behind four children. The person who caused it stopped for a moment. Then fled. If you lost someone in a crash like this, or you were hurt and the driver ran, you’re probably asking the same question every hit-and-run victim asks: “What can I actually do if they ran?” The answer, under Florida law, is more than you think. This article walks you through exactly what your rights are after an I-75 hit-and-run crash in Manatee County or anywhere in Florida, and what steps to take right now. Quick Summary A fatal hit-and-run on I-75 near State Road 64 in Manatee County killed a truck driver and father of four after the at-fault driver fled the scene. Florida law makes leaving a deadly crash scene a first-degree felony with up to 30 years in prison under Florida Statute 316.027. Even if the driver who fled is never found, you can still recover through your own uninsured motorist policy under Florida Statute 627.727. Florida recorded 97,902 hit-and-run crashes in 2024, and nearly 25% of all crashes involve a driver who flees. You are not alone in this. The Reyes Firm fights for hit-and-run victims across Tampa, Manatee County, and communities throughout Hillsborough County and South Florida. Had a bad day? Call 833-4 BAD DAY. Where Did the I-75 Hit-and-Run Crash Happen in Manatee County? The crash was reported on southbound I-75 near State Road 64 in Manatee County, Florida. The map below shows the approximate area for reader context only. Map note: Approximate location of the fatal hit-and-run crash on I-75 near SR-64 in Manatee County, Florida. For illustrative purposes only and not a precise crash-scene marker. What Happened on I-75 in Manatee County, and Why Does It Matter for Your Case? A vehicle was weaving aggressively through southbound I-75 traffic near State Road 64 in Manatee County when it struck another car. That impact forced the second vehicle into the path of a fully loaded semi-tractor-trailer. The semi overturned across all three southbound lanes, killing the truck driver at the scene. The driver who caused the chain reaction stopped briefly, then fled south on I-75. Florida Highway Patrol identified the at-fault driver after investigators tracked down the vehicle. Charges include vehicular homicide and leaving a crash scene involving death. The case is still under investigation. This crash matters for victims across Florida because it captures every element that makes hit-and-run cases so difficult: a high-speed corridor, a driver fleeing before evidence is collected, and a family left without answers. The I-75 corridor between Tampa and the South Shore communities carries some of the heaviest traffic in the state. When something goes wrong at speed on that stretch of road, the results are catastrophic. ⚠️ Deadline Warning: Florida’s statute of limitations for most personal injury and wrongful death claims is 2 years from the date of the crash under Florida Statute § 95.11(3)(a), as amended in 2023. If you miss this deadline, you lose your right to sue. Do not wait to find out your options. The Reyes Firm Hurt in a Hit-and-Run Crash on I-75? Get clear next steps after a serious crash in Manatee County or anywhere in Florida. Had a bad day? Contact Us Now Can I Still Sue If the Hit-and-Run Driver Fled or Was Not Identified? Yes. Florida law gives you recovery options even if the driver is never found. You have two main paths: a civil claim against the at-fault driver once identified, and a claim through your own uninsured motorist coverage under Florida Statute 627.727. Your uninsured motorist (UM) coverage exists for exactly this situation. Florida law treats a hit-and-run driver the same as an uninsured driver. Your own policy can step in and pay for your medical bills, lost income, pain and suffering, and in a wrongful death case, the full damages your family has suffered. What Happens When a Driver Flees a Crash Scene in Florida? In this video, Attorney Edward Reyes explains what may happen after a hit-and-run crash and why uninsured motorist coverage can become important when the driver who caused the crash leaves the scene. Video note: Attorney Edward Reyes, Esq. discusses what can happen when a driver flees a crash scene and how uninsured motorist coverage may help injured victims. For informational purposes only. As Attorney Reyes explains in the video above, cameras don’t always capture the fleeing driver. Ring cameras, phone recordings, and witness accounts all become critical. But even without the driver’s identity, your UM coverage can still pay. The insurance company needs to confirm that the hit-and-run happened and that you were injured. The Reyes Firm helps clients in Tampa, Manatee County, and communities across Hillsborough County build and present exactly that case. 📊 Did You Know? Florida recorded 97,902 hit-and-run crashes in 2024, according to the Florida Department of Highway Safety and Motor Vehicles (FLHSMV). That is nearly one hit-and-run every 5 minutes. More than 1 in 4 Florida crashes in 2024 involved a driver who fled the scene. Source: FLHSMV. What Are the Criminal Charges a Hit-and-Run Driver Faces in Florida? Leaving a crash scene that results in death is a first-degree felony in Florida, carrying up to 30 years in prison with a mandatory minimum of 4 years. Florida Statute 316.027(2)(c), known as the Aaron Cohen Life Protection Act, imposes these penalties because fleeing deprives the victim of any chance at immediate help. The charge requires proof that the driver knew a crash occurred and knew or should have known someone was
Uninsured motorist coverage in Tampa
Accident Injuries & why, After A Car Accident, Blog, FAQ, Uninsured Motorist Coverage

Why It’s Essential to Have Uninsured Motorist Coverage in Tampa, Florida

Picture this: you’re driving down Bayshore Boulevard, doing everything right, when another driver runs a light and slams into you. You’re hurt, your car is wrecked, and then you learn the driver who hit you has no insurance at all. In Florida, that nightmare is far more common than most people realize, and whether you walk away financially protected often comes down to one line on your own policy. Here’s why uninsured motorist coverage may be the most important coverage you can carry after a Tampa car accident. TL;DR — QUICK SUMMARY Florida has one of the highest rates of uninsured drivers in the country, with an estimated one in five drivers carrying no insurance at all. Florida does not require most drivers to carry bodily injury liability coverage, so even an insured driver may have nothing to pay for the injuries they cause you. Uninsured and underinsured motorist (UM/UIM) coverage steps in to pay your medical bills beyond PIP, your lost wages, and your pain and suffering. Under Florida Statute 627.727, your insurer must offer you UM coverage, and settling with the at-fault driver without your UM carrier’s consent can wipe out that coverage. UM even covers hit-and-run and phantom-vehicle crashes, and you generally have two years to file an injury claim under Florida Statute 95.11(3)(a). The Reyes Firm Hit by an Uninsured Driver in Tampa? Find out if your own coverage can pay your claim. Had a bad day? Contact Us Now 1 in 5 Florida drivers are uninsured Insurance Research Council $0 Bodily injury coverage Florida requires of drivers Florida law Must Offer Insurers must offer you UM coverage Fla. Stat. 627.727 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) Why is uninsured motorist coverage so important in Florida? Uninsured motorist coverage is so important in Florida because two facts collide on our roads: a large share of drivers carry no insurance, and state law does not require most drivers to carry coverage for the injuries they cause. An estimated one in five Florida drivers has no auto insurance at all, one of the highest rates in the nation according to the Insurance Research Council, and Tampa’s heavy traffic and steady stream of out-of-town drivers only raise the odds of being hit by one. Here is the part that surprises people most. Florida requires drivers to carry Personal Injury Protection and property damage coverage, but it does not require them to carry bodily injury liability coverage, which is the coverage that would pay for your medical bills and pain after a crash they caused. That means even a driver who is following the law may have nothing available to compensate you, and your own uninsured motorist coverage becomes your safety net. What is the difference between uninsured and underinsured motorist coverage? The two go hand in hand but apply in different situations. Uninsured motorist (UM) coverage applies when the driver who hit you has no bodily injury liability insurance at all, or cannot be identified, as in a hit-and-run. Underinsured motorist (UIM) coverage applies when the at-fault driver does have liability insurance, but not enough to cover the full extent of your injuries. In Florida, the two are usually sold together as a single UM/UIM coverage, and both draw from your own policy. The practical point is the same in either case: when the other driver cannot make you whole, this coverage is what stands between you and paying for someone else’s mistake out of your own pocket. How does UM coverage fill the gap left by Florida’s no-fault system? Florida’s no-fault system gives you some protection, but not nearly enough for a serious injury. Your Personal Injury Protection coverage pays 80% of your medical bills and 60% of your lost wages, but only up to a standard limit of $10,000, and it pays nothing at all for pain and suffering. A trip to the emergency room and a single surgery can blow through that $10,000 in days. Uninsured motorist coverage picks up where PIP stops. It can pay your medical expenses beyond the PIP limit, your lost wages and reduced earning capacity, and your pain and suffering, and it protects not just you but the relatives in your household and the passengers in your car. It is especially vital for motorcycle riders, who are not covered by PIP at all and depend heavily on UM coverage when an uninsured driver hits them. 💡 Did You Know? Florida is a no-fault state that requires only $10,000 in PIP and $10,000 in property damage coverage, and it does not require most drivers to carry bodily injury liability at all. With an estimated one in five Florida drivers uninsured, your own uninsured motorist coverage is often the only source that will pay for your injuries, lost wages, and pain and suffering. Source: Insurance Research Council; Fla. Stat. § 627.736. Watch: Why you need uninsured motorist coverage in Tampa In this short video, attorney Edward Reyes explains how uninsured motorist coverage works and how it can protect you when the driver who hit you cannot pay. If you were hit by an uninsured driver, The Reyes Firm offers free consultations and can review your coverage at no cost. Does UM coverage protect you in a hit-and-run or no-contact crash? Yes, and this is one of its most valuable features. If a driver hits you and flees, or if a phantom vehicle runs you off the road without ever making contact, there may be no at-fault driver to identify and no liability insurance to pursue. Uninsured motorist coverage is built for exactly these situations and can pay for your injuries when the other driver vanishes. These claims do come with conditions, often including a requirement to corroborate that another vehicle caused the crash, which makes fast evidence-gathering critical. In the most tragic hit-and-run cases, where a family loses a loved one, UM coverage can also support a wrongful death claim when the driver is never found. ⚠️ Deadline

Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Legal, Road Accidents, Settlement, Strict Negligence, Uninsured Motorist Coverage, Why we serve

The at-fault party has no insurance: What to do

What should you do if the person that you crash into has no insurance coverage at all? What to do when the at-fault party has no insurance? How can you recover from your injuries? How can you get settlement from your damaged properties? Here’s what you can do. Watch this video for the full details.

After A Car Accident, After an Accident, Car accident, florida cities we serve, Legal, Our Community, Road Accidents, Settlement, Uninsured Motorist Coverage, Why we serve

You Need to Review your Insurance Policy after Watching this Video!

1/4 of the people are driving without insurance in Florida. Are you one of them? Hey, my name is attorney Edward Reyes and today I’m going to talk to you about bodily injury and uninsured motorists. More than a quarter of the people in Florida are driving without insurance. What does that mean to you? If somebody crashes into you and they don’t have insurance or they don’t have the provision in their insurance that says they have bodily injury, you cannot sue them for damages. Now you can’t sue them individually, but collecting can be very difficult. In the event that you are involved in a car accident, many times when you buy car insurance they tell you got full coverage but there’s no real such thing as full coverage. What does that mean? In Florida, you only need personal injury and property damage personal injury covers you for your medical and property damage covers the other person’s car, not your own car you need collision for that. Now, you need to have a bodily injury on your policy in case you hit somebody else and they make a claim against you for damages, vice versa. If somebody crashes into you and they have a bodily injury you can make a claim against their bodily injury claim for pain and suffering going forward in addition to your own auto insurance which is your personal injury protection of $10,000. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411Now if somebody crashes into you and they do not have bodily injury, if you have uninsured motorists, the uninsured motorists will cover you if they do not have insurance or if they do not have enough insurance. So, let’s use the example. Let’s say you have any $20,000 uninsured motorist policy on your policy in order for you to have that you need to have bodily injury yourself that person that crashed into you only has a ten-thousand-dollar policy. Let’s say your injuries are worth $30,000 to see the doctors and future care and things like that well they’re ten thousand will cover and then it deducts from that and then your 20 will pick up making the thirty thousand dollars in recovery. Let’s say they had no insurance your twenty thousand would kick in under your uninsured policy. If you have any questions on this feel free to reach out to us at 813-421-3411 or you can come below as well. (Transcript from the video, transcribed but not reviewed)

Car accident legal guidance infographic
Accident Injuries & why, Uninsured Motorist Coverage

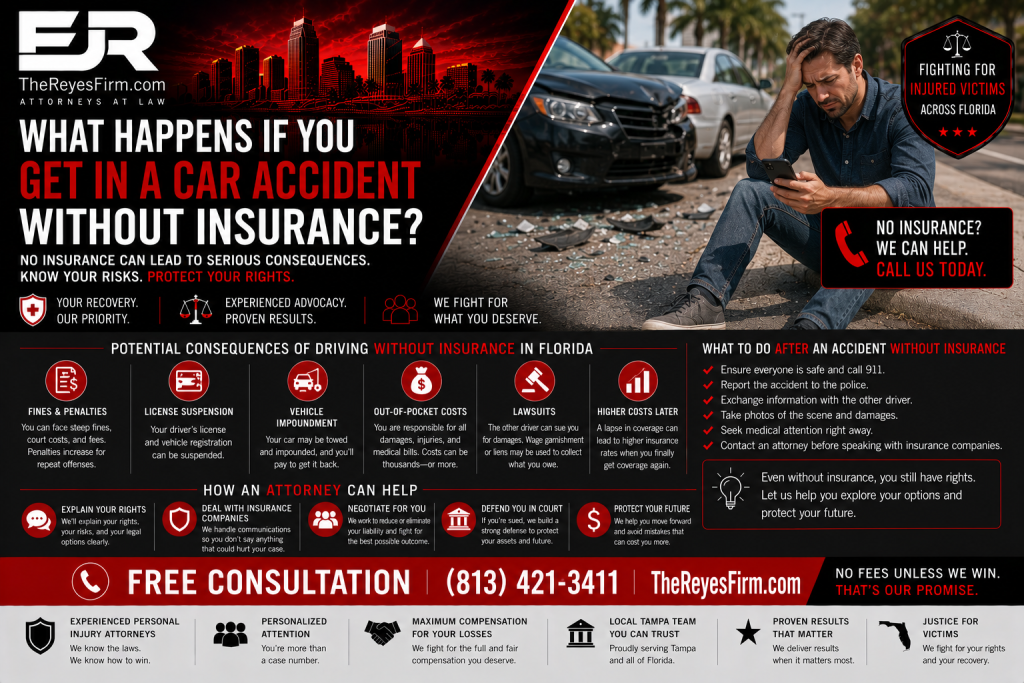
What happens if you get in a car accident without insurance?

You’ve been in a crash, and now you are staring down a confusing question: whose insurance pays for what, and in what order? Florida’s system is layered, and understanding how the pieces fit together is the difference between leaving money on the table and getting everything you are owed. Here is how auto accident claims actually work in Florida, step by step, after a car accident. The Reyes Firm Confused About Your Tampa Accident Claim? Let us map out every layer of coverage for you. Had a bad day? Contact Us Now $10,000 PIP benefits, regardless of fault Fla. Stat. § 627.736 80% / 60% PIP pays of medical bills / lost wages Fla. Stat. § 627.736 UM Coverage Protects you if the other driver has none Fla. Stat. § 627.727 2 Years Deadline to file a lawsuit Fla. Stat. § 95.11 Florida is a no-fault state, which gives its auto accident claims a structure that surprises a lot of people. Instead of one insurance company simply paying for everything, different coverages handle different parts of your losses, and they come into play in a particular order. Once you see how the layers stack up, the whole process becomes far less mysterious. How do auto accident claims work in Florida? Auto accident claims in Florida work as a layered system rather than a single payout. Your own Personal Injury Protection handles your immediate medical costs regardless of fault, the at-fault driver’s bodily injury coverage handles your pain and suffering after a settlement, and your uninsured motorist coverage protects you when the responsible driver cannot. Which layers apply, and how much each pays, depends on the coverage involved and the severity of your injuries. Think of it as a chain, where each link does a specific job. Understanding what each link covers, and when it comes into play, is the key to making sure nothing that should be paid gets missed. What does your PIP cover after a crash? Your Personal Injury Protection is the first link in the chain. Under Florida Statute § 627.736, PIP pays your medical bills and a portion of your lost wages regardless of who caused the crash, which is the heart of the no-fault system. Specifically, PIP generally covers 80% of your reasonable medical expenses and 60% of your lost wages, up to a combined limit of $10,000. There are two catches worth knowing. First, you must seek initial medical care within 14 days of the crash, or you can lose your PIP benefits entirely. Second, the full $10,000 is generally available only if a medical provider determines you had an emergency medical condition; without that finding, your PIP benefits may be capped at $2,500. This is your own coverage, so it applies no matter who was at fault. How do you recover for pain and suffering? PIP does not pay for pain and suffering, so that part of your claim comes from a different link in the chain: the at-fault driver’s bodily injury liability coverage. When another driver causes your injuries, you can pursue a claim against their coverage for the human cost of the crash, including pain, suffering, and the impact on your life, and that recovery typically comes as part of a settlement rather than upfront. There is an important condition, though. In a Florida car accident, you generally cannot step outside the no-fault system to recover pain and suffering unless your injury meets a legal threshold. That is a key reason serious injuries are treated so differently from minor ones, and why proper medical documentation matters so much to the value of your claim. 💡 Did You Know? In a Florida car accident, you generally cannot recover for pain and suffering unless your injury meets a threshold such as permanent injury within a reasonable degree of medical probability, significant permanent scarring or disfigurement, or significant and permanent loss of an important bodily function. This is why the nature and permanence of your injury drives the value of your claim. Source: Fla. Stat. § 627.737(2). What if the at-fault driver has no insurance or too little? This is where the next link matters, because a great many Florida drivers are on the road with no insurance or the bare minimum. If the driver who hit you cannot cover your injuries, your own uninsured and underinsured motorist coverage under Florida Statute § 627.727 can step in to fill the gap. Here is a detail many people miss: you may have this coverage even if you do not remember buying it, because Florida requires insurers to offer it and to obtain your rejection in writing. If you never signed a written rejection, there is a good chance the coverage is on your policy. We go deeper into this in our guide on what to do when you are hit by a driver with no insurance. What happens if the crash was your fault? Even then, you are not left with nothing. Because Florida is a no-fault state, your own PIP still pays your medical bills and a portion of your lost wages regardless of who caused the crash. That is the whole point of no-fault coverage: your immediate medical needs are handled by your own policy first, no matter who was to blame. What changes when you are at fault is your ability to recover for pain and suffering, since that comes from the other driver’s coverage. For the damage to your own vehicle, your collision coverage, if you carry it, can pay for repairs regardless of fault, subject to your deductible. 🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible. Because fault directly affects what you can recover, insurers work hard to assign as much of it to you as possible, and an experienced Tampa injury lawyer works to keep the facts straight. How do the

Motorcycle Accidents Are Different Than Car Accidents
Accident Injuries & why, After an Accident, Car accident, Injury, Legal, Motorcycles, Uninsured Motorist Coverage, Why we serve

Motorcycle Accidents Are Different Than Car Accidents

Motorcycle accidents are traumatic and the reason why because you don’t have the bumper in a car or airbags to protect you from the impact of a vehicle. In fact, many times you are thrown off your motorcycle and there are major injuries due to do the road rash. Many times, when this happens you have to undergo serious treatment and serious therapy and it’s pretty tragic. In Florida, it is not required for you to wear a helmet, however, it is highly recommended that you wear a helmet for many reasons. One, for your health, to protect your head from a higher impact from traumatic brain injury and on the legal side, the civil side to protect yourself. But also, if you do not have your helmet on, a lot of times what happens is that the insurance company on the other side, the at-fault party’s insurance company will try to deduct the injuries that you have in your head or brain and say anything that your helmet could have protected. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411This is because their stance is, if you had your helmet on, you should have been protected from the impacts or reduce the injuries and damage. It’s very important that you wear your helmet. It is very important that you are safe while keeping your distance from other vehicles. But if you are involved in a motorcycle accident and you are not at fault or even if you are at fault we can still help. It all depends on the facts and the case itself. If you have any questions on this feel free to give us a call at 833-422-3329. (Transcript from the video, transcribed but not reviewed)

Car accident help, we've got you covered
After A Car Accident, Car accident, Legal, Road Accidents, Uninsured Motorist Coverage, Why we serve

Had A Car Accident But It’s Not Your Fault?

You were just driving, walking, or biking through Tampa, doing nothing wrong. Then someone else’s mistake caused a car accident that wasn’t your fault. Now you’re hurt, worried about who pays, maybe even unsure whether your own insurance gaps will sink your claim — and the other driver’s insurer is already working to protect their interests. Here’s what you need to know before you say another word to them. TL;DR — QUICK SUMMARY If a crash wasn’t your fault, you can have a case even if you don’t carry your own insurance or weren’t in a car at all. Florida does not require drivers to carry Bodily Injury liability coverage, so whether the at-fault driver can pay for your injuries depends on what they actually carry. When the at-fault driver has no Bodily Injury coverage, your own uninsured/underinsured motorist coverage often becomes your most important source of recovery. Under Florida Statute § 95.11(3)(a), you generally have two years from the date of the crash to file a personal injury lawsuit. Florida’s comparative fault rule means partial fault reduces your recovery, but being found not at fault protects the full value of your claim. The Reyes Firm Hit in a Crash That Wasn’t Your Fault? Get clear next steps when someone else caused your wreck. Had a bad day? Contact Us Now Optional Bodily injury coverage in Florida FL Financial Responsibility Law $10,000 Florida required PIP coverage Fla. Stat. § 627.736 2 Years Florida statute of limitations Fla. Stat. § 95.11(3)(a) 50%+ Fault that bars recovery in Florida Fla. Stat. § 768.81 Do you have a case if a car accident wasn’t your fault in Tampa? Yes, if a car accident wasn’t your fault, you generally have a case against the driver who caused it. Florida law lets an injured person hold a negligent driver financially responsible for the harm they caused, whether you were behind the wheel, on foot, or on a bicycle. What changes from case to case isn’t whether you have a claim — it’s where the money to pay that claim actually comes from. That depends heavily on what insurance the at-fault driver carries and what coverage you have on your own policy. Sorting that out early is one of the most important things a lawyer does for you. Can you recover if it wasn’t your fault but you don’t have insurance? Often, yes. If the crash was caused by another driver and you were a pedestrian, a cyclist, or a scooter rider, you generally aren’t required to carry auto insurance, and you can still pursue the at-fault driver’s coverage for your injuries. It gets more complicated if you own a car and didn’t carry the Personal Injury Protection that Florida requires, because that can limit some of the benefits available to you. It doesn’t automatically erase your right to recover from the person who hurt you, but it’s exactly the kind of wrinkle you want a lawyer reviewing before you talk to any insurer. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Watch: What to do when a crash wasn’t your fault This short video explains how recovery works after a not-at-fault crash and why the other driver’s coverage — or lack of it — makes such a difference. If you still have questions after watching, The Reyes Firm offers a free consultation so you can talk through your specific situation with a real attorney. Why doesn’t Florida require Bodily Injury coverage, and why does that matter? Florida is one of the few states that does not require most drivers to carry Bodily Injury liability coverage, which is the coverage that pays for the injuries an at-fault driver causes to other people. Drivers are required to carry Personal Injury Protection under Florida Statute § 627.736 and property damage liability, but not Bodily Injury. That matters enormously after a not-at-fault crash. If the driver who hit you carries Bodily Injury coverage, their policy can pay for your injuries even if you had no insurance of your own. If they don’t carry it, that source of money simply isn’t there, and you have to look elsewhere — which is where your own coverage comes in. 💡 Did You Know? Because Florida doesn’t require Bodily Injury liability coverage, a driver who causes your injuries may legally have no coverage to pay for them — even though the crash was entirely their fault. That’s the single biggest reason to carry uninsured/underinsured motorist coverage on your own policy. Source: Florida Financial Responsibility Law, leg.state.fl.us. What if the at-fault driver has no Bodily Injury coverage? If the at-fault driver has no Bodily Injury coverage, your own uninsured/underinsured motorist coverage often becomes your most important source of recovery. UM/UIM coverage, governed by Florida Statute § 627.727, is designed to step in exactly when the responsible driver can’t pay. This coverage can come from your own policy, and in some situations from a resident relative’s policy, even if you weren’t in a car at the time. There may also be other parties to pursue, such as an employer if the driver was working. An attorney’s job is to find every available policy so you aren’t left absorbing someone else’s mistake. Who is liable when the accident wasn’t your fault? Liability falls on whoever failed to use reasonable care, which in a not-at-fault crash is the other driver. A motorist who was speeding, distracted, ran a light, or failed to yield can be held responsible for the harm they caused, regardless of whether you carried your own insurance. In some cases more than one party shares responsibility, such as an employer whose driver was on the clock or a business that overserved an impaired driver. Identifying every responsible party matters, because each one may bring additional insurance coverage to

Crash recovery legal help infographic
Settlement, Uninsured Motorist Coverage

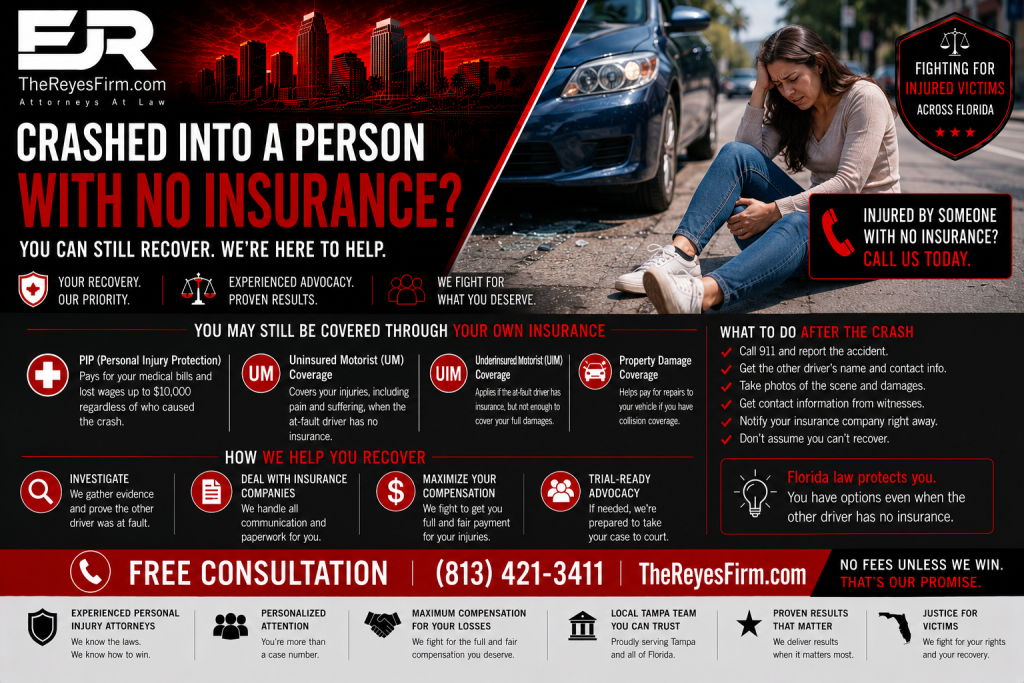
Crashed Into A Person With No Insurance?

The other driver ran the light, wrecked your car, and left you hurting. Then comes the gut punch: they have no insurance. It feels like you have no way to recover, but in Florida that is often not true. Between your own coverage and the state’s rules, you may have far more protection than you realize after a car accident with an uninsured driver. Here is how it works. The Reyes Firm Hit by an Uninsured Driver in Tampa? You may have more coverage than you think. Let us check. Had a bad day? Contact Us Now UM Coverage Your protection when the other driver has none Fla. Stat. § 627.727 In Writing UM applies unless you rejected it in writing Fla. Stat. § 627.727 $10,000 PIP pays your bills regardless of fault Fla. Stat. § 627.736 2 Years Deadline to file an injury lawsuit Fla. Stat. § 95.11 Discovering that the person who hurt you carried no insurance is one of the most frustrating moments after a crash. It feels like the responsible party gets to walk away while you are left with the bills. The good news is that Florida’s insurance system was built with this exact problem in mind, and the path to recovery usually runs through coverage you may already have. What happens if the driver who hit you has no insurance? You still have options. In Florida, being hit by an uninsured driver does not mean you are out of luck, because your recovery does not depend entirely on the other driver’s insurance. It depends first on your own coverage, which Florida’s no-fault system and uninsured motorist rules are designed to provide. This matters more here than in most states, because Florida consistently ranks among the states with the highest percentage of uninsured drivers. Being prepared for this situation is not paranoia in Florida, it is simply realistic, and the drivers who come through it best are usually the ones who understand their own policy. Does Florida’s no-fault system still cover you? Yes. Florida is a no-fault state, which means your own Personal Injury Protection coverage under Florida Statute § 627.736 pays your medical bills first, regardless of who caused the crash. Because PIP is your own coverage, it applies whether the other driver had insurance or not, as long as you seek initial medical care within 14 days of the crash. The limitation is that PIP only goes so far. It covers a portion of your medical expenses and lost wages up to a $10,000 cap, and it does not compensate you for pain and suffering. For a serious injury, PIP is a starting point, not the whole answer, which is where uninsured motorist coverage becomes essential. What is uninsured motorist coverage, and how does it help? Uninsured motorist coverage, often called UM, is the single most important protection when the at-fault driver has no insurance. It essentially steps into the shoes of that driver’s missing policy and pays for the harm they caused you, including the pain and suffering and the excess medical costs that PIP does not cover. A closely related coverage, underinsured motorist coverage, applies when the at-fault driver has some insurance but not enough to cover your injuries. There is an important wrinkle worth understanding. When you file a UM claim, you are making a claim against your own insurance company, which means your insurer is now on the other side of your claim. That can feel strange, and it is one reason these claims sometimes become contentious even though you have paid your premiums faithfully. 💡 Did You Know? You may already have uninsured motorist coverage without realizing it. Under Fla. Stat. § 627.727, an insurer generally must offer UM coverage equal to your bodily injury liability limits, and you can only reject it or choose lower limits in writing on an approved form. If you never signed such a rejection, there is a good chance you have this coverage. Source: Fla. Stat. § 627.727. What if you didn’t think you had uninsured motorist coverage? Check before you assume the worst. Because Florida law requires insurers to offer UM coverage and to obtain a written rejection if you decline it, many drivers carry this coverage even though they do not remember choosing it. The rejection form itself must carry a bold warning that you are giving up valuable protection, precisely because the state wants drivers to have it. The practical takeaway is simple: do not give up before someone reviews your actual policy. Pulling your declarations page and reading exactly what coverage you carry is one of the first things worth doing, and a lawyer can do it with you to make sure nothing is missed. What looks like a hopeless situation frequently turns out to be a covered one. 🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible. When the at-fault driver is uninsured, insurers sometimes lean harder on blaming you, and an experienced Tampa injury lawyer works to keep the facts straight and your assigned fault as low as the evidence allows. Can you sue an uninsured driver personally? You can, but it is often not the most productive path. A driver who cannot afford insurance frequently cannot afford to pay a judgment either, and a court award means little if there are no assets to collect from. This is the old problem of trying to get blood from a stone, and it is why your own uninsured motorist coverage usually matters far more than a lawsuit against the individual. That said, an uninsured driver is not always the only responsible party. Sometimes another person or company shares liability, such as an employer if the driver was working, or the owner of the vehicle if someone else let them drive it. Identifying every potentially responsible party is part of what

Moped accidents rising in Tampa area
Accident Injuries & why, After an Accident, Blog, Moped Accidents, Uninsured Motorist Coverage, Why we serve

What Are Moped Accidents and Why Are they on the Rise?

You were just riding through Tampa like any other day. Then a careless driver turned across your path and your moped accident changed everything. Now you’re in pain, staring at medical bills, and the at-fault driver’s insurance company is already working to protect their bottom line. Here’s what you need to know before you say another word to them. TL;DR — QUICK SUMMARY Moped use is climbing across Tampa’s dense, walkable neighborhoods, and more riders on the road means more serious crashes with cars and trucks. Moped riders are far more exposed than people inside cars, so even a low-speed collision can cause head trauma, broken bones, and spinal injuries. Florida’s no-fault PIP coverage usually does not protect moped and motorcycle riders the way it protects car occupants, which changes how you recover compensation. Under Florida Statute § 95.11(3)(a), you generally have two years from the date of the crash to file a personal injury lawsuit. Your recovery typically comes from the at-fault driver’s bodily injury liability coverage and, in many cases, your own uninsured/underinsured motorist coverage. The Reyes Firm Hurt in a Moped Accident in Tampa? Get clear next steps after a serious moped crash. Had a bad day? Contact Us Now 2 Years Florida statute of limitations Fla. Stat. § 95.11(3)(a) 30 mph Top speed that legally defines a moped Fla. Stat. § 316.003 Under 16 Moped riders required to wear a helmet Fla. Stat. § 316.211 50%+ Fault that bars recovery in Florida Fla. Stat. § 768.81 Why are moped accidents on the rise in Tampa? Moped accidents are rising in Tampa because more people are choosing mopeds for short, everyday trips in dense neighborhoods where they live, work, and play within a few miles. Instead of pulling out a car for a quick errand, residents grab a moped, and the result is far more two-wheel traffic sharing the road with cars, SUVs, and delivery trucks. That shift creates predictable danger. Drivers in Tampa simply are not looking for mopeds. They check for other cars at intersections, on University-area streets, and along busy corridors, but they overlook smaller, slower vehicles in the lane next to them. Left-turn collisions, sideswipes, and rear-end crashes follow, and the rider almost always absorbs the worst of it. Can you file a claim after a moped accident in Tampa, Florida? Yes, you can file a claim after a moped accident in Tampa if another party’s negligence caused or contributed to the crash. A driver who turned in front of you, ran a light, or never checked their mirror can be held financially responsible for your medical bills, lost wages, and pain and suffering. The key is acting before the clock runs out and before critical evidence disappears. Skid marks fade, vehicles get repaired, and witness memories blur within days. The sooner a Tampa moped accident lawyer starts protecting the facts, the stronger your claim tends to be. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Watch: Why moped accidents happen and what to do In this short video, Edward Reyes, Esq. explains why mopeds are out on Tampa roads more than ever and what coverage matters if you are injured while riding. If you still have questions after watching, The Reyes Firm offers a free consultation so you can talk through your specific situation with a real attorney. Why do moped accident injuries tend to be so severe? Moped injuries are so severe because the rider has almost nothing between their body and the road. There is no steel cage, no airbag, and no seatbelt, so the forces of a collision transfer directly to the person instead of the vehicle. That is why even a “minor” crash can leave a moped rider with a traumatic brain injury, a spinal cord injury, broken bones, road rash, or internal trauma. Many of the cases we see look similar to the most serious motorcycle accident claims, because the physics of a two-wheel crash are unforgiving. 💡 Did You Know? Under Florida Statute § 316.003, a true “moped” is narrowly defined as a low-powered vehicle with pedals that cannot exceed 30 mph on level ground. Many vehicles riders call “mopeds” are actually motor scooters under the law, which can change registration, licensing, and insurance rules after a crash. Source: Florida Statutes, leg.state.fl.us. Who is liable after a moped accident in Tampa? Liability after a moped accident depends on who failed to use reasonable care, and it is often the driver of the other vehicle. A motorist who turns left across your lane, fails to yield, follows too closely, or opens a door into your path can be held responsible for the harm they caused. In some cases, more than one party shares fault. A government entity responsible for a dangerous road defect, a business that overserved an impaired driver, or a maintenance shop that botched a repair can all be pulled into a claim. Identifying every responsible party matters, because it often determines how much insurance coverage is actually available to you. 🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible for your own harm. An experienced Tampa moped accident lawyer works to protect the facts, challenge unfair blame, and keep your percentage of fault as low as the evidence allows. Does Florida no-fault insurance cover moped accident injuries? Usually not in the way riders expect. Florida’s no-fault system, built around Personal Injury Protection under Florida Statute § 627.736, is designed for people injured while occupying a car, not riders on two wheels. PIP benefits generally do not extend to injuries you suffer while riding a moped or motorcycle. That gap is exactly why

Motorcycle accident Here's what to do.
Accident Injuries & why, After an Accident, FAQ, For Parents, For Teens, Health, Injury, Motorcycles, Road Accidents, Scooter Accident, Traumatic injury, Uninsured Motorist Coverage, Why we serve

Motorcycle Accidents Cause More Injuries: What to Do?

You were just riding home through Tampa. Then a driver who never saw you turned across your lane, and in an instant everything changed. Now you’re facing serious injuries, mounting medical bills, and an insurance company that is already building its case against you. Here’s what you need to know about your Florida motorcycle accident claim before you say another word to an adjuster. TL;DR — QUICK SUMMARY Motorcycle riders absorb the full force of a crash with almost no protection, which is why these collisions cause far more severe injuries than typical car accidents. Florida’s no-fault PIP insurance does not cover motorcycle injuries, so you generally must pursue the at-fault driver and their bodily injury liability coverage directly. Evidence such as skid marks, vehicle damage, and dashcam or surveillance footage disappears quickly, so preserving it early can make or break your case. You have two years from the date of the crash to file a personal injury lawsuit under Florida Statute 95.11(3)(a), and missing this deadline usually ends your claim. Even if you legally rode without a helmet, the insurer may try to blame you to cut your payout, and an experienced Tampa attorney can push back. The Reyes Firm Hurt in a Motorcycle Crash in Tampa? Get clear next steps after a serious motorcycle accident. Had a bad day? Contact Us Now 578 Florida motorcycle deaths in 2024 FLHSMV Crash Dashboard 2024 9,420 Florida motorcycle crashes in 2024 FLHSMV Crash Dashboard 2024 2 Years Florida statute of limitations Fla. Stat. 95.11(3)(a) #1 Deadliest U.S. state for riders FLHSMV / NHTSA, 3 years running Why do motorcycle accidents cause so much more serious injury than car crashes? Motorcycle accidents cause more severe injuries because a rider has almost nothing between their body and the road, while a car occupant is surrounded by a steel frame, seatbelts, crumple zones, and airbags. When a motorcycle is struck, the rider is often thrown from the bike and hits the pavement, another vehicle, or a fixed object with the full force of the impact. That physics is why a crash that might leave a car driver shaken but uninjured can leave a motorcyclist with life-altering harm. Common motorcycle accident injuries include traumatic brain injuries, spinal cord injuries and paralysis, broken bones, severe road rash, internal organ damage, and amputations. Head injuries are especially dangerous. A serious traumatic brain injury can change how you think, work, and live, sometimes permanently. In the most tragic cases, families are left pursuing a wrongful death claim after losing someone they love. The severity of these injuries is also why motorcycle claims deserve to be taken seriously from day one. Can you sue the driver who caused your Tampa motorcycle accident? Yes. If another driver’s negligence caused your motorcycle crash, you can pursue a claim against that driver for the harm they caused you. Florida law lets injured riders seek compensation when someone else’s careless or reckless driving leads to their injuries, whether the other driver ran a red light, turned left across your path, followed too closely, or was distracted behind the wheel. The challenge is that motorcyclists face an unfair stigma. Insurance companies often assume the rider was speeding or weaving, even when the driver of the car was entirely at fault. Building your case means proving what actually happened, and that work starts the moment the crash occurs. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Does Florida’s no-fault insurance cover your motorcycle accident? No. Florida’s no-fault Personal Injury Protection (PIP) system does not cover motorcycle injuries, even though it covers drivers and passengers in cars. Under Florida Statute § 627.736, PIP benefits apply to motor vehicles as the statute defines them, and motorcycles fall outside that definition. This is one of the most misunderstood points in Florida motorcycle law, and it has real consequences. Unlike a car accident, where your own PIP pays the first portion of your medical bills regardless of fault, an injured motorcyclist usually has to recover from the at-fault driver’s bodily injury liability coverage, plus any uninsured or underinsured motorist and MedPay coverage you carry on your own policy. Because that compensation depends on proving fault and locating the right insurance, having a lawyer who knows how to stack these sources of coverage matters. 💡 Did You Know? According to the Florida Highway Safety and Motor Vehicles Crash Dashboard, Florida recorded 9,420 motorcycle crashes in 2024, resulting in 578 rider deaths and 8,106 injuries. For the third year in a row, Florida led the nation in motorcycle fatalities. Source: FLHSMV Crash Dashboard, 2024. Note: 2024 crash numbers are preliminary. Watch: How Motorcycle Accidents Are Different Than Car Accidents This short video walks through the first moves that protect both your health and your legal claim after a motorcycle crash in Florida. If you have questions after watching, The Reyes Firm offers free consultations and can review your situation at no cost. Who is actually liable for your Tampa motorcycle crash? Liability depends on who caused the crash, and it is not always only the other driver. Depending on the facts, responsible parties can include the at-fault motorist, their employer if they were driving for work, a vehicle owner who let an unsafe driver use their car, a government agency responsible for a dangerous road defect, or a manufacturer whose defective part contributed to the wreck. Florida also follows a modified comparative negligence rule, which means the insurance company will look for ways to shift blame onto you. One common tactic in motorcycle cases involves helmets. Florida law under Florida Statute § 316.211 allows riders 21 and older to ride without a helmet if they carry at least $10,000 in medical benefits coverage. Even when you rode legally, a defense lawyer may argue that not wearing

Scroll to Top