Settlement

After A Car Accident, After an Accident, Car accident, florida cities we serve, Legal, Our Community, Road Accidents, Settlement, Uninsured Motorist Coverage, Why we serve

You Need to Review your Insurance Policy after Watching this Video!

1/4 of the people are driving without insurance in Florida. Are you one of them? Hey, my name is attorney Edward Reyes and today I’m going to talk to you about bodily injury and uninsured motorists. More than a quarter of the people in Florida are driving without insurance. What does that mean to you? If somebody crashes into you and they don’t have insurance or they don’t have the provision in their insurance that says they have bodily injury, you cannot sue them for damages. Now you can’t sue them individually, but collecting can be very difficult. In the event that you are involved in a car accident, many times when you buy car insurance they tell you got full coverage but there’s no real such thing as full coverage. What does that mean? In Florida, you only need personal injury and property damage personal injury covers you for your medical and property damage covers the other person’s car, not your own car you need collision for that. Now, you need to have a bodily injury on your policy in case you hit somebody else and they make a claim against you for damages, vice versa. If somebody crashes into you and they have a bodily injury you can make a claim against their bodily injury claim for pain and suffering going forward in addition to your own auto insurance which is your personal injury protection of $10,000. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411Now if somebody crashes into you and they do not have bodily injury, if you have uninsured motorists, the uninsured motorists will cover you if they do not have insurance or if they do not have enough insurance. So, let’s use the example. Let’s say you have any $20,000 uninsured motorist policy on your policy in order for you to have that you need to have bodily injury yourself that person that crashed into you only has a ten-thousand-dollar policy. Let’s say your injuries are worth $30,000 to see the doctors and future care and things like that well they’re ten thousand will cover and then it deducts from that and then your 20 will pick up making the thirty thousand dollars in recovery. Let’s say they had no insurance your twenty thousand would kick in under your uninsured policy. If you have any questions on this feel free to reach out to us at 813-421-3411 or you can come below as well. (Transcript from the video, transcribed but not reviewed)

Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Company-Caused Car Accidents, Legal, Settlement, Why we serve

Auto Accident: Is It Okay to Work with Other Insurance Company?

Here is a myth, can I work it out with the other insurance company if I’m involved in an auto accident? The question is, yes. Is it recommended? My Name is Edward Reyes and I’m a personal injury attorney, here in Florida. Yes, you can work it out with the other company but keep in mind they are looking to save money on their insurance company because they work for the insurance company. The people that are writing the checks, are adjusters adjusting the claim out and they’re trying not to spend the money of their boss, which is the insurance company. Yes, you can work it out with the other company, you can work it out with the other person but in my experience that I have seen, I have seen many times people try to work it out and they get shortchanged from the other side trying to mitigate or reduce the damages that you’re suffering. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411This happens all the time. In fact, a personal story, my first car accident when I was younger, somebody gave me $400 and I thought that was enough. Come to find out, to make the repairs on my car, were over a thousand something dollars and the injuries that I felt after the fact, were much greater than that. So, can you work it out? The technical answer is yes. Should you work it out with them by yourself? So that myth is busted. If you have any questions on this and if you’d like to hear more case stories, feel free to give us a call 833-4-BAD DAY (833-422-3329).   (Transcript from the video, transcribed but not reviewed)

Settlement process infographic for attorneys
Health, Settlement

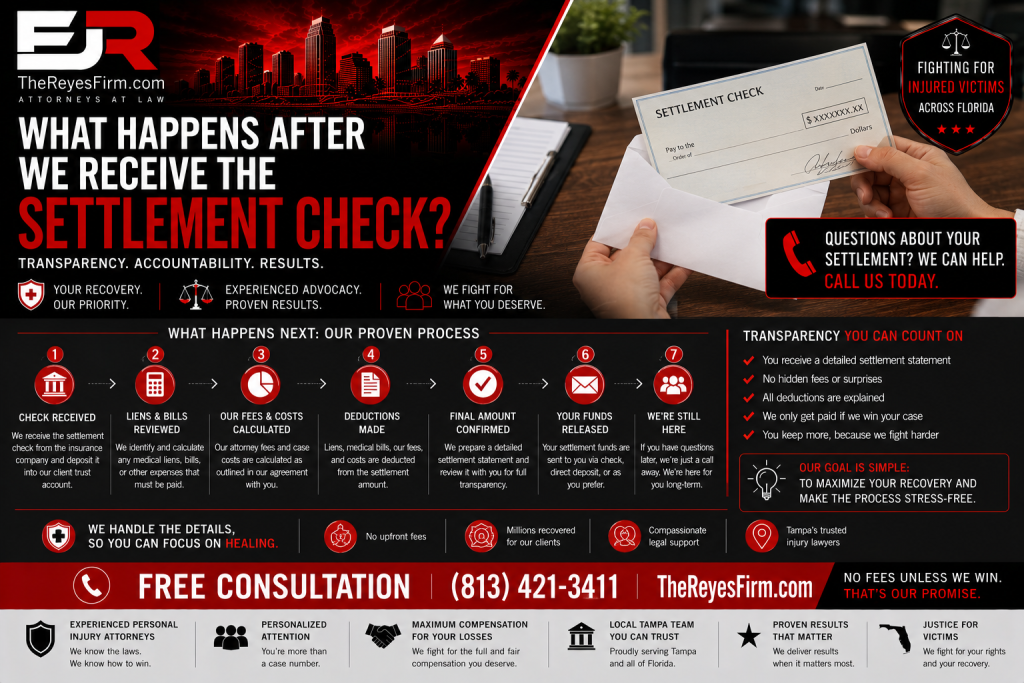
What Happens After We Receive the Settlement Check?

The call finally comes: your case has settled, and the check is on its way. It feels like the finish line, and in many ways it is. But there is one more important stretch between the settlement and the money landing in your pocket, and understanding it helps you see exactly why the work continues. Here is what happens after your lawyer receives the settlement check in your injury case. The Reyes Firm Questions About Your Tampa Settlement? We fight to maximize what actually reaches you. Had a bad day? Contact Us Now Your Net What matters is the money you keep After liens and fees Liens Bills repaid from your settlement Medical and other liens Negotiable Many liens and bills can be reduced Where a lawyer adds value Held in Trust Your funds are safeguarded first How it works After months of treatment and negotiation, a settlement can feel like the moment everything is finally over. In truth, a good lawyer’s job shifts at this point rather than ending. The goal now is to make sure that as much of that settlement as possible ends up with you, the person who actually went through the injury, rather than being eaten up by bills that could have been reduced. What happens after your lawyer receives the settlement check? When the settlement check arrives, it does not go straight to you, and that is by design and for your protection. The funds are first deposited into the firm’s trust account, and then a series of obligations tied to your case are resolved before the remainder, your net recovery, is paid to you. Those obligations typically include medical liens, outstanding bills, case costs, and the attorney’s fee. This is the part of the process most people never hear about until they are in it. Handled well, it is where a lawyer can meaningfully increase the amount you actually take home, by reducing what has to be paid out along the way. What are medical liens, and why must they be repaid? A medical lien is a right to be repaid from your settlement, held by a party that paid for or provided your accident-related care. Several kinds can appear in an injury case. A health insurer that covered your treatment may assert a right to reimbursement. A hospital may file a lien. A provider who treated you under a letter of protection agreed to be paid from your eventual settlement. And government programs like Medicare and Medicaid have their own reimbursement rights under federal and state law. For valid liens, repayment is not optional, and your lawyer is generally required to satisfy them from the settlement. That obligation exists to reimburse those who effectively advanced the cost of your care. The key is making sure each claimed lien is actually valid and correctly calculated, and then reducing it wherever the law and the circumstances allow. How does using health insurance increase your net recovery? It sounds backward, but running your accident treatment through your health insurance often leaves you with more money at the end. The reason is that health insurers do not pay providers the full billed amount. They pay a contracted, negotiated rate that is usually far lower, and the amount repaid from your settlement is generally tied to that reduced figure rather than the original bill. Suppose a hospital billed $10,000 for your care. If your health insurer had a contracted rate of roughly $3,000 for that treatment, the repayment obligation from your settlement is generally based on that lower negotiated number, not the full $10,000. That difference stays in your pocket, which is a significant and often overlooked benefit of using your coverage. 💡 Did You Know? Using your health insurance for accident treatment can increase your net recovery. Because health insurers reimburse providers at negotiated rates well below the billed charges, the amount that must be repaid from your settlement is often much smaller than the original bill, leaving more money with you. Can medical bills and liens be reduced? Yes, and this is one of the most valuable things a lawyer does after a settlement. Liens and outstanding bills are frequently negotiable, and reducing them directly increases what you keep. Lawyers negotiate with health insurers, hospitals, and providers to lower the amounts owed, sometimes citing the costs and effort that produced the recovery, sometimes on grounds of hardship, and sometimes simply because a provider would rather accept a reduced sum than risk collecting nothing. If you did not have health insurance and have outstanding bills, the same principle applies. Your lawyer works with those providers to reduce the balances as much as possible before the final numbers are set, so that more of the settlement reaches you rather than the billing department. ⚠️ Important Warning: Never spend or disburse settlement money before your liens are resolved. Funds paid out before valid liens are satisfied can leave you personally responsible for repaying them later, and unresolved Medicare or Medicaid obligations in particular can create serious problems. This is exactly why the work continues carefully after the check arrives. What other obligations come out of a settlement? Beyond medical liens, a few other items are typically resolved from the settlement. The attorney’s fee, usually a contingency percentage agreed to at the start, comes out of the recovery, as do the case costs advanced during your case, such as records fees, expert charges, and filing costs. In some situations, other legal obligations apply as well, such as a child support lien, which the law may require be paid from a settlement. None of this should be a mystery to you. A reputable firm accounts for every one of these items in a written settlement statement, so you can see precisely how the total was distributed and how your net figure was reached. 🛡️ Your Rights: You have the right to a clear, itemized settlement statement showing exactly how your settlement was distributed, every lien, every case cost, the

Protect your rights medical liens explained
After an Accident, Car accident, Health, Legal, Settlement, Why we serve

What You Should Know About Medical Liens?

You did the smart thing after your Tampa accident and used your health insurance to get the care you needed. Then you hear a word that makes your stomach drop: lien. Suddenly it sounds like everyone who paid a medical bill wants a piece of your settlement. Here’s what a medical lien really is, who can claim one in Florida, and why the right approach often leaves more money in your pocket, not less. TL;DR — QUICK SUMMARY A medical lien is a legal claim to be repaid from your settlement by whoever covered your accident-related medical care. Your health insurer can seek repayment through subrogation, but under Florida Statute 768.76 its lien is reduced by its share of your attorney’s fees and costs. Medicare and Medicaid have far stronger repayment rights that cannot be ignored, with Medicaid’s lien attaching automatically under Florida Statute 409.910. Using health insurance usually shrinks the bill, because insurers pay providers at reduced negotiated rates, so less comes out of your recovery. Most liens are negotiable, and resolving them before you sign is how you protect what you actually take home. The Reyes Firm Worried a Lien Will Eat Your Settlement? Let us protect what you take home from your Tampa claim. Had a bad day? Contact Us Now $10,000 Florida PIP pays before health insurance Fla. Stat. 627.736 Pro Rata Health insurer liens cut by their share of fees Fla. Stat. 768.76(4) Automatic Medicaid’s lien attaches by law Fla. Stat. 409.910(6) 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) What is a medical lien, and why does it come out of your settlement? A medical lien is a legal claim to be repaid from your settlement by an insurer, provider, or government program that covered your accident-related medical care. The idea behind it is simple: those bills were paid on the understanding that, if someone else caused your injuries, the money would be paid back out of whatever you recover from the at-fault party. This matters most when your injuries are serious and your bills are large, such as after a catastrophic crash. A lien does not reduce what the at-fault party owes you. It determines how much of your recovery you actually keep after the people who paid your bills are reimbursed, which is why understanding and controlling these liens is a real part of winning your case. Who can put a lien on your personal injury settlement in Florida? Several different parties can claim repayment, and they do not all have the same rights. The most common lien holders are your private health insurer, which may seek reimbursement through subrogation; hospitals, which in some Florida counties, including parts of the Tampa and Hillsborough County area, can assert a lien under a local ordinance; and government programs like Medicare and Medicaid, which have powerful repayment rights set by statute. There is also a fourth situation. If you had no health insurance, or chose not to use it, a doctor may have treated you under a Letter of Protection, which is an agreement to wait and be paid directly from your settlement. That arrangement creates a lien-like claim on your recovery too. The first job in any case is identifying every one of these claims, because a lien you forget about does not disappear, it follows you. How does health insurance subrogation actually work? When your health insurer pays accident-related bills, it often has a right to be paid back out of your settlement, and that right is called subrogation. Under Florida Statute § 768.76, a health insurer that has properly asserted this right can be reimbursed only from what you actually recover, and its claim is reduced by its pro-rata share of the attorney’s fees and costs you paid to obtain that recovery. Two things make this far better for you than it first sounds. The insurer is usually repaid based on the discounted rate it actually paid the provider, not the much higher billed amount, and that repayment is then cut down by its share of your legal costs. The main exception is a self-funded employer health plan governed by federal ERISA law, which can have stronger reimbursement rights than a state-regulated plan, so the type of plan you have genuinely matters to the outcome. 💡 Did You Know? Under Fla. Stat. § 768.76, a health insurer’s reimbursement is limited to what you actually recovered and must be reduced by the insurer’s pro-rata share of your attorney’s fees and costs. Combined with the discounted rates insurers pay providers, this often means using your health insurance leaves you with more money than letting the full medical bill ride to settlement. Source: Fla. Stat. § 768.76, leg.state.fl.us. What about Medicare and Medicaid liens? Government liens are a different animal, and they cannot be ignored. Florida Medicaid is automatically subrogated to your claim and holds an automatic lien for the full amount it paid under Florida Statute § 409.910, while Medicare’s repayment rights come from federal law and function as a so-called super lien on your recovery. The good news is that the amount these programs actually collect can often be reduced, for Medicaid by reasonably allocating your settlement to past medical expenses, and for Medicare through its conditional-payment resolution process. The bad news is that disbursing your settlement without addressing them is a serious mistake, because the government can pursue repayment afterward, with interest. These claims come up in any case with major medical care, including large truck and commercial vehicle settlements. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Watch: How medical liens affect your settlement In this short video, attorney Edward Reyes explains how medical liens work and why using your health insurance can still be the smart move after an accident. Tampa personal injury

Why insurance undervalues your pain
After A Car Accident, After an Accident, Car accident, Legal, Settlement, Why we serve

Why Insurance Company Undervalue your Pain?

You’re in real pain after your Tampa car accident, but the insurance adjuster keeps acting like it’s no big deal. They weren’t in the crash. They don’t feel your back seize up every morning. To them, you are a stack of paper, and if that paper doesn’t tell the right story, they will value your pain at close to nothing. Here’s why that happens, and how to make sure your pain is taken seriously. TL;DR — QUICK SUMMARY Insurance companies undervalue pain because it is subjective, and Florida’s no-fault law only makes them pay for it when your injury is permanent. Your PIP coverage pays 80% of medical bills and 60% of lost wages up to $10,000, but it pays nothing for pain and suffering. To recover pain and suffering from the at-fault driver, your injury must meet one of four permanency categories under Florida Statute 627.737. Gaps in treatment and old injuries are the two tools insurers use most to argue your pain is not real or not from the crash. You have two years from the crash to file a lawsuit under Florida Statute 95.11(3)(a), and consistent medical proof is what protects your claim’s value. The Reyes Firm Is the Insurance Company Downplaying Your Pain? Get your Tampa injury claim valued fairly. Had a bad day? Contact Us Now 4 Injury categories that allow pain & suffering Fla. Stat. 627.737(2) $10,000 Standard Florida PIP limit Fla. Stat. 627.736 80% Of medical bills PIP pays, none for pain Fla. Stat. 627.736 2 Years To file an injury lawsuit Fla. Stat. 95.11(3)(a) Why do insurance companies undervalue your pain after a car accident? Insurance companies undervalue your pain because pain is subjective, hard to measure, and easy to dispute, and because Florida law only forces them to pay for it under specific conditions. A broken bumper has a price tag. The ache that keeps you from lifting your child or sleeping through the night does not, so the adjuster treats it as negotiable, then looks for reasons to push its value down. The deeper problem is that the insurer only knows you on paper. It has never met you and does not feel what you feel, so it judges your pain entirely by your medical records. If those records show consistent treatment and a clear diagnosis, your pain looks real. If they show gaps, missed appointments, or no imaging, the insurer will argue you must not be hurting much at all. Understanding how that paper trail is read is the first step to protecting what your claim is actually worth. What does Florida’s no-fault system actually pay for your pain? On its own, your no-fault coverage pays nothing for pain and suffering. Florida’s Personal Injury Protection (PIP) coverage under Florida Statute § 627.736 pays 80% of your medical bills and 60% of your lost wages, up to a standard limit of $10,000, and that money covers economic losses only. Pain, suffering, mental anguish, and the loss of enjoyment of your life are non-economic damages, and you can only recover them by stepping outside the no-fault system and pursuing the at-fault driver directly. Florida does not let you do that for every injury, which is exactly the gap insurers rely on. To reach your pain and suffering, you first have to clear a legal bar called the permanency threshold. When can you recover pain and suffering in Florida? You can recover pain and suffering only when your injury meets Florida’s permanency threshold. Under Florida Statute § 627.737(2), you may pursue non-economic damages from the at-fault driver only if your injury involves one of four things: significant and permanent loss of an important bodily function, a permanent injury within a reasonable degree of medical probability, significant and permanent scarring or disfigurement, or death. The phrase that decides most cases is “permanent injury within a reasonable degree of medical probability.” Proving it usually takes more than your word. It takes the right imaging, the right specialist, and a doctor willing to state that your injury is permanent. This is why a thorough diagnosis matters so much, especially for back, neck, and spine injuries where an MRI can reveal disc damage that an X-ray misses, or for head injuries where a traumatic brain injury may need a neurologist rather than a general doctor to document. 💡 Did You Know? Under Florida’s no-fault law, you cannot recover a dollar of pain and suffering from the at-fault driver unless your injury meets one of four permanency categories in Fla. Stat. § 627.737(2), and the permanency normally has to be confirmed by a doctor to a reasonable degree of medical probability. This single requirement is why proper diagnosis can change a claim’s value dramatically. Source: Fla. Stat. § 627.737, leg.state.fl.us. Watch: Why the insurance company says you’re not really in pain In this short video, attorney Edward Reyes explains how insurers use your medical records to argue your pain isn’t serious, and what you can do about it. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411If an adjuster is downplaying what you’re going through, The Reyes Firm offers free consultations and can review your situation at no cost. How gaps in treatment lower the value of your pain Nothing hands an insurer more ammunition than a gap in your treatment. When weeks or months pass with no doctor visits, the adjuster’s argument writes itself: if you were really in pain, you would have kept seeing someone about it. A long delay between the crash and your care, or a stretch where you simply stopped going, becomes their reason to discount how you feel. Consistency is your best answer. Steady, documented treatment shows that your pain is ongoing and real, builds the medical record needed to prove permanency, and removes the insurer’s favorite excuse. The same urgency applies to

Auto accident claims process in Florida
After A Car Accident, Settlement

How Do Auto Accident Claims Work in Florida?

You’ve been in a crash, and now you are staring down a confusing question: whose insurance pays for what, and in what order? Florida’s system is layered, and understanding how the pieces fit together is the difference between leaving money on the table and getting everything you are owed. Here is how auto accident claims actually work in Florida, step by step, after a car accident. The Reyes Firm Confused About Your Tampa Accident Claim? Let us map out every layer of coverage for you. Had a bad day? Contact Us Now $10,000 PIP benefits, regardless of fault Fla. Stat. § 627.736 80% / 60% PIP pays of medical bills / lost wages Fla. Stat. § 627.736 UM Coverage Protects you if the other driver has none Fla. Stat. § 627.727 2 Years Deadline to file a lawsuit Fla. Stat. § 95.11 Florida is a no-fault state, which gives its auto accident claims a structure that surprises a lot of people. Instead of one insurance company simply paying for everything, different coverages handle different parts of your losses, and they come into play in a particular order. Once you see how the layers stack up, the whole process becomes far less mysterious. How do auto accident claims work in Florida? Auto accident claims in Florida work as a layered system rather than a single payout. Your own Personal Injury Protection handles your immediate medical costs regardless of fault, the at-fault driver’s bodily injury coverage handles your pain and suffering after a settlement, and your uninsured motorist coverage protects you when the responsible driver cannot. Which layers apply, and how much each pays, depends on the coverage involved and the severity of your injuries. Think of it as a chain, where each link does a specific job. Understanding what each link covers, and when it comes into play, is the key to making sure nothing that should be paid gets missed. What does your PIP cover after a crash? Your Personal Injury Protection is the first link in the chain. Under Florida Statute § 627.736, PIP pays your medical bills and a portion of your lost wages regardless of who caused the crash, which is the heart of the no-fault system. Specifically, PIP generally covers 80% of your reasonable medical expenses and 60% of your lost wages, up to a combined limit of $10,000. There are two catches worth knowing. First, you must seek initial medical care within 14 days of the crash, or you can lose your PIP benefits entirely. Second, the full $10,000 is generally available only if a medical provider determines you had an emergency medical condition; without that finding, your PIP benefits may be capped at $2,500. This is your own coverage, so it applies no matter who was at fault. How do you recover for pain and suffering? PIP does not pay for pain and suffering, so that part of your claim comes from a different link in the chain: the at-fault driver’s bodily injury liability coverage. When another driver causes your injuries, you can pursue a claim against their coverage for the human cost of the crash, including pain, suffering, and the impact on your life, and that recovery typically comes as part of a settlement rather than upfront. There is an important condition, though. In a Florida car accident, you generally cannot step outside the no-fault system to recover pain and suffering unless your injury meets a legal threshold. That is a key reason serious injuries are treated so differently from minor ones, and why proper medical documentation matters so much to the value of your claim. 💡 Did You Know? In a Florida car accident, you generally cannot recover for pain and suffering unless your injury meets a threshold such as permanent injury within a reasonable degree of medical probability, significant permanent scarring or disfigurement, or significant and permanent loss of an important bodily function. This is why the nature and permanence of your injury drives the value of your claim. Source: Fla. Stat. § 627.737(2). What if the at-fault driver has no insurance or too little? This is where the next link matters, because a great many Florida drivers are on the road with no insurance or the bare minimum. If the driver who hit you cannot cover your injuries, your own uninsured and underinsured motorist coverage under Florida Statute § 627.727 can step in to fill the gap. Here is a detail many people miss: you may have this coverage even if you do not remember buying it, because Florida requires insurers to offer it and to obtain your rejection in writing. If you never signed a written rejection, there is a good chance the coverage is on your policy. We go deeper into this in our guide on what to do when you are hit by a driver with no insurance. What happens if the crash was your fault? Even then, you are not left with nothing. Because Florida is a no-fault state, your own PIP still pays your medical bills and a portion of your lost wages regardless of who caused the crash. That is the whole point of no-fault coverage: your immediate medical needs are handled by your own policy first, no matter who was to blame. What changes when you are at fault is your ability to recover for pain and suffering, since that comes from the other driver’s coverage. For the damage to your own vehicle, your collision coverage, if you carry it, can pay for repairs regardless of fault, subject to your deductible. 🛡️ Your Rights Under Florida Law: Under Florida Statute § 768.81, your compensation is reduced by your share of fault, and you may be barred from recovery if you are found greater than 50% responsible. Because fault directly affects what you can recover, insurers work hard to assign as much of it to you as possible, and an experienced Tampa injury lawyer works to keep the facts straight. How do the

Accident Injuries & why, After A Car Accident, After an Accident, Legal, Our Community, Personal Injury, personal injury attorney, Police Interaction, Settlement, Uninsured Motorists Coverage, Why we serve

How Important is it to have a Police Report?

I have a question related to personal injury. How important is having a police report when you are making a personal injury claim? Or just reporting to your insurance company that you’ve had an accident and maybe you just felt like oh I didn’t call the police because I was in a hurry, but then later you’re reporting your insurance the damage. Can you talk a little bit about that? Yeah, that’s a great question because a lot of people don’t want to wait for the police and they just want to exchange information. It’s important for you to get a police report because you need documentation because everybody inherently is telling the truth at that time when people are around. But the moment you drive away people start lying and they start saying I didn’t say that. The person hit me, or this is how it happened. Then we run into an issue of liability and then the insurance company will deny, the at-fault party will deny coverage because they’ll say it’s not their drivers’ fault. Their driver said something different when they did the recorded statement. So, now we have the problem of we may have to file suit and go through this process. It creates something I could have taken maybe an hour. Now it takes months and months even if you even get to that point. If it’s not very clear-cut. So, it’s very important and on the same subject, we need to get this. We need to ask for a long-form. A lot of sheriffs and law enforcement they don’t actually want to do this because it’s a lot of work. But a lot of times they just want to do a quick thing if there are no injuries because people feel pain the next day. They’d always feel pain the same day unless it’s pretty substantial. Then I say feel I got hit by a truck, so the long-form it goes into deeds detail and it was like a narrative of what they write in detail of what happened in the accident and it’s all a map. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411In short form they don’t do any of those things. So and then, later on, we have one that the police cited that the other party at fault but because they didn’t do a long-form there the teenage driver that hit my client that my client didn’t speak English which is another problem we can talk about because they discriminate a lot towards people don’t understand the language. They took the word of a 17-year-old high school kid that wasn’t his fault after the police cited him and that they rejected liability because they said there’s no narrative on the long-form. So now we must file suit, in the end, we call the sheriff like it’s been a few months I don’t remember I did. So, it’s very important that you had a police report on a long-form. Is there any way to remedy it later on after the accident has passed several days can you call the police back at that point or what yeah what’s common practice? Yeah, we do. We call the police, we look for witnesses, we look at the actual damage the pictures to the car itself because that tells the story a lot of times because they might say whatever but in depending on how the car is dented how the impact was, there’s no way another scenario we have another one they said Oh your client, our client like but your client their phone in the car is completely damaged. So, for sure the pictures that your client hits something he’s substantial. The front end and my client have a date like they hit a pole so the pictures up a lot of witnesses and putting a little bit of pressure and we’ve been able to change my ability. But it is it’s more difficult more challenging. Yeah but this very thing is definitely an issue and that leads me to an immigration question. For more questions, call us at 833-4-BAD DAY (833-422-3329).   (Transcript from the video, transcribed but not reviewed)

Are you Getting a Fair Settlement
Accident Injuries & why, After A Car Accident, After an Accident, Car accident, Legal, Settlement, Why we serve

Are you Getting a Fair Settlement?

So, the insurance company offers you a fair settlement after you involved in an accident? It’s hard to talk about this without laughing because the insurance companies work for the insurance company. Those agents don’t work for you, instead, they work for the insurance company so they’re never going to offer you a fair settlement right off the bat without representation or without fighting them. Their job is to adjust the claims out and pay as little as possible to you for your lost wages, pain, and suffering. Tampa personal injury lawyer Edward Reyes represents people in Tampa and Hillsborough County, Florida who have suffered an injury in an incident or accident type of accident. Speak Directly to Me, At No Cost, Today 813.421.3411So, the question or myth is- do they pay you a fair settlement? No, they never pay you a fair settlement off the top. After you find them, you put force, and you show them that you’re not playing around with proper representation and then the settlement becomes fair. So, if you have any questions on this feel free to give us a call at 813.421.3411 and we’ll be more than happy to go through this process with you to help you understand how and what a fair settlement actually is. (Transcript from the video, transcribed but not reviewed)

Pain and suffering compensation guide
Accident Injuries & why, After an Accident, Car accident, FAQ, Health, Injury, Legal, Settlement

Should I Get Paid for Pain and Suffering? | Tampa, FL

You’re in real pain. The medical bills are only part of it — you can’t sleep, you can’t do the things you used to love, and a car accident you didn’t cause turned your daily life upside down. So can you actually be paid for that suffering, not just your bills? Here’s how pain and suffering compensation works in Florida. TL;DR — QUICK SUMMARY Yes, you can recover money for pain and suffering after a Florida crash that wasn’t your fault, but only if your injuries clear Florida’s serious-injury threshold. Pain and suffering is a type of non-economic damage. It covers physical pain, mental anguish, loss of enjoyment of life, and inconvenience, on top of your medical bills and lost wages. Florida’s no-fault system means your own PIP pays your first $10,000 in bills regardless of fault, but pain and suffering generally comes from the at-fault driver once you meet the injury threshold under Florida Statute § 627.737. There’s no fixed formula. The value depends on the severity and permanence of your injuries, your treatment, and how the crash has changed your life. You have two years from the date of your crash to file a personal injury lawsuit under Florida Statute § 95.11(3)(a). Uninsured/underinsured motorist coverage can also be a source of recovery if the at-fault driver has no insurance. The Reyes Firm Hurt and in Pain After a Tampa Crash? Find out what your pain and suffering claim may be worth. Had a bad day? Contact Us Now 2 Years Florida statute of limitations Fla. Stat. § 95.11(3)(a) $10,000 Florida PIP minimum coverage Fla. Stat. § 627.736 4 Ways To meet FL injury threshold Fla. Stat. § 627.737(2) 50% Fault bar to recovery in FL Fla. Stat. § 768.81 Can you get paid for pain and suffering after a Florida car accident? Yes, you can be compensated for pain and suffering, as long as the crash wasn’t your fault and your injuries are serious enough to clear Florida’s threshold. Whether it actually happens depends on the facts: how badly you were hurt, whether the at-fault driver had insurance, and whether they have assets to reach if they didn’t. If you’re in genuine pain, you should be able to recover for that pain, for the loss of enjoyment of life, for time you couldn’t work, and for the damage to your vehicle. That’s the principle. In practice, it doesn’t happen automatically, which is why how you handle your claim matters so much. One of the biggest obstacles is uninsured drivers. Florida has a high number of people driving without adequate coverage, which is exactly why carrying uninsured/underinsured motorist coverage on your own policy is one of the smartest protections you can have. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you have two years from the date of your crash to file a personal injury lawsuit. Wait too long and you can lose the right to recover anything for your pain and suffering, no matter how badly you were hurt. Don’t let the clock run out. What counts as pain and suffering in a Florida injury claim? Pain and suffering is a category of non-economic damages, meaning losses that don’t come with a receipt. Unlike a medical bill or a paycheck stub, these harms are real but harder to put a dollar figure on, which is exactly why insurers fight them. In a Florida injury claim, pain and suffering can include physical pain from your injuries, mental anguish and emotional distress, loss of enjoyment of life, inconvenience and disruption to your routine, and the lasting effect of scarring or disfigurement. A serious back or neck injury that limits you for years carries very different value than a sprain that heals in weeks. These damages sit on top of your economic damages, which cover medical bills, future treatment, lost wages, and lost earning capacity. Together they make up the full value of your claim. Watch: Should you get paid for pain and suffering in Tampa? In this short video, Tampa personal injury attorney Edward Reyes explains when you can recover for pain and suffering after a Florida crash and what factors affect it. If you’re hurting and unsure whether your injuries qualify, The Reyes Firm offers a free case review to walk you through where you stand. How does Florida’s injury threshold affect pain and suffering? Florida’s injury threshold is the gateway to recovering pain and suffering from an at-fault driver. Because Florida is a no-fault state, your own Personal Injury Protection (PIP) coverage pays your first medical bills regardless of who caused the crash, but PIP does not pay for pain and suffering. To step outside no-fault and pursue non-economic damages from the at-fault driver, your injury generally has to meet the serious-injury threshold in Florida Statute § 627.737. That statute recognizes injuries involving significant and permanent loss of an important bodily function, permanent injury within a reasonable degree of medical probability, significant and permanent scarring or disfigurement, or death. Whether your injury clears that threshold is often the central fight in a Florida case. Strong medical documentation and the right expert opinions are what move an injury from “soft tissue” in the insurer’s eyes to a permanent, compensable harm. 💡 Did You Know? Florida’s PIP system pays up to $10,000 in medical bills and lost wages no matter who caused the crash under Fla. Stat. § 627.736 — but PIP never pays for pain and suffering. Those damages only become available once your injury meets the threshold in Fla. Stat. § 627.737. How is pain and suffering calculated in Florida? There is no fixed formula for pain and suffering in Florida. Two cases with similar bills can settle for very different amounts depending on how the injuries affect each person’s life, which is why a number pulled from an online calculator means little. In practice, the value turns on factors like the severity and permanence of your injuries, the length and intensity of your treatment, whether you’ll

Get the right attorney after an accident
After A Car Accident, After an Accident, FAQ, For Parents, For Teens, Legal, Pedestrian Accident, Personal Injury, personal injury attorney, Road Accidents, Settlement, Why we serve

Do you Really Need an Attorney After an Accident?

You were just going about your day. Then a car accident changed everything, and now you’re wondering whether you really need a lawyer or can just handle the insurance company yourself. Meanwhile, the adjuster who already called you sounds friendly and helpful. Here’s what you need to know before you decide to go it alone. TL;DR — QUICK SUMMARY You are not legally required to hire an attorney after an accident, but it is strongly recommended any time you’ve been injured. Insurance adjusters work for the insurance company and its policyholder, not for you, and their goal is to settle for as little as possible. An attorney levels the field by knowing the law, valuing your claim correctly, and handling the insurers so you don’t say something that hurts your case. Under Florida Statute § 95.11(3)(a), you generally have two years from the crash to file a personal injury lawsuit, so waiting too long can cost you no matter what. Most personal injury attorneys, including The Reyes Firm, work on contingency, so you pay nothing upfront and owe fees only if they recover for you. The Reyes Firm Not Sure If You Need a Lawyer? Get a free, honest answer about your accident. Had a bad day? Contact Us Now 2 Years Florida statute of limitations Fla. Stat. § 95.11(3)(a) 14 Days To seek care and keep PIP benefits Fla. Stat. § 627.736 Free Initial case consultation The Reyes Firm 50%+ Fault that bars recovery in Florida Fla. Stat. § 768.81 Do you really need an attorney after an accident in Tampa? No, you are not legally required to hire an attorney after an accident, but having one is strongly recommended any time you’ve been hurt. Think of it less as a requirement and more as a necessity, the way gum isn’t required after bad breath but is highly advisable. An attorney works in your best interest. They know when someone is trying to take advantage of you, they understand the laws that apply to your claim, and they’re ready to fight when fighting is what it takes. The other side already has trained professionals protecting their money. The question isn’t really whether you’re allowed to go it alone, but whether you should. When can you handle an accident claim without a lawyer? You can sometimes handle a claim on your own when the accident was truly minor, no one was injured, fault is clear and undisputed, and the only issue is modest property damage. In those situations, the stakes are low enough that hiring a lawyer may not change the result. The moment any of that breaks down, the calculus changes. If you were injured, if fault is in question, if multiple parties or a commercial vehicle are involved, or if the insurer is delaying or lowballing you, the value of professional help climbs fast. A free consultation is the easiest way to find out which situation you’re actually in. ⚠️ Deadline Warning: Under Florida Statute § 95.11(3)(a), you generally have two years from the date of your crash to file a personal injury lawsuit. Missing this deadline almost always means losing your right to recover anything. Don’t wait to call a lawyer. Watch: Do you really need an attorney after an accident? In this short video, Edward Reyes, Esq. explains why an attorney is less of a requirement and more of a necessity after an injury accident. If you still have questions after watching, The Reyes Firm offers a free consultation so you can talk through your specific situation with a real attorney. Why don’t insurance adjusters work in your best interest? Insurance adjusters don’t work in your best interest because they don’t work for you. The adjuster, the opposing party, and the insurance company are all working to protect their insured and their own bottom line, which means paying you as little as possible. That’s not a personal attack on adjusters; it’s their job. They’re trained negotiators who handle claims every day, while you may be doing this for the first time in your life, in pain, and under financial pressure. A friendly phone call early on is often designed to get you talking before you understand what your claim is really worth. 💡 Did You Know? You can hire an experienced Tampa injury attorney without paying anything upfront. The Reyes Firm works on a contingency fee basis, so you owe attorney fees only if the firm recovers compensation for you — which means cost is rarely a reason to face the insurance company alone. Source: The Reyes Firm fee policy. What does a personal injury attorney actually do for you? A personal injury attorney does the work that protects your recovery while you focus on healing. Rather than leaving you to guess at the process, they take over the parts that most often go wrong when people handle claims alone. In practical terms, a good attorney typically: Values your claim correctly, accounting for future medical care and long-term impact, not just the bills already in front of you Handles all communication with adjusters, so you don’t accidentally say something that gets used to reduce your payout Gathers and preserves evidence, including the police report, medical records, photos, and witness statements, before they disappear Identifies every source of coverage, including policies you may not realize apply to you Negotiates from a position of strength, and is prepared to file suit if the insurer won’t pay fairly Does a lawyer affect how much fault matters in your case? Yes, because how fault is assigned has a direct effect on what you recover, and that’s an area where representation matters. Insurers routinely try to shift blame onto the injured person to shrink what they owe. A lawyer’s job is to push back on unfair blame with the actual evidence. Even a modest reduction in your assigned share of fault can mean a meaningful difference in your recovery, which is exactly the kind of fight you don’t want to

Scroll to Top